
Costco (COST) Stock May Be Priced For Perfection On Earnings
Costco Wholesale stock has logged strong returns in recent years, and the current price near US$1,018 per share puts fresh focus on whether that level is supported by its earnings power. For investors, the core issue is how much of the recent share price strength reflects the warehouse retailer’s actual profit engine versus expectations layered on top.
- Over the past 5 years the stock has gained 118.7%, which raises the question of how much earnings strength is already embedded in today’s valuation.
- Membership fees, volume buying and tight cost control can support consistent profitability, which matters because the market is effectively capitalizing those earnings into the current share price.
- The analysts covering Costco Wholesale have run their own numbers. See what analysts think Costco Wholesale's shares could be worth.
The issue now is whether Costco Wholesale’s current market value is justified by the earnings the business is generating today.
If you like testing whether Costco Wholesale’s earnings justify its price, it can help to benchmark that thinking against a wider group using our 30 high quality undervalued stocks.
Does Costco Wholesale Look Pricey on Earnings?
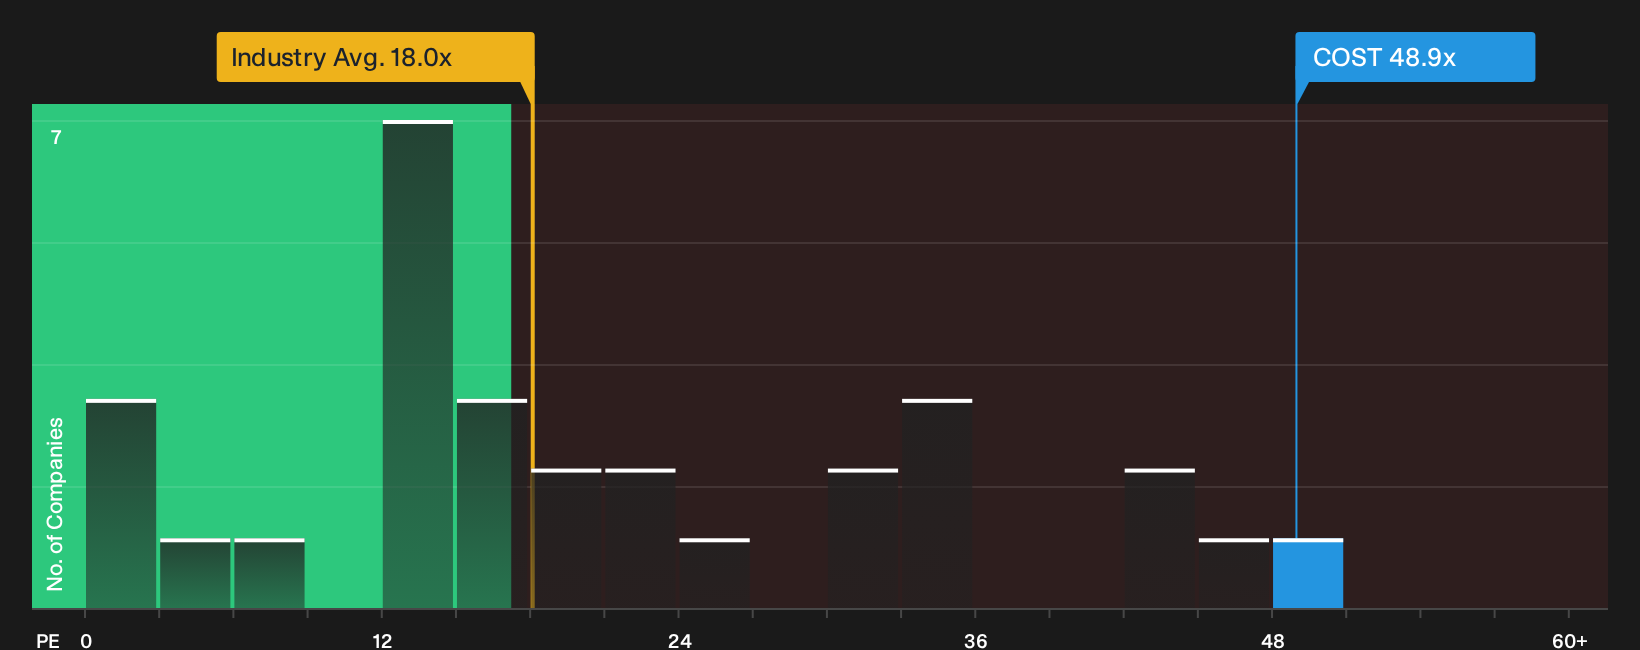
The P/E ratio suits Costco Wholesale because earnings remain the main anchor for how investors look at this retailer. On that yardstick, the stock trades on about 48.9x earnings, which is more than double the Consumer Retailing industry average near 19.0x and also sits well above the peer group around 23.3x. That kind of gap tells you buyers are paying a premium multiple for each dollar of Costco Wholesale profit.
A tailored fair P/E that adjusts for the company’s scale, margins and risk profile sits lower than the current 48.9x, which points to the shares screening as overvalued on this framework. For anyone considering Costco Wholesale today, the key question is whether the membership model, cost discipline and cash generation you see in the numbers justify paying that kind of earnings premium relative to sector norms. Explore the numbers behind Costco Wholesale's P/E valuation.
The Costco Wholesale Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Costco Wholesale pick up where the P/E puzzle leaves off and spell out which paths for future growth, margins and earnings would need to play out for the stock to be worth meaningfully more or less than today’s price on the Community page. Instead of giving just a single valuation output, they lay out the underlying future that number relies on so you can see what needs to happen and track whether it does.
Community views on Costco Wholesale are split between those who see more upside left and those who think the valuation already demands perfection.
Bull case: roughly fairly valued
"The current valuation, together with this narrative’s view that Costco Wholesale is undervalued, implies the share price does not fully reflect the company’s planned warehouse build out, growing ancillary mix and rising contribution from digital and AI driven sales and membership acquisition…"
Discover why this Narrative puts Costco Wholesale at roughly fairly valued.
Bear case: 40% overvalued
"Based on my projections through 2031, Costco is "priced for perfection." My Base Case (Mid) suggests an Annualized Return (IRR) of just 5.6%, largely because valuation compression is likely to offset operational growth…"
Explore why this Narrative puts Costco Wholesale at 40% overvalued.
One Costco Wholesale factor the valuation does not answer
Share price and P/E only tell part of the story because the people setting priorities, and how they are rewarded for doing it, can heavily influence where the business goes next. See who runs Costco Wholesale and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com