
3 Japanese Undervalued Stocks Trading Up To 45% Below Fair Value
Japanese high quality stocks suddenly look more interesting after the critical PHP security flaw pushed governments, including Japan, to raise cyber risk alerts and even suspend some online services. When trust in digital systems is tested, investors often look for companies with strong finances and dependable cash generation. This article highlights three financially robust Japanese stocks that appear underpriced on our value screen.
These three Japanese high quality stocks are only a sample, since the full screen surfaced 11 more companies with similarly compelling fundamentals and valuation stories that are not covered below.
To identify and analyze the highest conviction opportunities from this broader group, head straight into the High Quality Undervalued Stocks screener
NEXTAGE (TSE:3186)
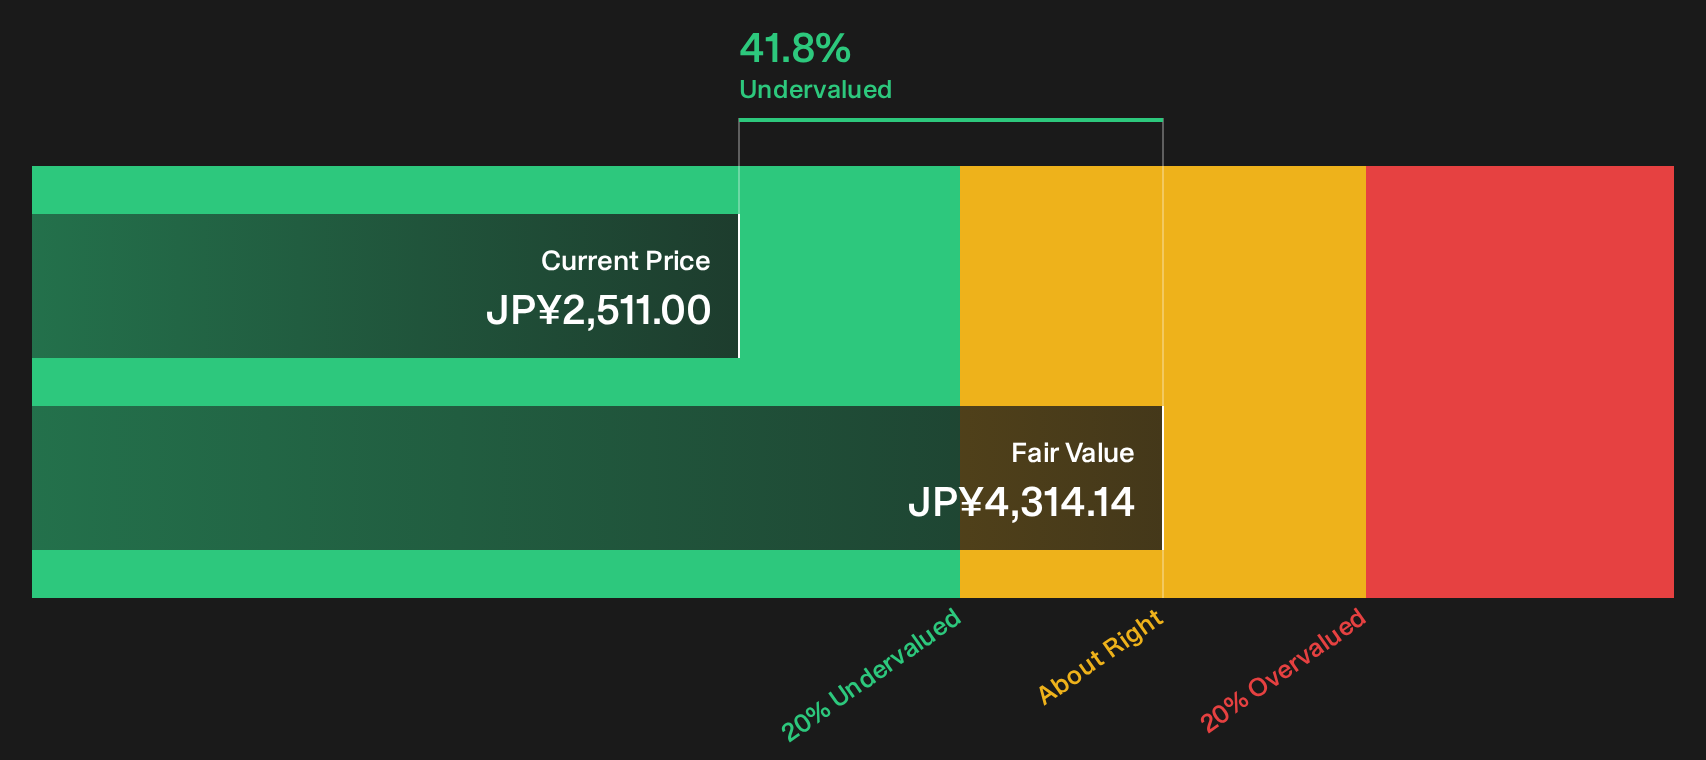
NEXTAGE runs a nationwide network selling new and used cars in Japan, with its theme-linked used vehicle trading and related services driving all ¥775.8b of revenue from “Automobile Sales and Associated Services.” The stock carries a market value of about ¥197.0b.
NEXTAGE combines a cash-heavy used-car operation with a value score that flags the shares as significantly below estimated fair value, and recent guidance points to sizeable sales and profit in 2026. The key question is how far margins can stretch if one pressure point on cash stays contained.
If you want to see how far that margin story can really run, scan the 4 key rewards and 2 important warning signs (1 is major!) while the valuation gap still looks wide.
Yokohama Financial Group (TSE:7186)
Yokohama Financial Group is a Tokyo based lender focused on commercial and consumer loans to small and medium sized businesses, generating all ¥399,402 million of revenue from banking activities in Japan, and carries a market value of about ¥1.85 trillion.
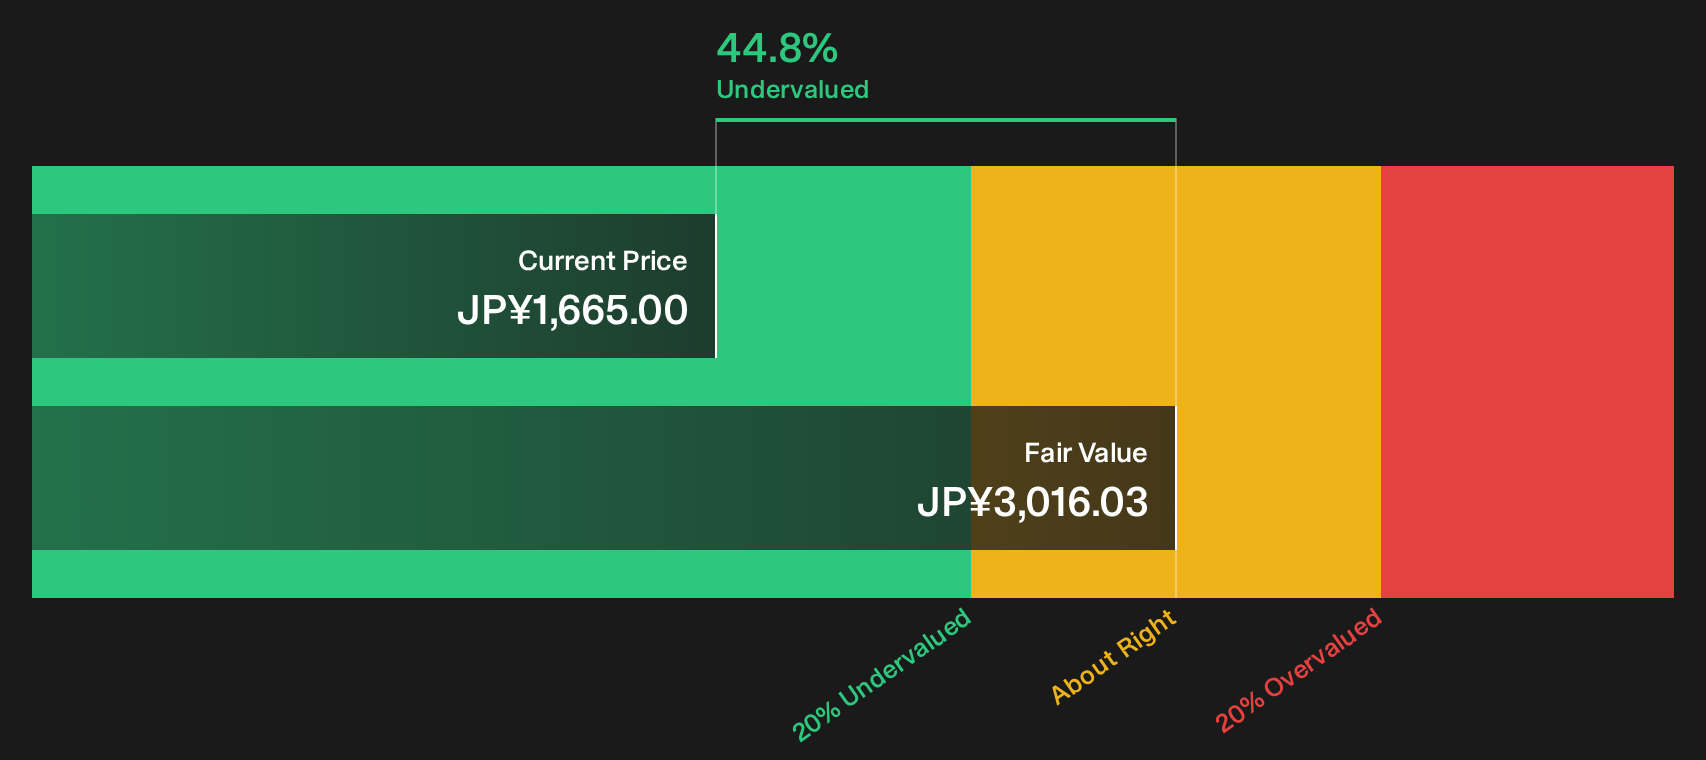
Yokohama Financial Group brings together SME focused lending cash flows, a dividend yield near 2.82% and a P/E around 16.6x that is close to peers. At the same time, screens flag roughly a 44.8% discount to fair value, so the real question is how the loan loss cushion holds up if one pressure point in SME credit costs shifts.
If that credit cushion has your attention, review the 5 key rewards and 1 important warning sign to see how Yokohama Financial Group’s valuation and risk profile could be decoupling from SME headlines.
Kasumigaseki CapitalLtd (TSE:3498)
Kasumigaseki Capital Ltd is a Tokyo based real estate consulting and asset developer, running apartment hotels, logistics warehouses and a solar power generation arm that brings in recurring energy income. All ¥163,756 million revenue comes from its Real Estate Consulting Business in Japan, and the stock is valued at about ¥165.0 billion.
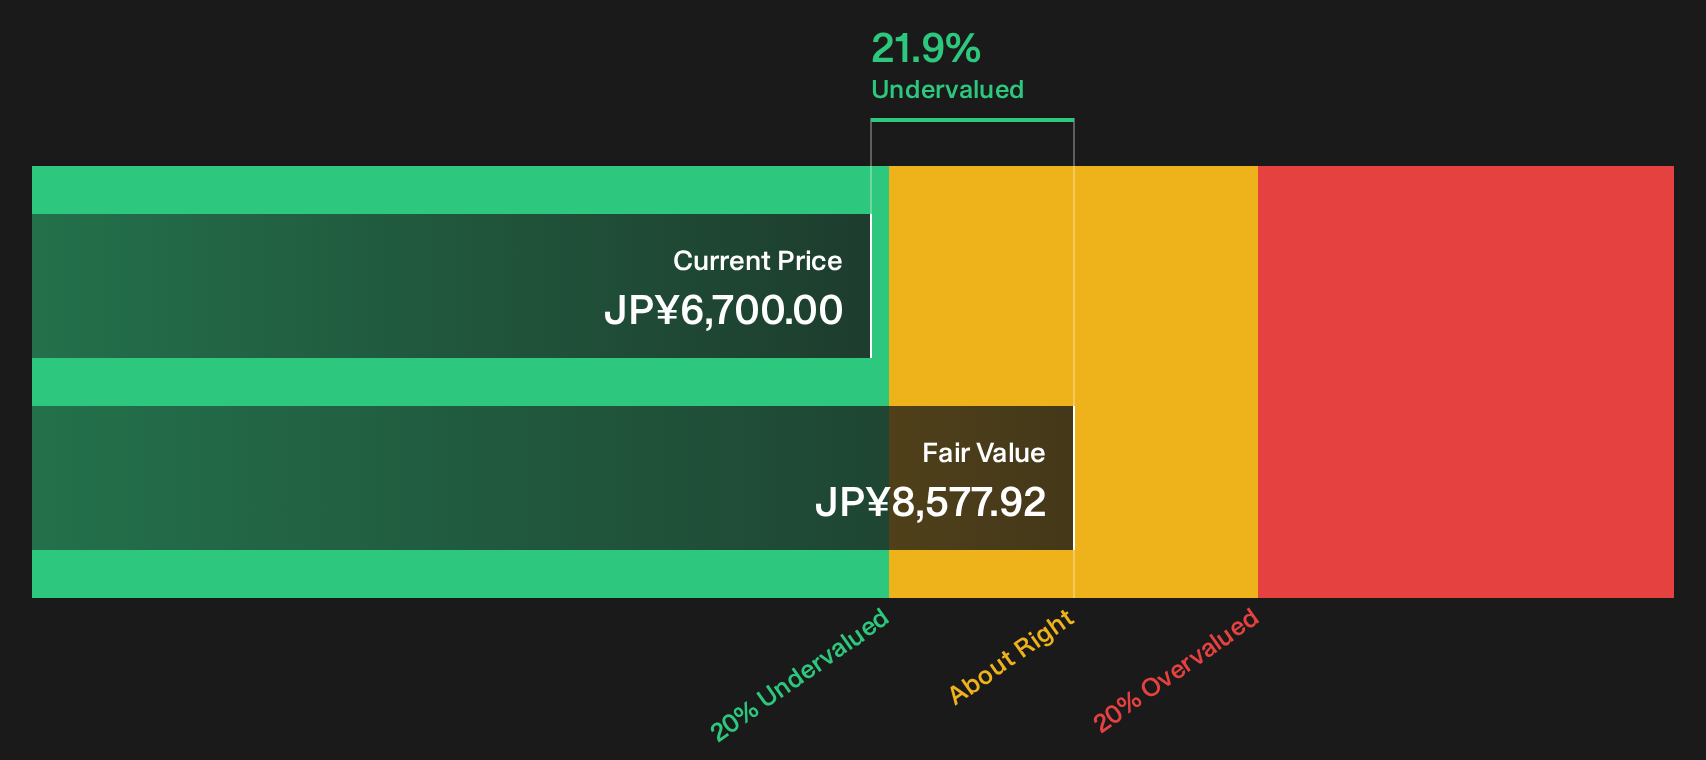
Kasumigaseki Capital Ltd combines recurring solar power income and asset backed projects with an estimated 21.9% discount to fair value and earnings that have recently outpaced the wider real estate group. That mix of cash flow support and pricing appeal could look very different if funding costs or access to credit shift in the next phase of its build out.
If funding costs and credit access are the swing factors, read the 5 key rewards and 5 important warning signs (2 are major!) for Kasumigaseki CapitalLtd before the next phase is fully priced in.
Seeking Alternatives Before The Crowd
Fresh ideas move first. By the time momentum headlines hit, the early entries are already flying. Scan these under the radar lists while it still matters and consider them before they become crowded.
- Identify resilient income opportunities before yields are affected by late money using the curated 29 dividend fortresses currently hiding in plain sight.
- Follow high conviction growth themes in automation and industrial efficiency through a focused group of 93 robotics and automation stocks designed to provide targeted exposure to this area.
- Review potential capacity constraints in electricity demand using a hand picked pool of 42 power grid technology and infrastructure stocks that may be positioned to respond to changes in grid spending.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com