
NVE (NVEC) Stock Price Cracks After Q2 Results Expose Demand Risks
NVE just reported Q2 FY2027 results and the stock reaction has been brutal. After closing at US$103.07 before the release, the shares finished the next session at US$68.36, a one day collapse of 33.7% that wipes out months of gains.
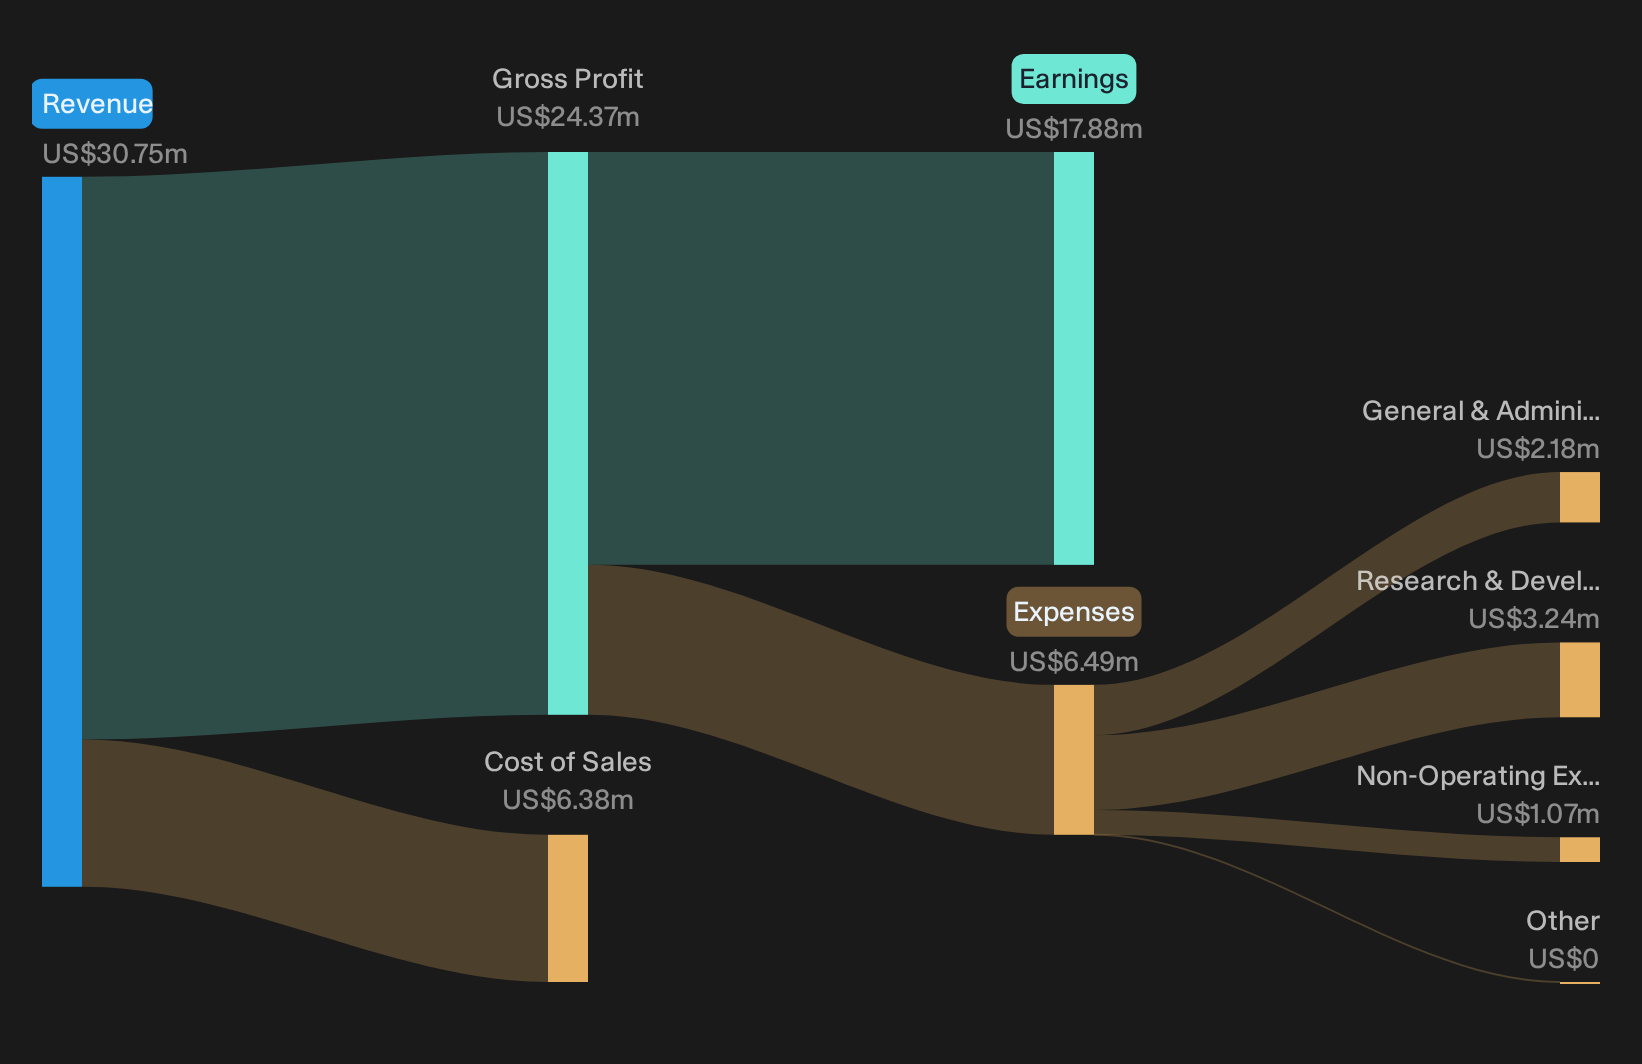
The trigger was a semiconductor report card that looked more nuanced than that plunge suggests. Quarterly revenue landed at US$5.8m with net income of US$3.2m, while profitability stayed unusually high for this sector as net margin held around the mid 50s. The real story here is sentiment, not solvency, and the gap between those two is what matters now.
Love NVE’s rich margins but worried about how quickly sentiment flipped after this report? You can screen for semiconductor peers that combine strong profitability with steadier share price trends in our list of solid balance sheet and fundamentals stocks (26 results).
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs. Q2 2026): US$5.83m vs. US$6.35m (declined 8.1%)
- Net Income (Q2 2027 vs. Q2 2026): US$3.17m vs. US$3.31m (fell 4.2%)
- Basic EPS (Q2 2027 vs. Q2 2026): US$0.66 vs. US$0.68 (edged down 4.3%)
- Net Profit Margin (Q2 2027 vs. prior 12-month level): 54% in the quarter vs. 58.1% over the last 12 months (compressed from very high trailing margin)
NVE bullish story meets resilient margins
NVE Corporation’s niche sensor and spintronics story still leans on one clear strength. The income statement holds very high gross, operating and net margins even in a quarter when revenue declined 8% and EPS slipped slightly. Cash generation also looks firm with US$11.1m from operations and US$44.4m in cash and securities, plus ongoing dividends. For a business tied to industrial, medical and automation themes, this mix of rich profitability and a clean balance sheet keeps the longer term “specialized enabler” narrative directionally intact, despite a sharp reset in the share price.
Short term setbacks fuel the bearish read
The bear story around NVE focuses on concentration risk and lumpy demand. Q2 captures that pattern clearly. Product revenue fell as defense orders dropped and a large medical customer adjusted inventories, even as distributor sales jumped 67% and contract R&D grew. Year to date figures are stronger. However, the single day decline of 33.7% and weak 30 to 90 day returns show how quickly sentiment can swing when a small supplier’s key verticals pause ordering, even if management expects conditions to stabilize.
After a one day decline of 33.7% and recent insider selling, it is fair to ask whether this Q2 air pocket is a one off or a sign of deeper fragility. Review the full risk analysis for NVE which shows 4 important warning signsSpot Potential Mispricings Early
NVE has just shown how sentiment can shift fast when expectations meet reported results. The real opportunity is in researching stocks that could be undervalued before wider attention arrives.
- Company 1 - 35% below our estimate - uses expanded manufacturing capacity and high horsepower engine platforms to address data center power needs.
- Company 2 - 28% below our estimate - supplies diagnostic equipment and test systems for utilities and defense contractors upgrading electrical grids and equipment.
- Company 3 - 49% below our estimate - wins long duration contracts for complex public works and military infrastructure tied to extended government buildouts.
Those are three of them. See the full list of 30 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com