
Johnson Controls International (JCI) Dropped, So Why Is It Still Drawing Attention?
With no single headline event driving attention, interest in Johnson Controls International (NYSE:JCI) is focusing on how its recent share performance and fundamentals align for investors tracking building technology and services.
Recent trading has cooled near a last close of US$143.0, with the share price down 5.31% over one day and 3.14% over the past week. However, the 16.92% year to date share price return alongside a 30.91% one year total shareholder return suggests that longer term momentum has held up better than the latest pullback indicates.
Scan beyond Johnson Controls International and compare it with a hand picked 42 power grid technology and infrastructure stocks capturing similar trends in building technology and infrastructure demand.
Bulls point to Johnson Controls International’s steady gains over 1 and 3 years, while bears focus on the recent pullback near US$143. Which story do the current valuation markers support?
Most Popular Narrative: 14% Undervalued
Against a last close of $143.0, the most followed valuation narrative for Johnson Controls International points to a fair value of $165.80. This frames the recent pullback as a move inside a wider undervaluation story built on data centers and services.
The company has significant opportunities for cost reductions and process improvements through the implementation of Lean practices, supported by recent examples of plant capacity increasing several times over without major capital spending, which can help sustain operating leverage and earnings growth.
See why 25 investors see Johnson Controls International as 14% undervalued.
Result: Fair Value of $165.80 (UNDERVALUED)
Still, the Johnson Controls International story can break if complexity drags on efficiency improvements, or if softer Fire and Security demand dulls the data center tailwind.
Find out about the key risks to this Johnson Controls International narrative.
Another View: Johnson Controls International Looks Expensive On Earnings
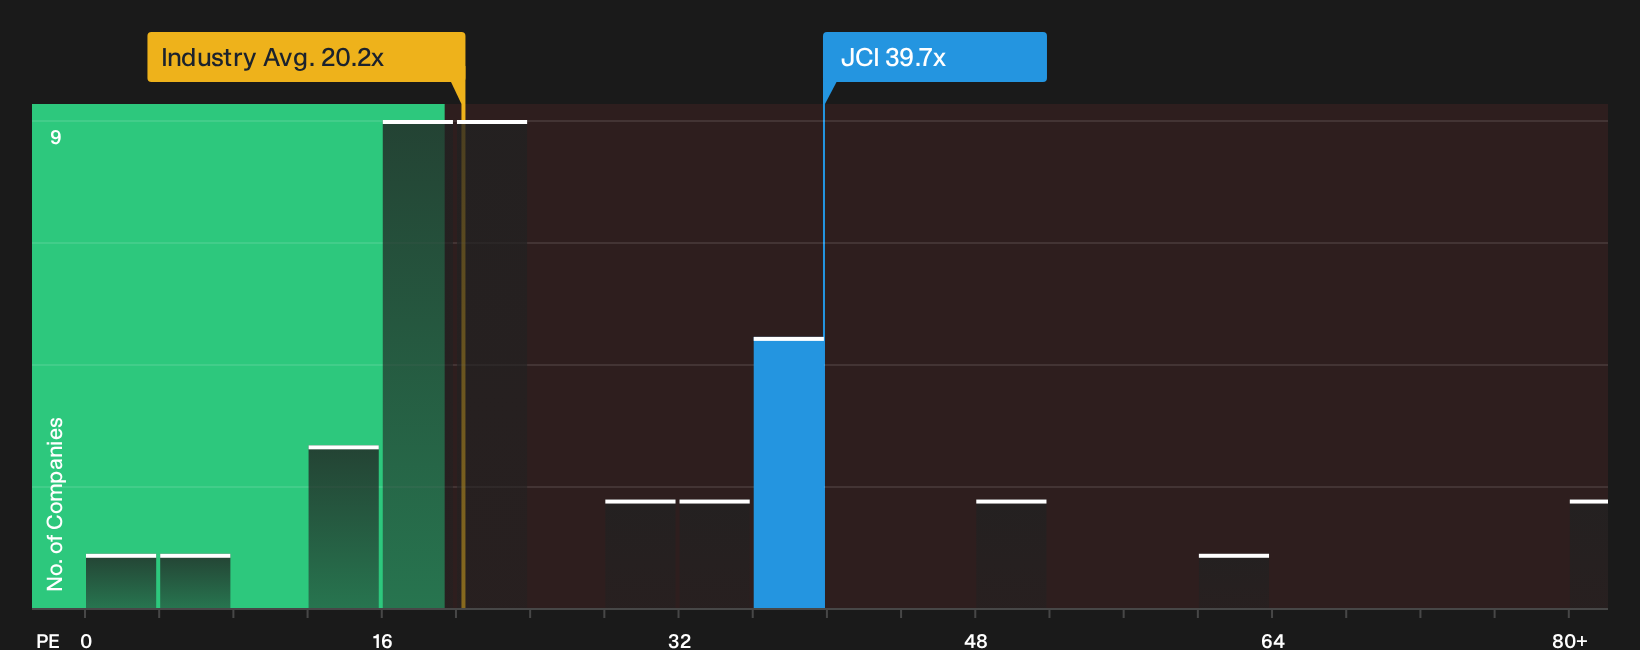
That 14% undervaluation story runs into a very different picture when you look at Johnson Controls International through its P/E. The shares trade on 39.7x earnings compared with a 27.3x peer average and a fair ratio of 35.1x, implying investors are paying up and leaving less room for error.
For anyone weighing those richer multiples against the growth narrative, the key question is whether future execution can justify paying above both peers and the fair ratio, or if expectations have crept too far ahead of the fundamentals. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Conflicted by the mix of optimism and caution around Johnson Controls International? Act quickly and review the full breakdown of its 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Johnson Controls International?
If Johnson Controls International has sharpened your thinking on pricing and expectations, do not stop here. Broader idea hunting through focused screeners can reveal opportunities you might otherwise overlook.
- Target resilient compounding potential by reviewing a curated 30 high quality undervalued stocks that aligns solid fundamentals with pricing that still looks reasonable.
- Prioritise sleep at night holdings through a 30 resilient stocks with low risk scores that filters for sturdier balance sheets and lower overall risk profiles.
- Get ahead of the crowd by scanning 20 high quality undiscovered gems where quality fundamentals have yet to attract wider market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com