
3 AI Data Center Stocks Built For Higher Rates
AI data centers are soaking up power, steel, and capital at the same time borrowing costs are still adjusting to a world of higher rates and heavier government debt. That mix can punish stretched balance sheets yet reward businesses that already generate dependable cash. This article walks through three stocks from our AI Data Center Infrastructure Enablers screener and explains how the recent macro shift could matter for each one.
The three examples below are just a sample, and the full screen surfaced 18 more AI data center infrastructure enablers with equally compelling stories that are not covered here. To identify and analyze your own highest conviction ideas in this theme, head straight into the AI Data Center Infrastructure Enablers screener.
Powell Industries (POWL)
Overview: Powell Industries designs and services custom power distribution gear that helps large facilities, including AI data centers, run reliable high-capacity electrical systems.
Operations: Powell generates about $1.16b from electric equipment, with most revenue from the United States at $907.85 million and Canada at $135.34 million.
Market Cap: US$6.01b
Powell Industries matters for this AI data center infrastructure theme because its engineered switchgear and power systems sit at the point where rising compute demand meets heavy-duty electrical reliability.
"Expectations appear elevated for durable gross margin improvement on the basis of recent project execution, pricing power, and product mix. However, management noted a significant portion of recent margin gains were one-time project closeouts that may not recur, raising the risk of margin normalization and earnings disappointment.
What investors have to weigh now is how Powell’s future AI-driven project mix behaves if a single key assumption about power-project economics breaks.
If that core assumption is what worries you, read the full narrative for Powell Industries to see how Powell Industries could still accelerate or stall from here.

Xi'an Sinofuse Electric (SZSE:301031)
Overview: Xi'an Sinofuse Electric develops and sells high-power fuses and protection components that safeguard data centers, energy systems, and electric transport.
Market Cap: CN¥11.8b
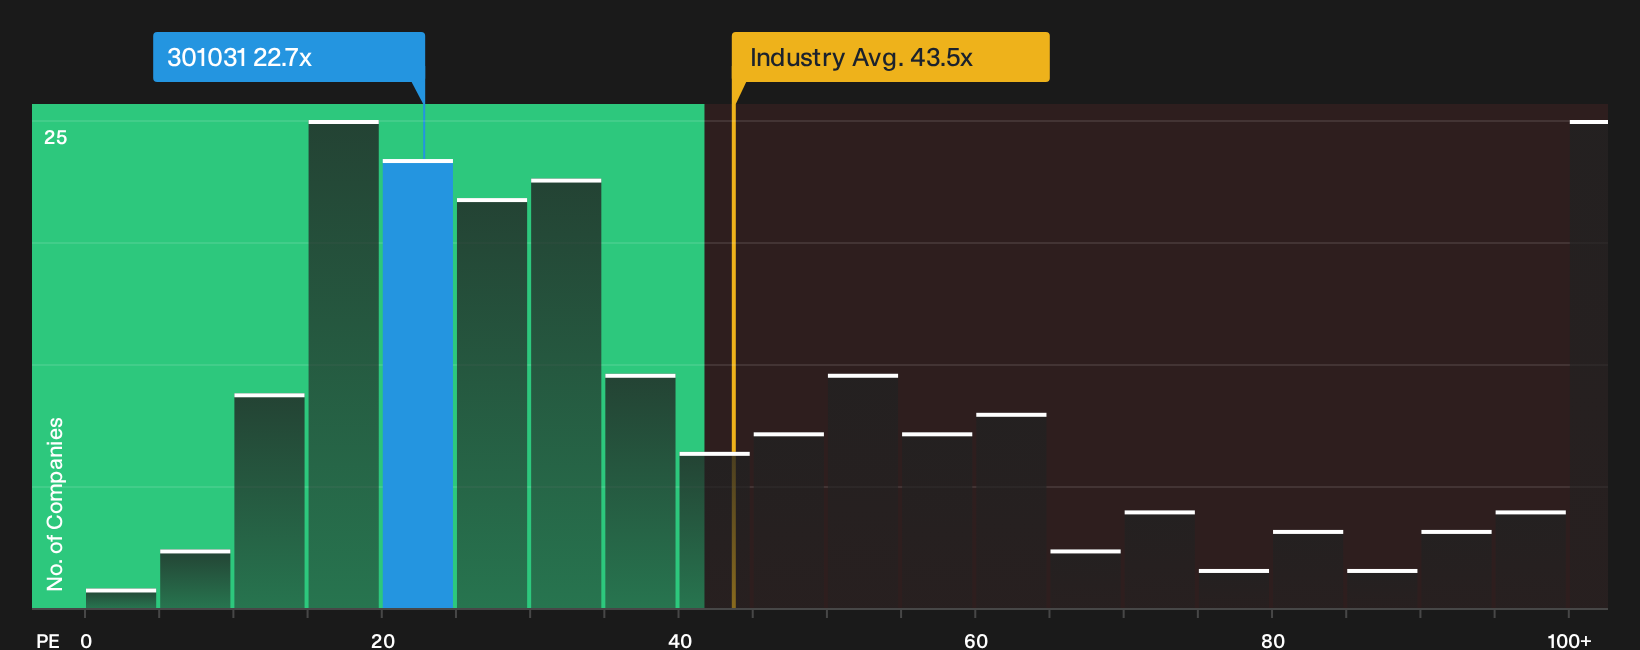
Xi'an Sinofuse Electric provides direct exposure to the electrical protection hardware that keeps AI data centers and other high-load assets online. It is backed by strong profitability metrics and a P/E that sits well below the broader Chinese electrical sector. The key question is how rising capital costs could reshape operators' willingness to pay for premium protection hardware.
That trade off on premium hardware is exactly where the 5 key rewards and 1 important major warning sign starts to show whether Xi'an Sinofuse Electric’s pricing power could be stronger than it looks.
Sweco (OM:SWEC B)
Overview: Sweco is a global architecture and engineering consultancy that plans, designs, and optimizes complex infrastructure, including AI ready data center facilities.
Operations: Sweco generates SEK 9.8b from Sweden, with sizeable contributions from Belgium at SEK 4.2b, Finland at SEK 3.8b, Denmark at SEK 3.3b, the Netherlands at SEK 3.7b, Norway at SEK 3.7b, the UK at SEK 1.5b, and Germany & Central Europe at SEK 3.0b.
Market Cap: SEK 48.1b
Sweco matters for this AI data center infrastructure theme because it sits on the design side of the build out. Smarter power, cooling, and structural planning can make billion krona projects more efficient in a world of higher capital costs.
"The broad roll out of AI tools across Sweco, including an internal platform used weekly by over 70% of employees and targeted at productivity and process automation, creates scope for higher revenue per employee and improved net margins as these tools are embedded in client work."
What investors will be watching next is how one less visible pressure on project economics shapes Sweco's ability to keep lifting profitability.
With that pressure in mind, read the full narrative for Sweco to see how Sweco’s AI rollout, pricing power, and project mix could be quietly accelerating earnings quality.

Seeking Fresh Alternatives Before They Fly
Some of the sharpest breakout stories start quiet, then momentum builds and entry points vanish. Scan these fresh lists before they stop flying under the radar.
- Spot cash-rich businesses before momentum traders catch on by running the list of solid balance sheet and fundamentals (25 results) curated for resilience when conditions suddenly tighten.
- Explore early upside in future-facing miners by scanning the 33 best rare earth metal stocks sourced for exposure to critical metals used in next generation hardware.
- Identify income streams that may help steady portfolio swings by checking the 7 dividend fortresses built around established, high-yield payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com