
Live Oak Bancshares (LOB) Q3 Earnings Cloud Record Operating Profit
Live Oak Bancshares stock barely budged on the Q3 2026 release, up about 1% to roughly US$35.80, which might suggest a routine quarter. The headline result was anything but routine. Reported earnings were hit by a one off US$17 million provision tied to an exited distillery portfolio, masking what management highlighted as record pre provision operating profit and tight cost control.
Short term traders see a modest bounce. Long term holders are weighing a stronger profit engine against the reality of sizable credit clean up and a loan book that continues to expand.
Like the engine under the hood at Live Oak Bancshares but uneasy about the credit clean up and provisioning hit to earnings quality? You can stress test that trade off against banks and lenders in our list of solid balance sheet and fundamentals stocks (25 results)
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): US$120.6m vs US$123.5m (slight top line decline)
- Net Income, Excl. Extra Items (Q3 2026 vs Q3 2025): US$24.3m vs US$25.6m (modest profit contraction)
- Basic EPS (Q3 2026 vs Q3 2025): US$0.52 vs US$0.56 (earnings per share slightly lower)
- Net Interest Margin, or NIM, (Q3 2026 vs Q3 2025): 3.33% vs 3.33% (margin level essentially unchanged)
Prefer clean, visual charts over another dense wall of financial text on Live Oak Bancshares? See the full picture of its balance sheet strength in an at a glance dashboard through our company report for Live Oak Bancshares.
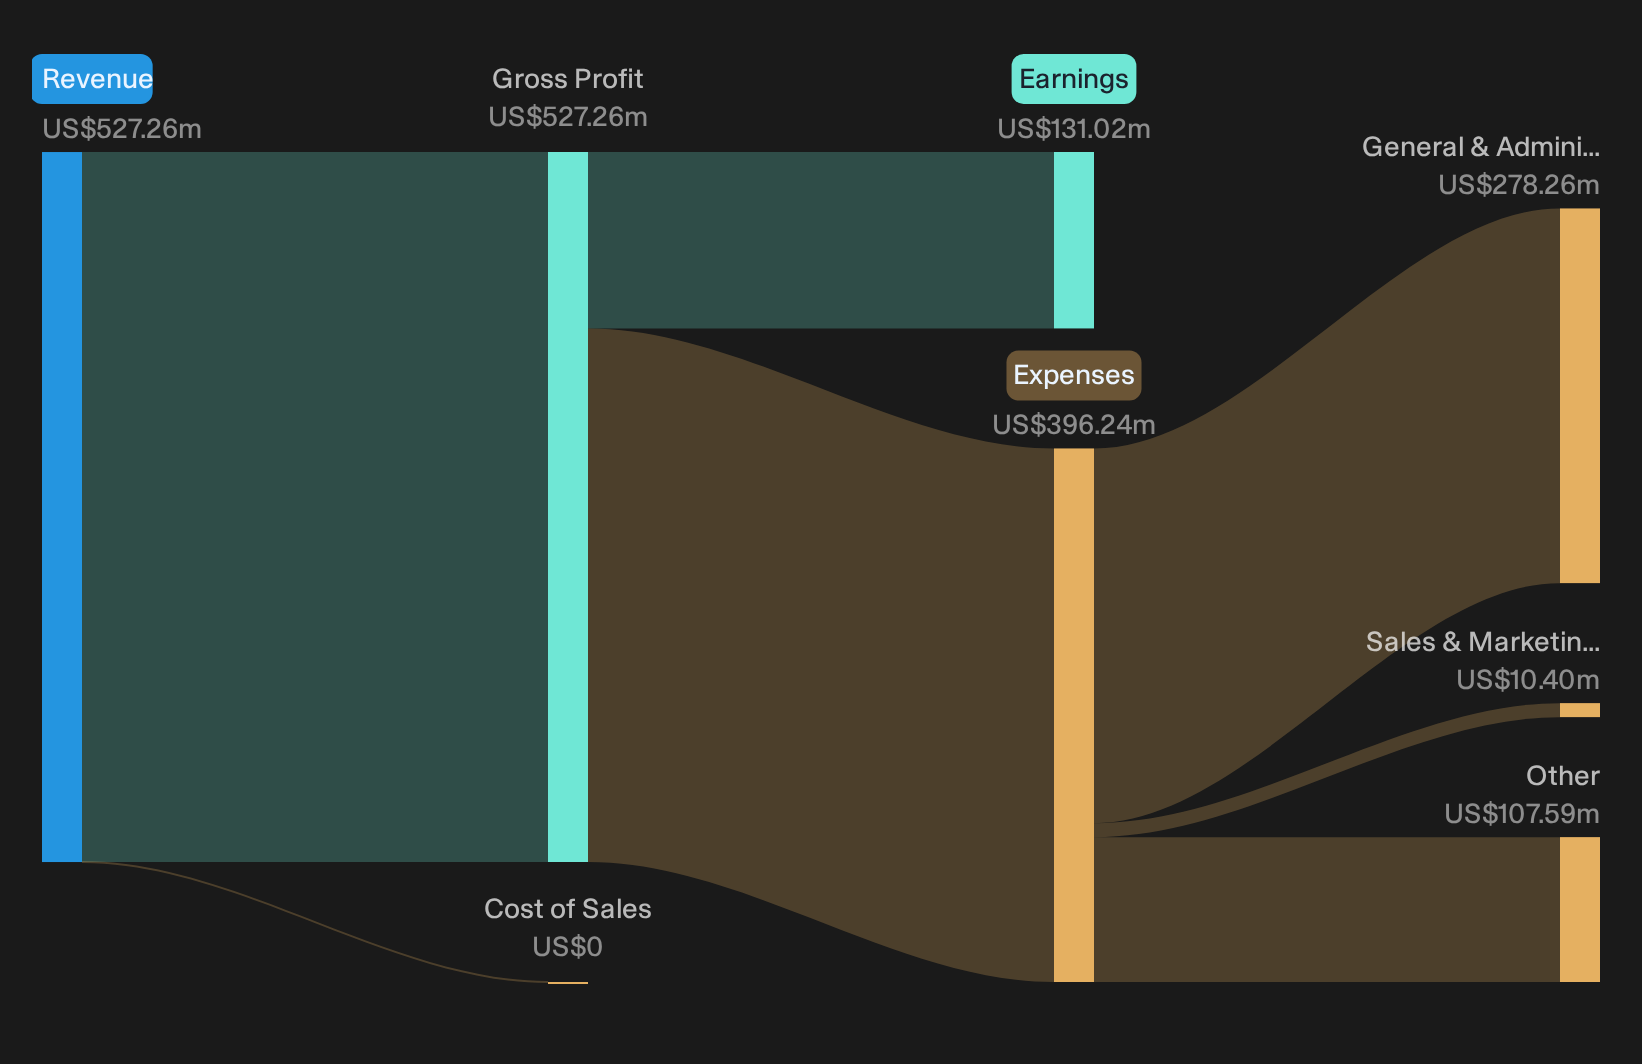
Live Oak bullish thesis meets mixed execution milestones
Supporters argue Live Oak Bancshares can grow faster and run leaner by leaning hard into tech and digital banking.
"Broader use of AI and digital tools, including an AI-native loan origination platform in Live Oak Express and more than 640 internal AI agents available to all employees, is aimed at speeding up underwriting and processing while holding noninterest expense near US$85 million. This can support further operating leverage and net margin improvement."
The quarter backs up part of that ambition. Adjusted PPNR reached US$88m with 15% revenue growth against 1% expense growth and an adjusted efficiency ratio near 49%. That shows genuine operating leverage while expenses stay anchored near the US$85m target.
Bear case on concentration and credit costs finds support
On the risk side, critics focus on whether growth and concentration in niche lending set Live Oak Bancshares up for bumpier credit outcomes.
"Heavy concentration in government guaranteed SBA and USDA lending remains a live issue, because any shift in program rules or guarantee structures could make these loans less attractive, reduce origination volumes and pressure gain on sale revenue, which would weigh on noninterest income and overall earnings for Live Oak Bancshares."
The quarter does not show program changes, yet it does show sensitivity to credit. Total provision reached US$55m, including US$17m for the exited distillery portfolio and US$29m tied to growth and commercial impairments. Provision guidance remains explicitly volatile, which reinforces concerns about earnings choppiness.
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for.
Hunt For Mispriced Earnings Power
Live Oak Bancshares just showed how reported profit and underlying momentum can diverge in important ways. The real opportunity is studying stocks that could be undervalued before the market adjusts their earnings power.
- Company 1 - 24% below our estimate - use a leading position in coconut-based drinks to expand branded and private label penetration in mainstream shelves.
- Company 2 - 33% below our estimate - turn a fast-growing super app into broader adoption of secured and higher yielding credit products across an engaged user base.
- Company 3 - 28% below our estimate - supply grid testing equipment and aerospace components as utilities and defense contractors upgrade systems to handle heavier electrification and power demand.
That is three of the list. See the full list of 30 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com