
1% Overvalued? Canadian Tire Corporation (TSX:CTC.A) As Aqara Rollout Reframes Value
Aqara’s Canadian retail debut through Canadian Tire Corporation (TSX:CTC.A), with smart home devices available in up to 500 stores as of 9 October 2026, gives investors a fresh angle on the retailer’s connected home ambitions.
Canadian Tire Corporation’s recent 1-month share price return of 10.68% and year to date share price return of 18.81% point to building momentum, supported by a 1-year total shareholder return of 24.30% and a 3-year total shareholder return of 73.02%.
Capitalize on Canadian Tire Corporation’s smart home push by comparing it with hand-picked retailers and tech-focused peers in our 10 high quality undiscovered gems.The recent jump in Canadian Tire Corporation shares leaves only a narrow gap to the CA$206.60 analyst target, while implying a far steeper discount to some intrinsic value estimates. Which reference point deserves more weight now?
Most Popular Narrative: 1% Overvalued
Canadian Tire Corporation’s most followed valuation story now pegs fair value at CA$206.60, sitting just below the CA$208.25 last close, which puts only a thin cushion between the narrative and the market price while still leaning on execution of its key projects.
Canadian Tire Corporation is pushing ahead with its True North shift to a more integrated retail system, with management targeting 3 to 5% annual revenue growth and faster earnings growth that would rely on shared data, tech and merchandising disciplines to support margins.
The wider rollout of AI pricing and customer analytics tools, such as the platforms used to shape promotions and category occasions, is expected to influence assortment, promo intensity and regular pricing in ways that support gross margin and earnings quality.
See why 43 investors see Canadian Tire Corporation as 1% overvalued.
Result: Fair Value of CA$206.60 (OVERVALUED)
Still, the data breach class action and any need for heavier CTFS spending on regulation or credit quality could quickly weaken the Canadian Tire Corporation fair value story.
Find out about the key risks to this Canadian Tire Corporation narrative.
Another View: Canadian Tire Corporation Through Earnings Multiples
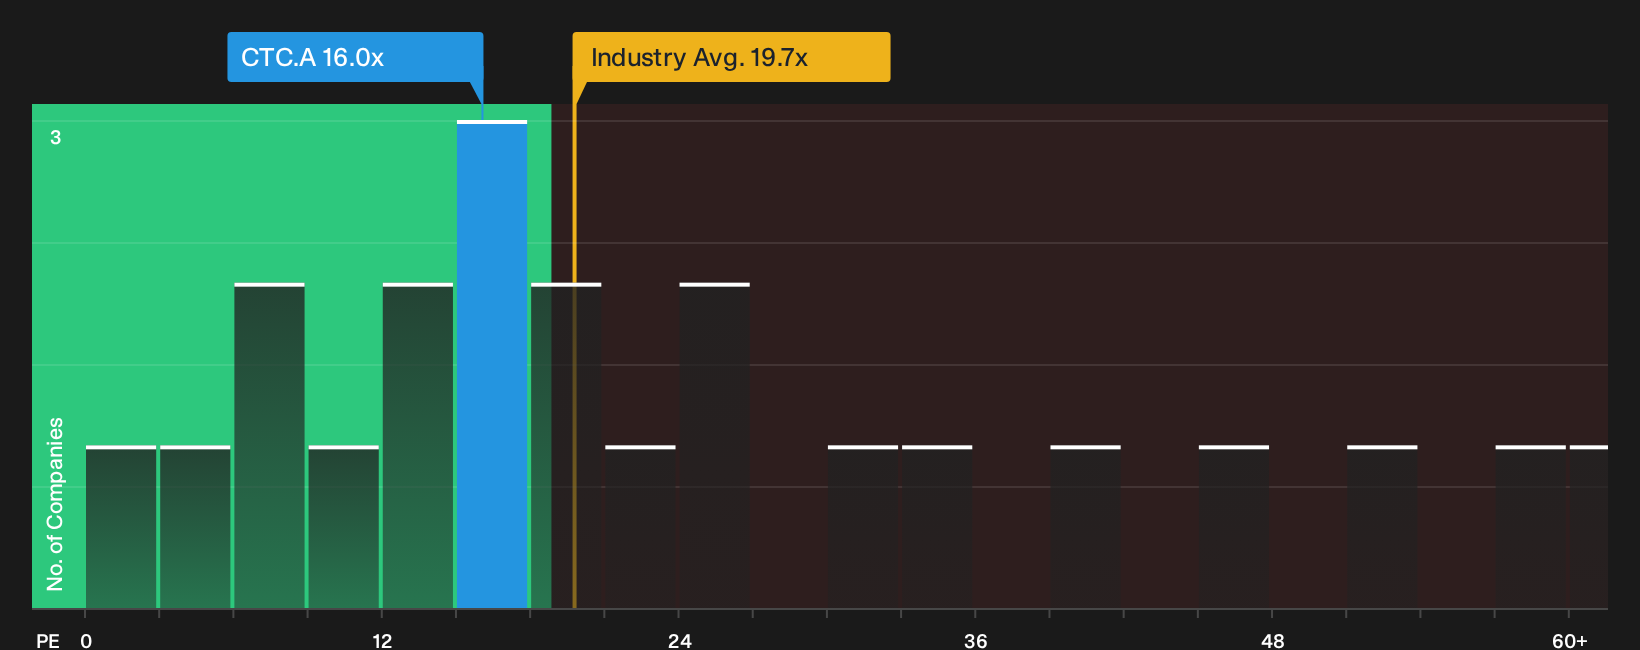
Analyst narratives lean on a fair value of CA$206.60 and label Canadian Tire Corporation as 1% overvalued, yet the current P/E of 16x tells a softer story. The Canadian market trades at 16.5x, global multiline retail at 19.7x, and the fair ratio model points to 19.4x.
That gap means the market is pricing Canadian Tire Corporation at a discount to both peers and the level the fair ratio suggests it could move toward, even as earnings growth forecasts are relatively modest. Is that a margin of safety or a signal that expectations are already capped?
For a closer look at how this earnings based view stacks up against other benchmarks and what it might mean for valuation risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Canadian Tire Corporation story today. Move quickly to test the upside against the weak spots and weigh the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Canadian Tire Corporation?
Canadian Tire Corporation gives you one angle on retail and consumer exposure, but your portfolio works harder when you line it up against other focused opportunities.
- Target fresh upside potential by scanning a curated 10 high quality undiscovered gems that surfaces under-the-radar companies with strong fundamentals before they hit the mainstream.
- Build a sturdier core by filtering for a list of solid balance sheet and fundamentals (7 results) so your capital leans toward businesses with cash flow support and less fragile finances.
- Sharpen your risk control by zeroing in on a 8 resilient stocks with low risk scores that highlights resilient stocks when you want ideas without taking on unnecessary volatility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com