
Zscaler (ZS) Joins NVIDIA OpenShell For AI Security, Is The Stock Fully Valued?
Zscaler (ZS) has been pulled into the center of the AI security conversation after integrating NVIDIA’s OpenShell Reference Architecture, with its AI security products generating over US$100 million in bookings and US$70 million in ARR.
Recent price action has been strong. Zscaler’s share price has climbed 7.84% in the last day and 65.59% over 90 days, while the 1-year total shareholder return declined 24.87%, signaling short-term momentum building after a tougher year for longer-term holders.
See how Zscaler compares with other companies securing the AI stack by reviewing our hand picked list of 55 AI infrastructure stocks.
Zscaler now looks like a high conviction way to play AI security, yet the stock has already sprinted on the OpenShell story. Is this still a sensible entry point or has enthusiasm run ahead of the price tag?
Most Popular Narrative: 7% Undervalued
Zscaler’s most followed narrative pegs fair value at $249.97, above the recent $231.33 close. This points to modest undervaluation and places extra weight on how the AI story develops from here.
The market still largely values Zscaler as a Zero Trust security company. I believe the more important question is whether it becomes a foundational platform for securing enterprise AI.
Fiscal 2026 results showed accelerating ARR growth, record large-customer activity, growing adoption of non-seat-based products, and early evidence that Security for AI is resonating with customers. Security for AI bookings grew more than 50% quarter-over-quarter, while 70% of those wins included Data Security products, suggesting meaningful platform expansion opportunities.
See why 31 investors see Zscaler as 7% undervalued.
Result: Fair Value of $249.97 (UNDERVALUED)
Still, the thesis around Zscaler and AI security could weaken if AI specific demand slows, or if larger platforms bundle competing security tools more aggressively.
Find out about the key risks to this Zscaler narrative.
Another View: Zscaler Looks Pricey On Sales
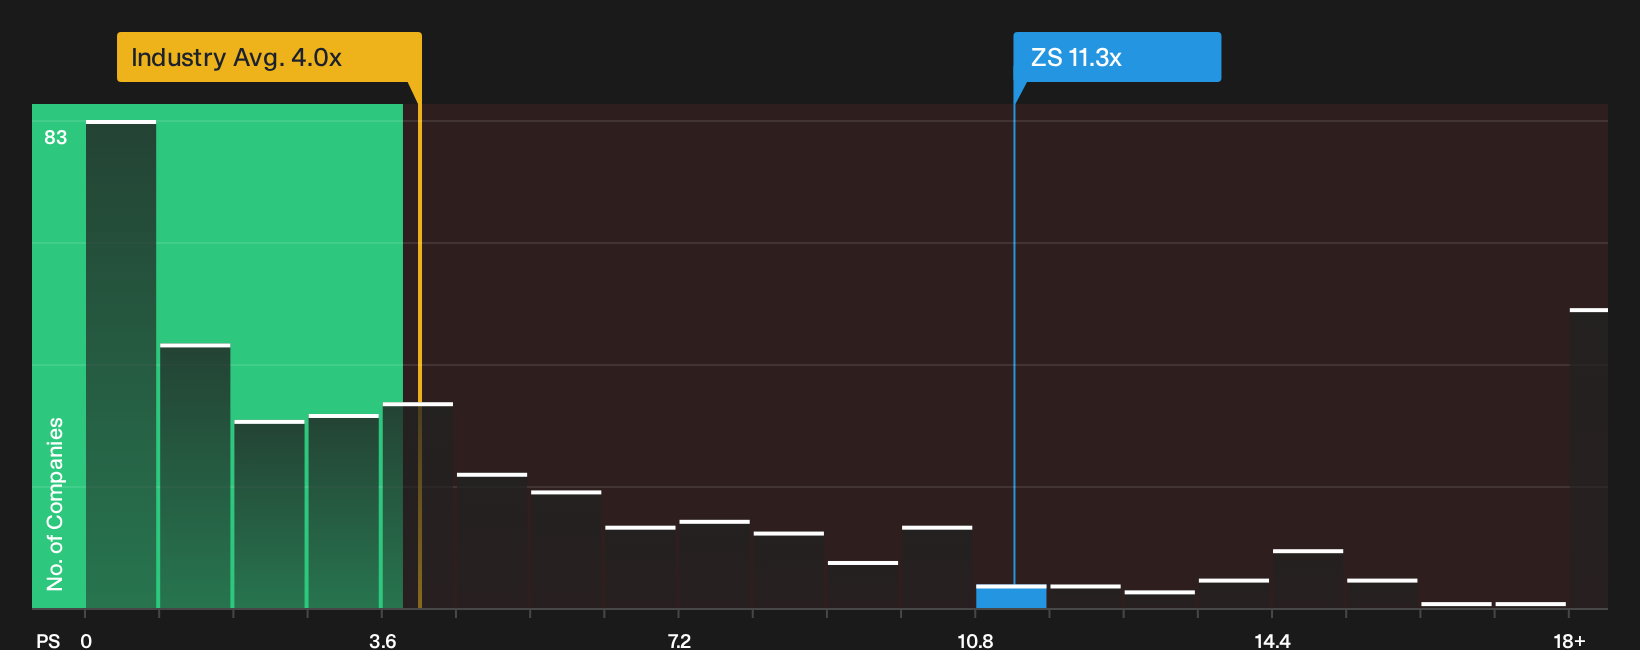
The fair value from the community narrative marks Zscaler as around 7% undervalued at $249.97. On a pure sales multiple, the picture is less generous. The P/S sits at 11.3x, above a fair ratio of 9.3x and far ahead of the US Software average of 4x and peer average of 11.7x.
That gap on revenue multiples points to a richer valuation that leans heavily on execution and AI traction. It raises a simple question for investors: Is this a margin of safety story or a quality premium that needs flawless delivery over the next few years?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Zscaler is split, and that is exactly when fresh eyes matter most. Move quickly, review the underlying data yourself, and weigh both sides through the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Zscaler?
Do not stop with one compelling ticker. Broaden your watchlist using focused stock ideas that match how you like to balance opportunity and risk.
- Target future upside with a curated set of quality businesses that still trade below many investors’ expectations by reviewing the 30 high quality undervalued stocks.
- Strengthen portfolio resilience by concentrating on companies with cleaner finances and sturdier balance sheets through the list of solid balance sheet and fundamentals (25 results).
- Hunt for underfollowed opportunities where the crowd has not yet fully caught on by scanning the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com