
What Banco de Sabadell Holders Bought Into
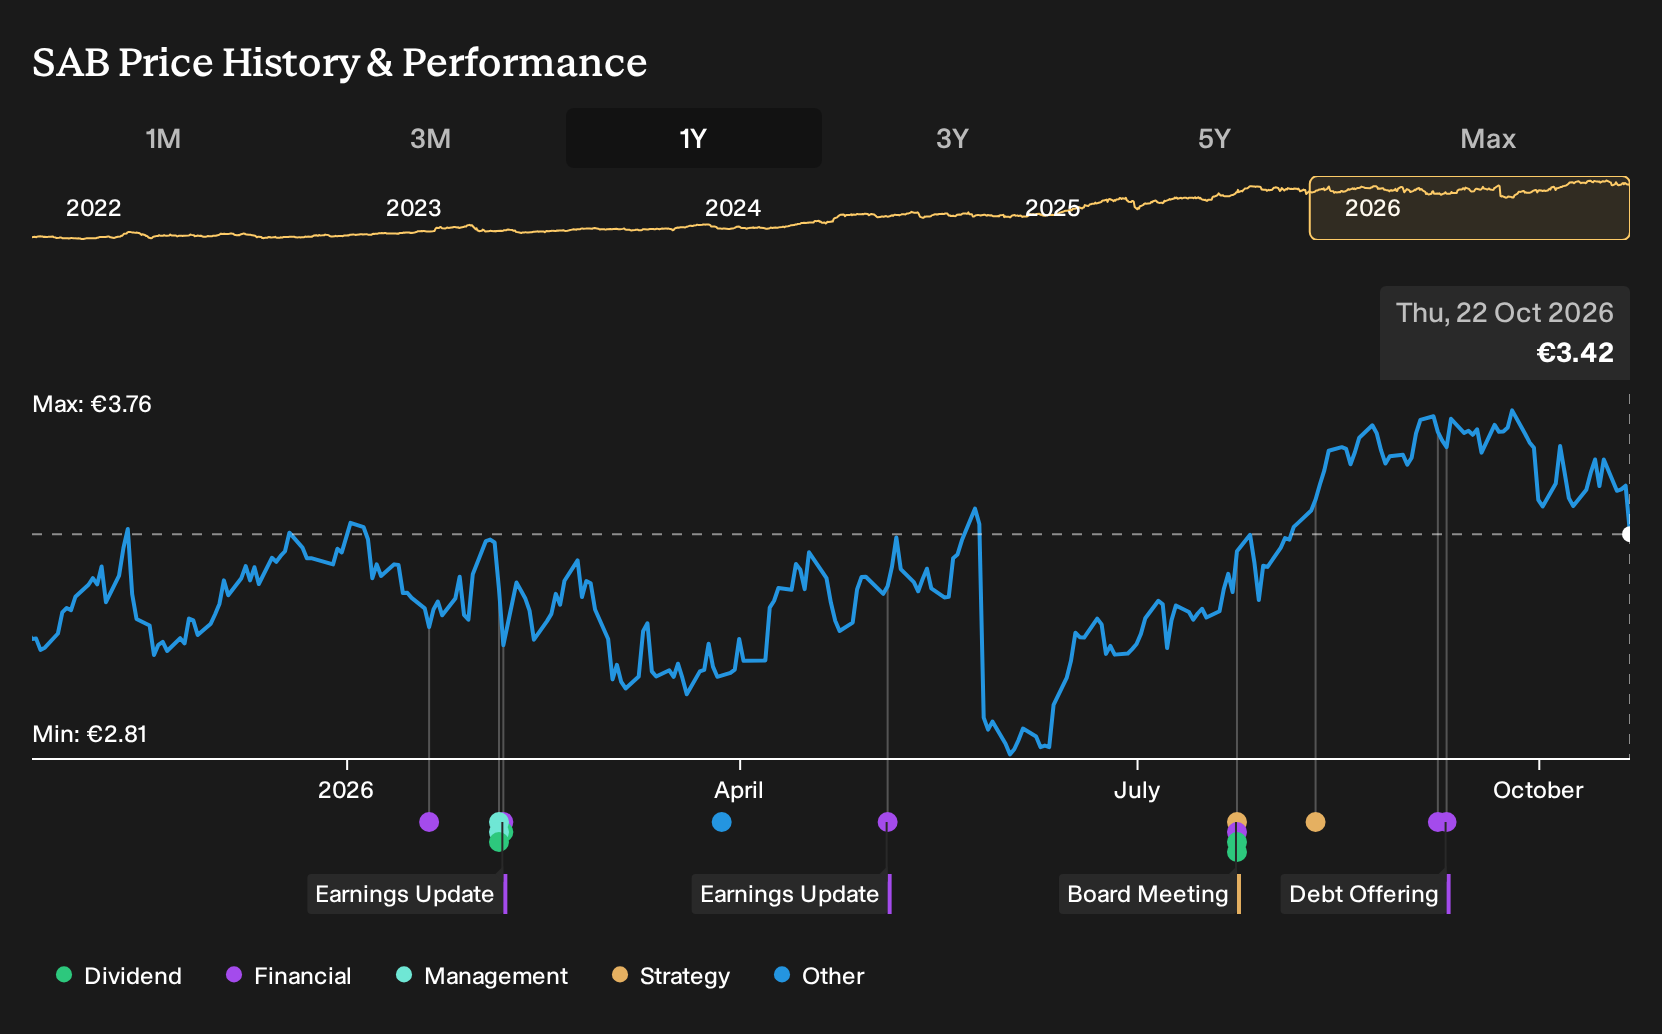
If you only glanced at the early 2025 debate around Banco de Sabadell, you saw analysts arguing over falling future revenues on one side and digital transformation upside on the other. For Banco de Sabadell shareholders, the return over the past year was 27.1%, including dividends. If you had been weighing those opposing fair values at the outset, what exactly in the record would have justified taking that risk?
The easy part of this move is behind Banco de Sabadell. Zero in on 192 high quality undervalued stocks for companies trading below our estimates.
The Two Stories Banco de Sabadell Investors Had To Choose Between
The shares cost €3.13 at the start of the period, and anyone looking at Banco de Sabadell then had to decide which future felt more plausible.
The bullish narrative pointed to a Fair Value of €4, a notional price based on its own assumptions, built on faith in digitalization and urbanization. Supporters leaned on rapid reductions in non performing assets and the idea that deepening digital services could lift fee income while keeping the cost base tight.
The bearish view anchored on a Fair Value of €2.3 and focused on structural risks. Critics worried that legacy IT, aging demographics in Spain and Europe, and heavier regulation could leave Sabadell with slower loan demand, weaker revenues, and a stubbornly high cost to income ratio.
What The Evidence Around Banco de Sabadell Actually Tested
The TSB sale, extra dividends and new €331 million buyback gave hard backing to the bullish Banco de Sabadell case that assumed strong capital generation and active shareholder payouts. BPCE buying about 7% and seeking a board seat added a long term partner. Participation in the Qivalis euro stablecoin project and an AI focused restructure supported the digital transition story. Overall, the evidence leaned toward the optimistic camp.
The lesson is simple. When a thesis hinges on capital strength and digital execution, do not stop at earnings forecasts. Track actual buybacks and special distributions, plus concrete moves such as IT restructures or payment projects, to see whether management is acting on those claims.
What Banco de Sabadell’s Price Already Builds In
Banco de Sabadell now trades at €3.42. The selected Narrative’s Fair Value estimate sits below that level and treats the current tag as rich for a bank still working through digital overhauls, domestic concentration, and tougher regulation.
That view leans on the idea that recent gains already assume durable earnings progress. A buyer today is effectively betting that digital investments translate into lasting growth and efficiency, so the key question is how the highlighted disruption and cost pressures might challenge that path.
"Rapid digital disruption, regulatory pressures, and legacy inefficiencies threaten Sabadell's market share, margin levels, and ability to effectively compete with technology-driven entrants. Domestic market concentration and demographic headwinds limit growth potential, exposing Sabadell to increased earnings volatility and operational risks."
The price and this Narrative do not agree. → Uncover what this Narrative says Banco de Sabadell is actually worth
Before The Next Story Makes Headlines
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 30% below our estimate - sells full-stack accelerated computing platforms that power large-scale AI infrastructure buildouts.
- Company 2 - 35% below our estimate - converts subsea opportunity lists into bundled iEPCI orders and recurring services agreements.
- Company 3 - 32% below our estimate - expands multichannel electronics retail by scaling online capability and newer store formats.
Those are three of them. See the full list of 203 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com