
We're Not Very Worried About World Houseware (Holdings)'s (HKG:713) Cash Burn Rate
Just because a business does not make any money, does not mean that the stock will go down. For example, although Amazon.com made losses for many years after listing, if you had bought and held the shares since 1999, you would have made a fortune. But the harsh reality is that very many loss making companies burn through all their cash and go bankrupt.
Given this risk, we thought we'd take a look at whether World Houseware (Holdings) (HKG:713) shareholders should be worried about its cash burn. In this report, we will consider the company's annual negative free cash flow, henceforth referring to it as the 'cash burn'. First, we'll determine its cash runway by comparing its cash burn with its cash reserves.
How Long Is World Houseware (Holdings)'s Cash Runway?
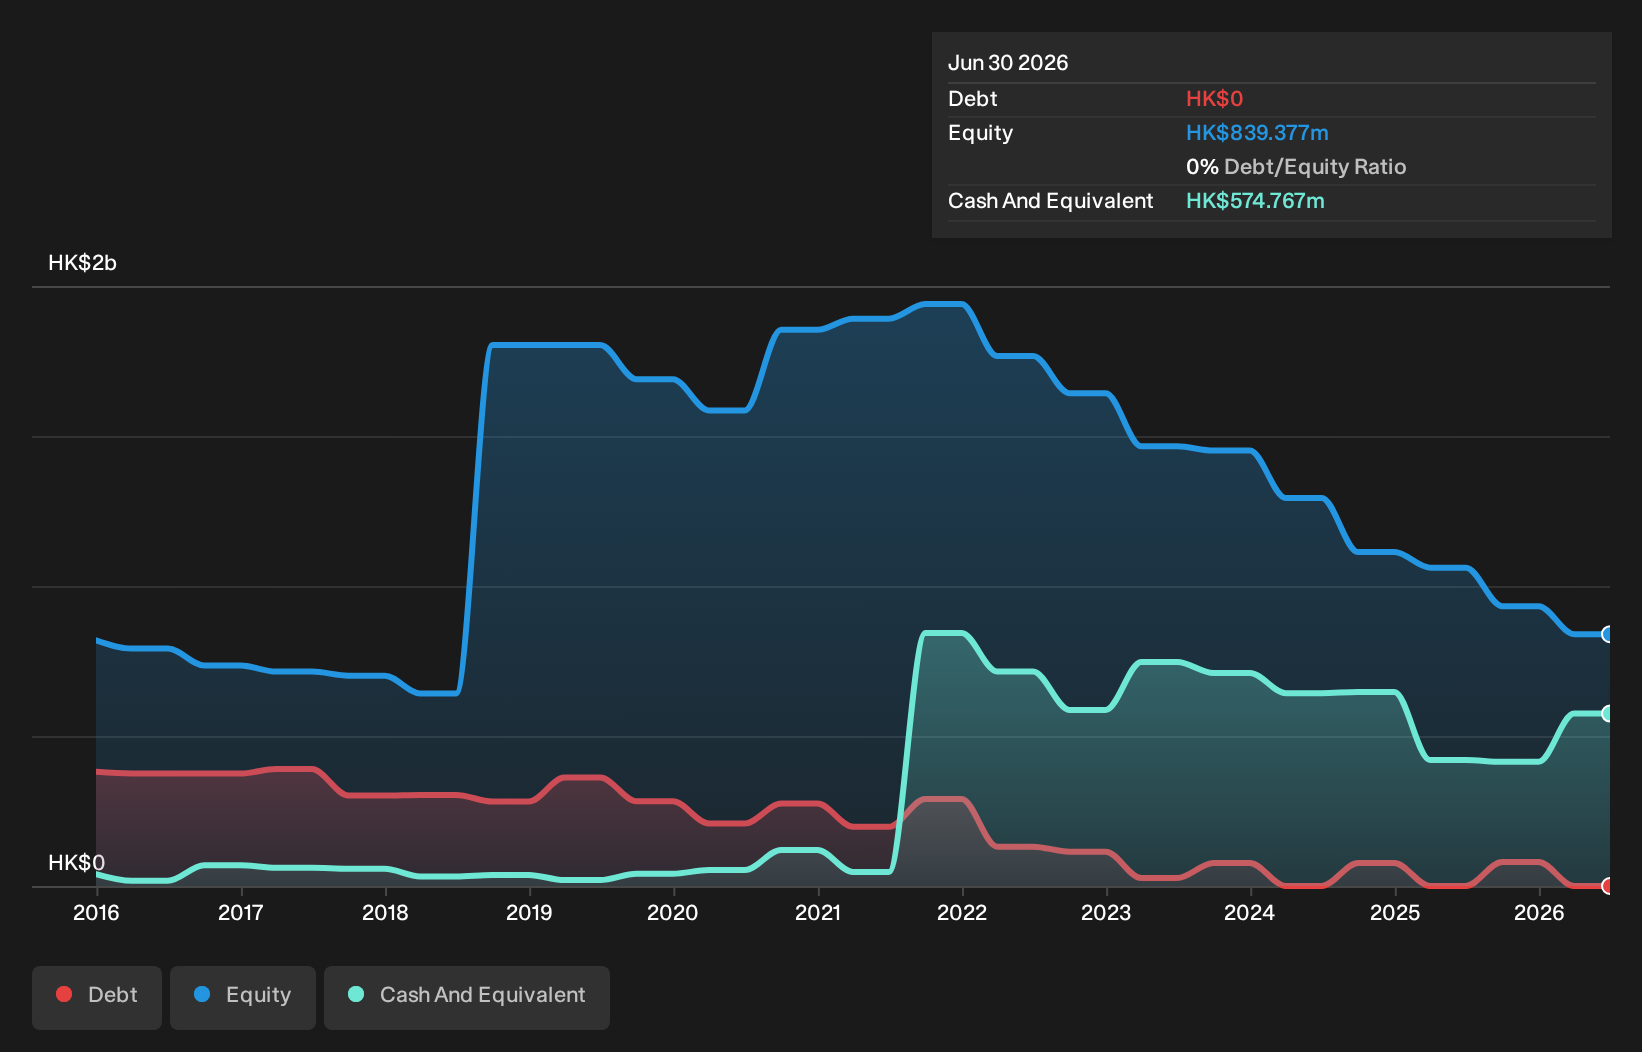
A cash runway is defined as the length of time it would take a company to run out of money if it kept spending at its current rate of cash burn. As at June 2026, World Houseware (Holdings) had cash of HK$575m and no debt. In the last year, its cash burn was HK$33m. So it had a very long cash runway of many years from June 2026. While this is only one measure of its cash burn situation, it certainly gives us the impression that holders have nothing to worry about. You can see how its cash balance has changed over time in the image below.
Check out our latest analysis for World Houseware (Holdings)
How Well Is World Houseware (Holdings) Growing?
Some investors might find it troubling that World Houseware (Holdings) is actually increasing its cash burn, which is up 12% in the last year. Also concerning, operating revenue was actually down by 7.8% in that time. Considering both these factors, we're not particularly excited by its growth profile. In reality, this article only makes a short study of the company's growth data. This graph of historic earnings and revenue shows how World Houseware (Holdings) is building its business over time.
How Easily Can World Houseware (Holdings) Raise Cash?
World Houseware (Holdings) seems to be in a fairly good position, in terms of cash burn, but we still think it's worthwhile considering how easily it could raise more money if it wanted to. Issuing new shares, or taking on debt, are the most common ways for a listed company to raise more money for its business. Many companies end up issuing new shares to fund future growth. We can compare a company's cash burn to its market capitalisation to get a sense for how many new shares a company would have to issue to fund one year's operations.
World Houseware (Holdings)'s cash burn of HK$33m is about 17% of its HK$202m market capitalisation. As a result, we'd venture that the company could raise more cash for growth without much trouble, albeit at the cost of some dilution.
Is World Houseware (Holdings)'s Cash Burn A Worry?
On this analysis of World Houseware (Holdings)'s cash burn, we think its cash runway was reassuring, while its falling revenue has us a bit worried. Cash burning companies are always on the riskier side of things, but after considering all of the factors discussed in this short piece, we're not too worried about its rate of cash burn. Separately, we looked at different risks affecting the company and spotted 2 warning signs for World Houseware (Holdings) (of which 1 can't be ignored!) you should know about.
Of course World Houseware (Holdings) may not be the best stock to buy. So you may wish to see this free collection of companies boasting high return on equity, or this list of stocks with high insider ownership.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.