
Badger Meter (BMI) Climbed, But What Is Driving Attention Now?
Badger Meter (BMI) just released third quarter numbers, reporting essentially flat sales, a small increase in earnings, a higher dividend for the 34th consecutive year, and ongoing share repurchases that are drawing fresh investor attention.
Recent trading tells a mixed story for Badger Meter. The stock has risen 7.03% over the past 90 days, but the year-to-date share price return is down 25.25%, while the 1-year total shareholder return has declined 26.95%. This suggests that near term enthusiasm has not yet reversed the longer term pullback.
Capitalize on the renewed focus on Badger Meter's earnings, dividend growth, and buybacks by scanning a curated set of 33 high quality undervalued stocks with resilient balance sheets and disciplined capital allocation.Badger Meter just bounced on an earnings beat while still trading below both analyst targets and some intrinsic value estimates. The gap between its price and those ranges now matters more than the headline move.
Most Popular Narrative: 16% Undervalued
Badger Meter last closed at $131.86, while the most followed narrative anchors fair value closer to $156.67. This puts today’s bounce into context and shifts attention to how future project execution supports that gap.
Balanced capital allocation, including roughly US$400 million deployed on acquisitions over five years, continued R&D focused on ultrasonic metering and cellular AMI, a renewed US$150 million undrawn credit facility and an active share repurchase program with about US$90 million remaining, gives Badger Meter financial flexibility to continue compounding revenue and to protect EBITDA margin and cash conversion even through periods of uneven project pacing.
See why 13 investors see Badger Meter as 16% undervalued.
Result: Fair Value of $156.67 (UNDERVALUED)
Still, Badger Meter’s story can change quickly if large AMI and sewer awards ramp more slowly than expected or if legal and governance issues escalate costs.
Find out about the key risks to this Badger Meter narrative.
Another View: What Badger Meter’s P/E Is Telling You
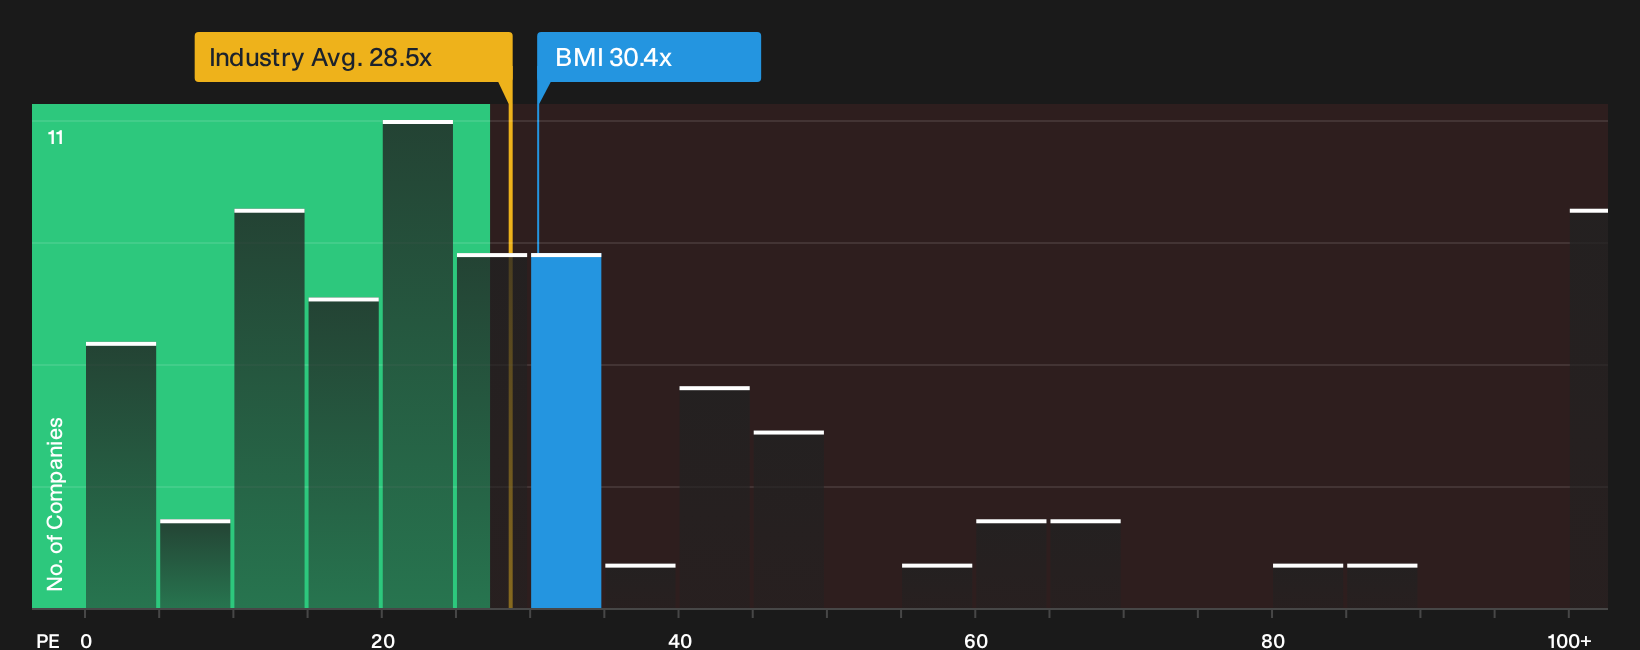
There is a catch. While Badger Meter screens as about 4.4% below the SWS fair value estimate and trades under some intrinsic value ranges, the stock changes hands at a P/E of 30.4x. That is higher than the estimated fair ratio of 23.6x and above the US Electronic industry average of 28.6x.
For you as an investor, that gap means the market is already paying a premium for Badger Meter’s earnings compared with both the sector and what the fair ratio suggests the multiple could move toward over time. The question is whether the execution on AMI awards, software attachment and legal outcomes justifies living with that valuation risk.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Curious whether the cautious tone here matches your own read on Badger Meter. Move quickly to review the underlying data and weigh the 2 key rewards.
Looking for more investment ideas beyond Badger Meter?
If Badger Meter has you reassessing your watchlist, this is the moment to widen the lens and look for fresh opportunities before others spot them.
- Target strong balance sheets and steady fundamentals by scanning a curated list of solid balance sheet and fundamentals (25 results) that can handle pressure when conditions turn.
- Identify potential mispricings early by reviewing a focused 33 high quality undervalued stocks where quality and price work together more efficiently for your capital.
- Evaluate consistent cash flow potential by assessing a handpicked 7 dividend fortresses built around higher-yield payouts and durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com