
Tower Semiconductor (TSEM) Secures Semtech Capacity, Is The AI Upside Already Priced In?
Semtech capacity deal puts Tower Semiconductor in focus
Tower Semiconductor (TSEM) moved into the spotlight after Semtech announced an expanded multi-year agreement that secures dedicated silicon germanium capacity for AI data center optical interconnect components across Tower’s global fabs.
Despite a sharp year-to-date share price return of 55.7% and a very large 3-year total shareholder return of about 7x, Tower Semiconductor has recently given back some ground, with the share price down 18.9% over 30 days and 27.2% over 90 days. The Semtech capacity deal lands just as momentum cools in the short term. This can hint that investors are reassessing both growth potential in AI data center exposure and the risks implied by such a strong 160.6% total shareholder return over the past year at a latest share price of US$189.55.
Scan handpicked peers riding similar AI infrastructure demand with the 55 AI infrastructure stocks to see how Tower Semiconductor stacks up in this part of the market.
Bulls point to Tower Semiconductor’s AI data center exposure and fresh Semtech capacity, while bears highlight a sharp run-up and recent pullback. Which side do the current valuation markers lean toward?
Most Popular Narrative: 39% Undervalued
On the most followed narrative, Tower Semiconductor’s fair value sits at $312.93, well above the last close of $189.55. This puts the new Semtech capacity deal into a pricing framework that already leans heavily on AI related growth and margin assumptions.
The roughly US$920m silicon photonics and SiGe capacity program across existing 200mm and 300mm fabs, together with the larger dual track 300mm build out in Japan that targets more than 5x silicon photonics capacity and roughly 4x Japanese 300mm output, gives Tower Semiconductor substantial headroom to translate customer demand into higher long term revenue.
See why 32 investors see Tower Semiconductor as 39% undervalued.
Result: Fair Value of $312.93 (UNDERVALUED)
Still, the Tower Semiconductor story can crack if the multi year Japan build and silicon photonics expansion outstrip wafer demand, or if high P/E expectations reset sharply.
Find out about the key risks to this Tower Semiconductor narrative.
Another View: Tower Semiconductor Through The Earnings Lens
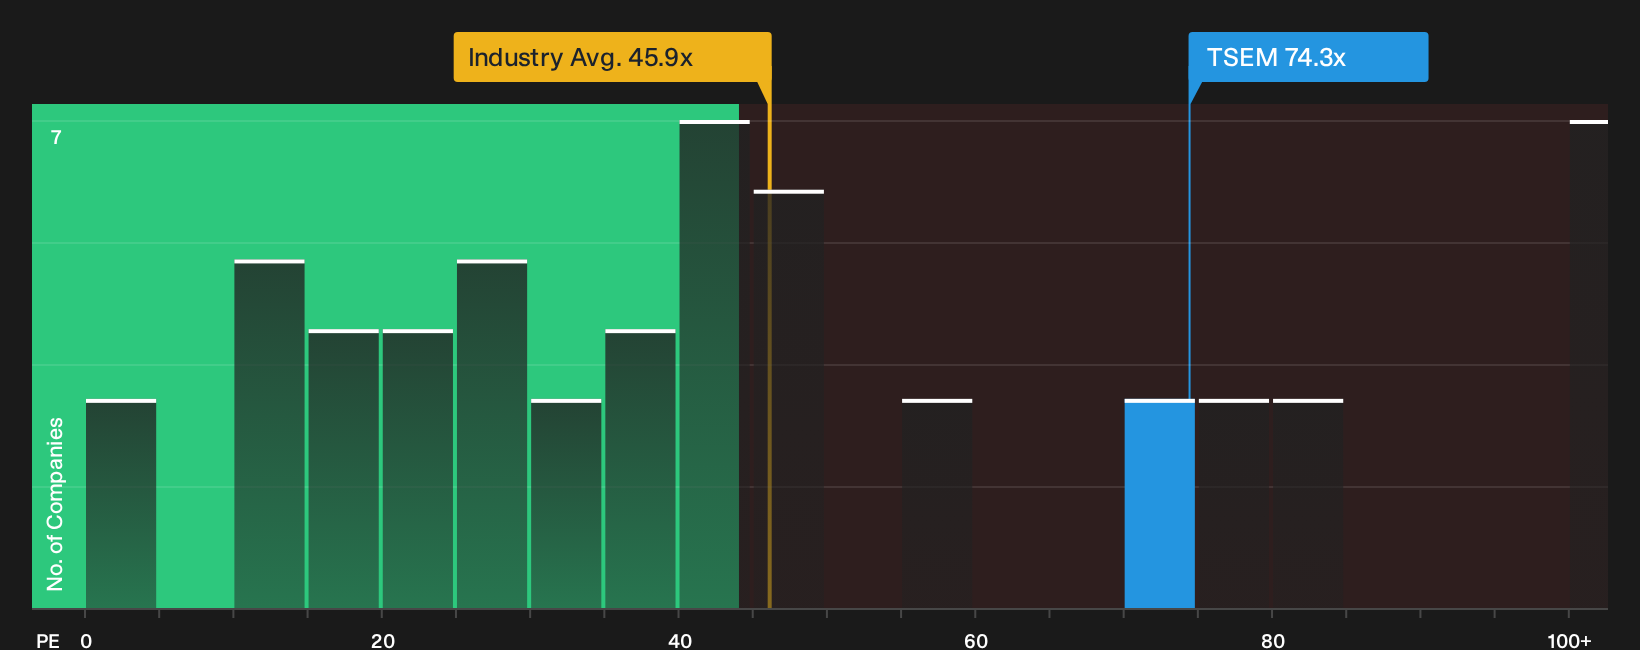
The analyst narrative leans on a fair value of $312.93, yet the current P/E of 74.3x tells a tougher story. That valuation is well above the US Semiconductor industry at 45.9x, peers at 45.4x, and even a fair ratio of 52.7x, which signals meaningful multiple risk if sentiment cools.
For a closer look at what this pricing gap could mean for Tower Semiconductor if the market drifts back toward that fair ratio, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages on Tower Semiconductor’s valuation story can make it tempting to follow the crowd, but the better move is to pressure test the numbers yourself, weigh both the concerns and the upside, and then frame your own stance with the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Tower Semiconductor?
If Tower Semiconductor has sharpened your thinking, do not stop here. Broader context across other opportunities can help you stress test your next move.
- Target stronger value by lining up Tower against a broader pool of quality opportunities through the 33 high quality undervalued stocks.
- Protect the downside first by filtering for companies with sturdier finances using the list of solid balance sheet and fundamentals (25 results).
- Hunt for underfollowed potential by scanning the 21 high quality undiscovered gems before others catch on.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com