
What Becton Dickinson Doubters Overlooked
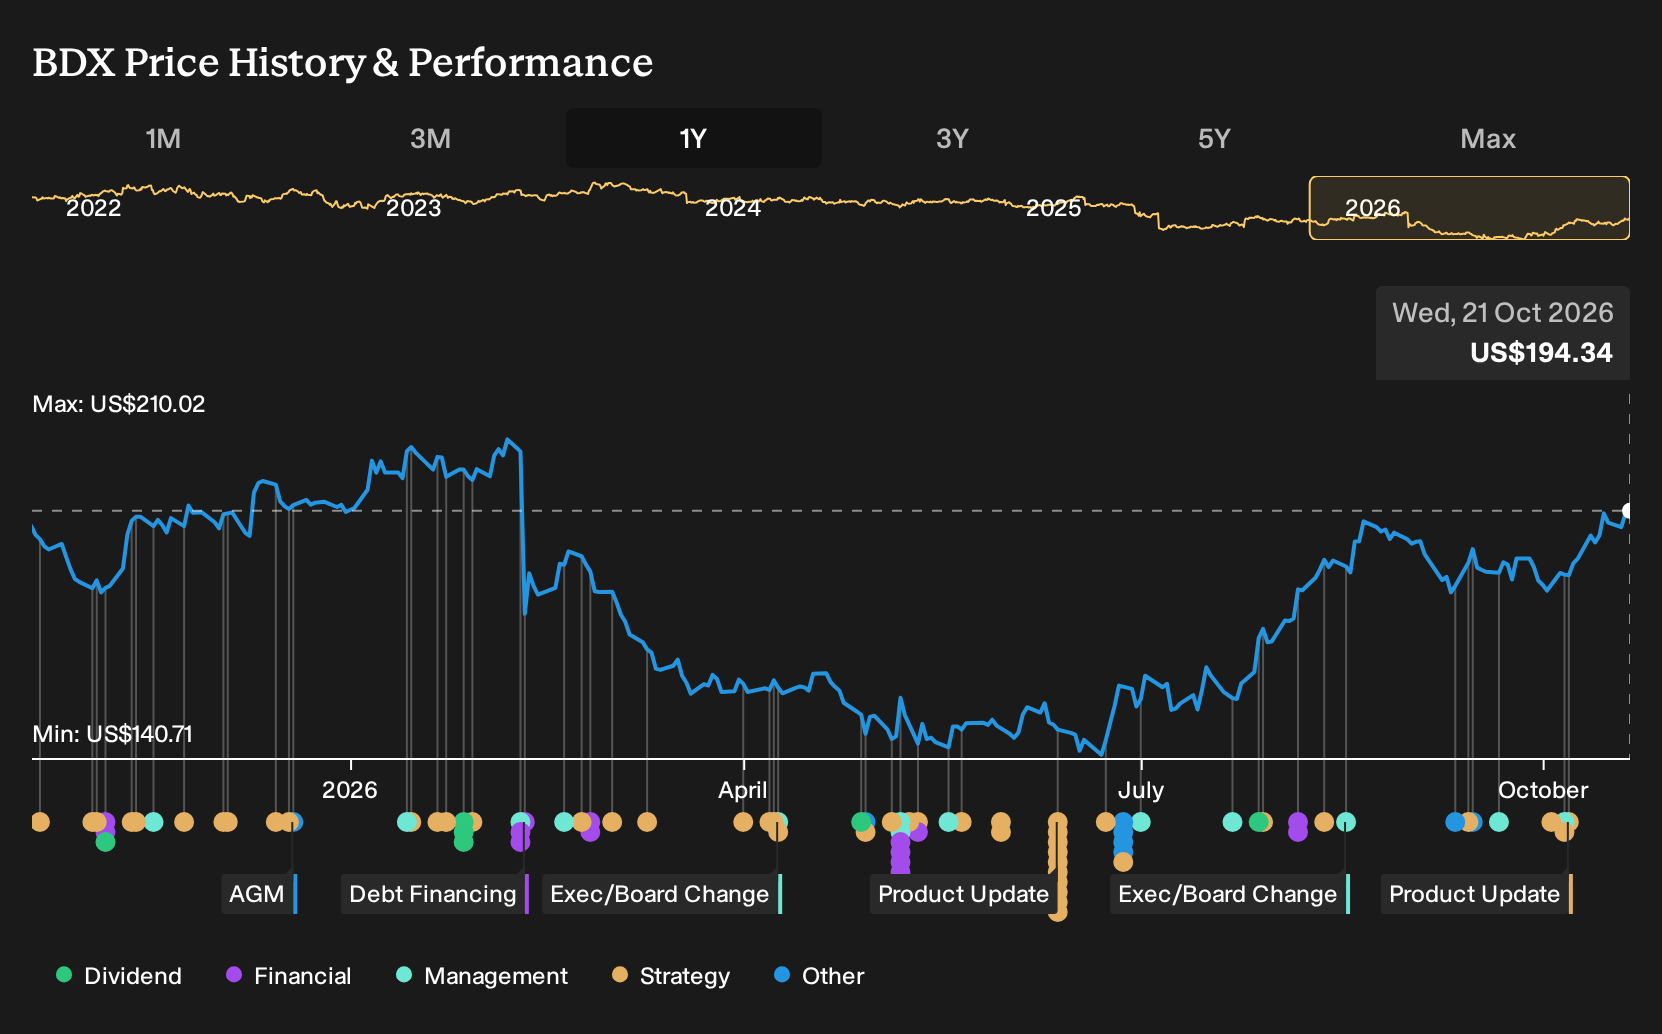
Becton Dickinson closed a high profile US manufacturing agreement that tied billions of dollars of planned investment to producing syringes, needles and other consumables on American soil, with protection from certain future tariffs built in. For Becton Dickinson shareholders, the return over the past year was 34.8%, including dividends. If you were weighing a purchase on 21 October 2025, what exactly would you have needed to believe about this kind of deal-driven future for the business?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
Becton Dickinson has already moved. Pinpoint other ways to investigate the theme among 37 healthcare AI stocks.
The Two Stories Investors Were Really Choosing Between On Becton Dickinson
The shares cost US$189 at the start of the period, and Becton Dickinson sat between two very different but plausible stories about where the next few years might lead.
The bullish Narrative put Fair Value at US$209, 11% above the start price. It leaned on advanced diagnostics and tissue regeneration, as well as the planned separation into a consumables heavy pure play medtech group.
The bearish case pinned Fair Value at US$172, 9% below. It focused on pressure from cheaper rivals, regulatory friction, and the risk that cuts to global research funding would drag on Life Sciences margins.
What The Evidence Did To The Becton Dickinson Story
Becton Dickinson’s decision to commit up to US$19b with the U.S. government for domestic manufacturing backed the bullish view that contract heavy consumables and tariff protection could underpin the medtech spin. Revenue reached US$4,983m in Q3 2026 compared with US$4,726m a year earlier, while net income stayed at US$451m and net margin slipped from 9.5% to 9.1%. In other words, the evidence cut both ways.
The key assumption was that higher capital and separation spending would still translate into healthier margins. When you test a similar claim elsewhere, watch whether net income and net margin move with headline revenue once large investment programs kick in.
What Becton Dickinson’s Price Already Bakes In
Becton Dickinson is now at US$194, modestly above where it started one year ago, and this selected Narrative’s Fair Value sits below that level based on its own assumptions.
The argument leans on productivity programs and focused medtech platforms. A buyer today is effectively betting that sustained margin strength and free cash flow outweigh the execution and regulatory risks flagged in the Narrative.
"The main factor that has to go right is that Becton Dickinson continues to turn its focused medtech platforms and BD Excellence productivity into sustained margin strength and healthy free cash flow that can support ongoing shareholder returns despite Alaris, China and vaccine headwinds. The combined figures on growth, margins, cash generation and capital returns, together with this narrative's view that Becton Dickinson is fairly valued, indicate a share price that already reflects successful execution on the higher growth, higher margin portfolio and operating model."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
Another Way To Play Healthcare Scale
Becton Dickinson focuses on equipment and consumables. Your portfolio does not have to stop there.
Hospitals and clinics still need someone to coordinate care, handle claims, and refine pricing. That operational work shapes what they can actually pay for devices.
One large health services group is expanding value based programs and pharmacy benefits. It is also investing in software and AI to trim back office costs.
If those efforts change how care is delivered and reimbursed, the effects reach device ordering and long term demand planning.
One Narrative has already put a figure on it. → Uncover the company trading 13% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com