
DoorDash (DASH) Stock Looks Expensive Despite Its 155% 3 Year Run
DoorDash has had a mixed share price journey, with a very strong 3 year return sitting alongside weaker recent months, which puts fresh focus on whether its current valuation lines up with the earnings behind the story. With the stock now trading at US$184.45, the question is how much of its future profitability the market is already baking into that price.
- Over the past 3 years, DoorDash has delivered a return of 155.2%, which raises the stakes on whether its earnings can support that kind of long term rerating.
- Recent news, from FAA approval for its in house drone delivery program to expanded restaurant loyalty tools, may support expectations for future revenue, margins and capital spending that feed directly into the earnings power investors are paying for.
- The analysts covering DoorDash have run their own numbers. See what analysts think DoorDash's shares could be worth.
For investors, the debate is whether DoorDash's current share price is justified by the earnings it produces today and what those earnings may reasonably become over time.
If you want to test the same earnings question you are asking of DoorDash across a wider set of companies, take a look at 33 high quality undervalued stocks.
Is DoorDash Getting Expensive on Earnings?
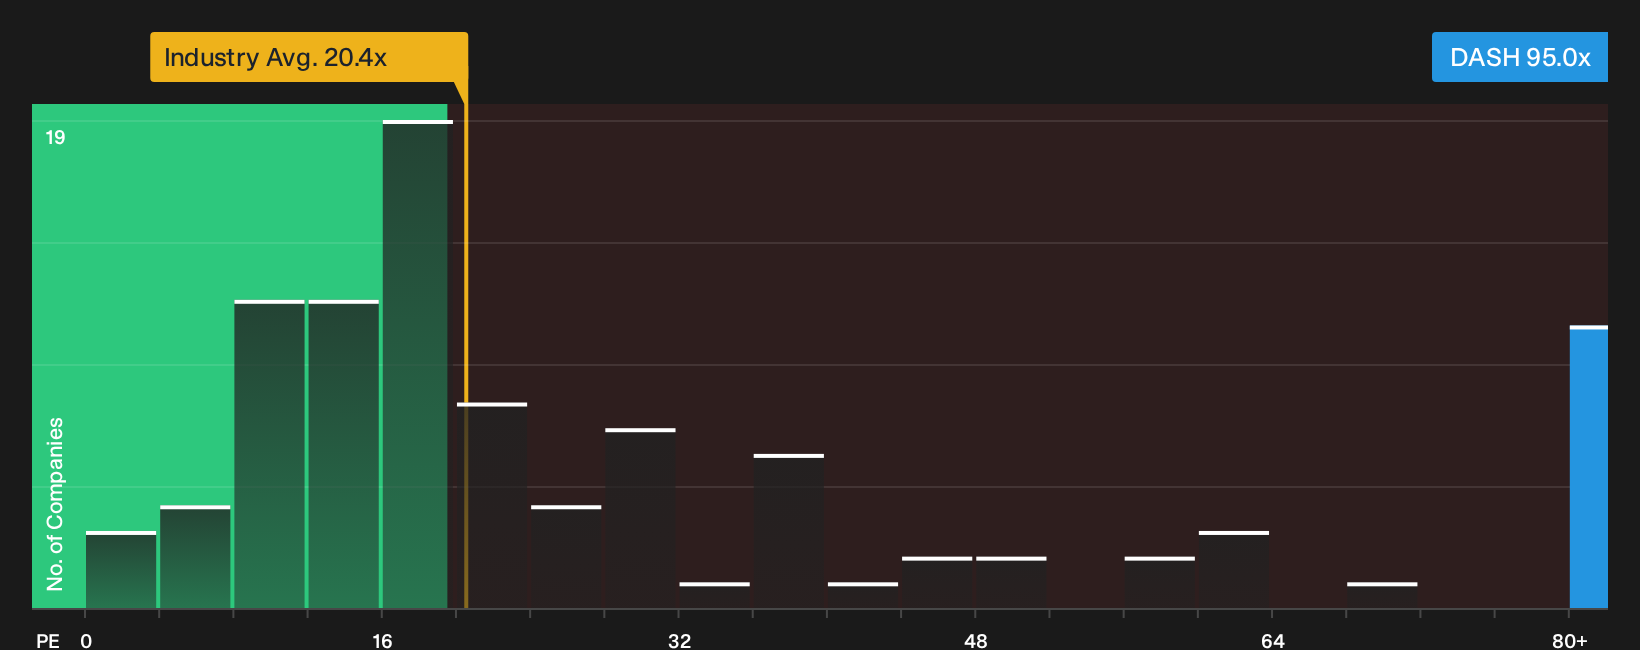
The P/E ratio is a clean way to see how heavily DoorDash stock is pricing each dollar of current earnings. Right now the shares trade on about 95.0x earnings, which is more than triple the Hospitality industry average of roughly 20.4x and also well above the peer group at about 29.8x.
On this framework, the tailored fair multiple that factors in DoorDash's risk, growth profile and business model points to a lower P/E than where the stock trades today, so the current level looks overvalued on earnings. Because the newly announced DoorDash Air drone program and expanded loyalty tools can lift excitement around the story long before they feed through into the income statement, you should be clear how much extra you are paying for those prospects before relying on this P/E to justify the share price. Explore the numbers behind DoorDash's P/E valuation.
The DoorDash Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the DoorDash valuation puzzle leaves off. They explain which expectations for growth, margins and future earnings would need to hold for the stock to be worth meaningfully more or less than today’s price. Each Narrative treats fair value as a thesis about the business that you can track over time, rather than as a single frozen snapshot. These Narratives are available on DoorDash's Community page for investors to explore.
One of the top community narratives on DoorDash: roughly fairly valued
"Bearish analysts expect higher regulatory, compliance, and Dasher support costs to keep pressuring DoorDash's margins even as the core delivery business scales."
Discover why this Narrative puts DoorDash at roughly fairly valued.
One more piece of the DoorDash story is easy to overlook
Valuation only tells part of the picture for DoorDash, because recent checks also pick up specific business risks that could alter how you view the whole opportunity. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com