
South32 (ASX:S32) Upper Kobuk Progress Puts Fair Value Back In Focus
Fresh attention on South32 (ASX:S32) has been sparked by progress at the Upper Kobuk Mineral Projects, where joint venture Ambler Metals completed its 2026 summer field program and appointed a senior executive to steer the Arctic Project.
South32’s recent interest around Upper Kobuk comes against a mixed price backdrop, with the shares at A$4.36 after a 1-month share price return that fell 10.66%, a year-to-date share price gain of 22.82%, and a 1-year total shareholder return of 40.92%, which hints that longer term momentum has still been positive.
Scan other miners with similar momentum and project catalysts by checking the 16 top copper producer stocks along with South32’s Upper Kobuk exposure.
South32 trades at A$4.36 while analyst targets and one intrinsic estimate sit higher, which leaves a clear gap. The real task now is working out where fair value in that range appears most sensible.
Most Popular Narrative: 5% Overvalued
South32 is trading at A$4.36 while the leading narrative fair value sits at A$4.17, which suggests the share price is slightly ahead of that assessment and puts more weight on execution at assets like Upper Kobuk and Hermosa.
At A$4.167 per share, South32 (ASX: S32) appears reasonably valued based on its current operating performance. South32 reports in US dollars and recorded first-half FY26 underlying earnings of US$435 million, or approximately US 9.7 cents per share. Annualising this result and using an exchange rate of US$0.70 per Australian dollar gives earnings of approximately A$0.277 per share and a P/E ratio of around 15 times.
Underlying EBITDA increased by 9% to US$1.1 billion, while underlying earnings increased by 16%. The interim dividend of US 3.9 cents per share, together with the previous US 2.6-cent dividend, represents a trailing fully franked yield of approximately 2.2% at the assessed price.
See why 4 investors see South32 as 5% overvalued.
According to Jamesiskindacool, that A$4.17 figure leans heavily on existing operations and only partially reflects the proposed aluminium sale to Alcoa, development at Hermosa, and potential copper and zinc expansion. Those moving parts tie back to the narrative discount rate of 8.66%, which builds in a material return hurdle before any re rating case stacks up.
Result: Fair Value of A$4.17 (OVERVALUED)
Still, any delay or change to the proposed aluminium sale, or cost and timing setbacks at Hermosa, could quickly challenge that South32 fair value story.
Find out about the key risks to this South32 narrative.
Another View: What The Ratios Say About South32
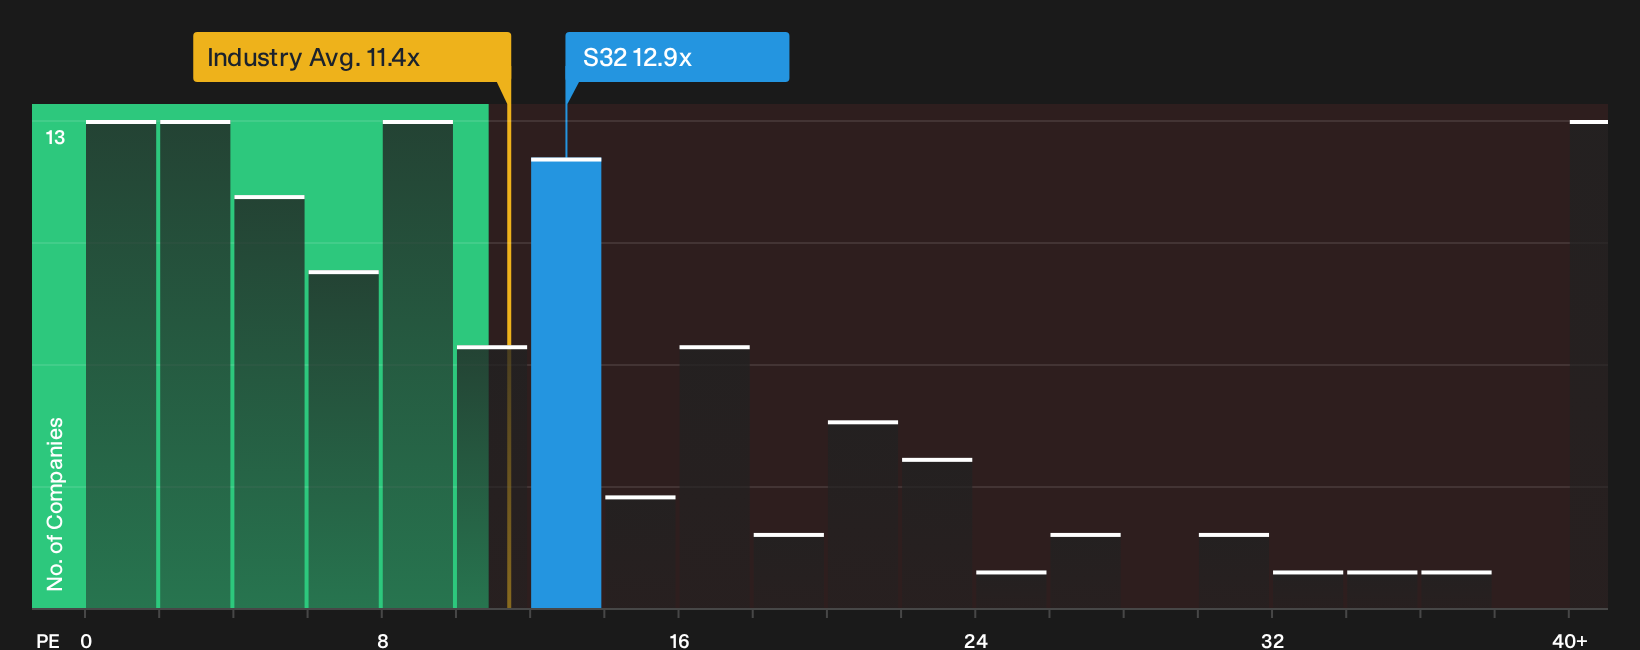
There is a twist once ratios are brought in. South32 trades on a P/E of 12.9x, which is lower than its fair ratio of 15.4x and well under the 24.7x peer average, yet slightly above the 11.4x Australian metals and mining group. That mix hints at both a cushion and some sector risk. Which side matters more to you?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on South32 so far. If that blend of risk and upside has you curious, spend a few minutes with the numbers and weigh the 3 key rewards and 2 important warning signs.
Looking for more South32-sized investment ideas?
If South32 has sharpened your thinking, do not stop here. A few focused screens can quickly surface other opportunities that fit your style and risk tolerance.
- Target potential bargains by zeroing in on companies that pass strict quality checks and still trade below intrinsic assessments through the 4 high quality undervalued stocks.
- Strengthen your income stream by scanning for businesses that offer resilient payouts using the 5 dividend fortresses.
- Reduce portfolio surprises by filtering for companies with sturdier finances through the 6 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com