
Mitie Group (LSE:MTO) Following Fresh Stake Disclosures Is The Turnaround Story Already Priced In
Mitie Group (LSE:MTO) has attracted a cluster of new disclosures, with Weiss Asset Management, Natixis, Millennium and Qube Research all reporting sizeable interests in the facilities services specialist under Rule 8.3 of the Takeover Code.
Set against these fresh Rule 8.3 disclosures, Mitie Group’s 1-year total shareholder return of 34.16% and 3-year total shareholder return of about 2.4x, alongside a 27.64% year to date share price return and a £2.106 latest share price, indicate that momentum has been building rather than fading.
Scan how other facilities and support services stocks with solid balance sheets are trading by checking our hand picked list of solid balance sheet and fundamentals (9 results) alongside Mitie Group today.
Mitie Group now trades close to the average analyst target, while an intrinsic value estimate points to a much steeper discount. Is the market’s caution on this rerated contractor misplaced or entirely rational?
Most Popular Narrative: 1% Overvalued
Mitie Group trades at £2.106 against a narrative fair value of £2.09, so the widely followed thesis effectively treats today’s price as baking in most of the expected execution on projects, cost savings and capital returns.
The facilities transformation 3-year plan that aims to move Mitie Group from traditional facilities management toward technology led and data rich projects is now supported by projects revenue of £1.4bn since 2023 and a target for a £2bn plus projects business over the next few years, which directly targets higher project margins and profit growth.
See why 37 investors see Mitie Group as 1% overvalued.
Result: Fair Value of £2.09 (OVERVALUED)
Still, higher employer national insurance costs and the drag from underperforming Technical Services contracts could unsettle the Mitie Group story if recovery efforts disappoint.
Find out about the key risks to this Mitie Group narrative.
Another View: SWS DCF Signals A Very Different Price For Mitie Group
The P/E based narrative presents Mitie Group as fairly valued to slightly expensive around £2.11. Our DCF model tells a very different story. On that cash flow view, an estimated value of £6.32 per share suggests the current quote is trading at a heavy discount. Which lens do you trust more for a long term assessment of this contractor?
For a closer look at the assumptions and moving parts behind that cash flow view, Look into how the SWS DCF model arrives at its fair value.
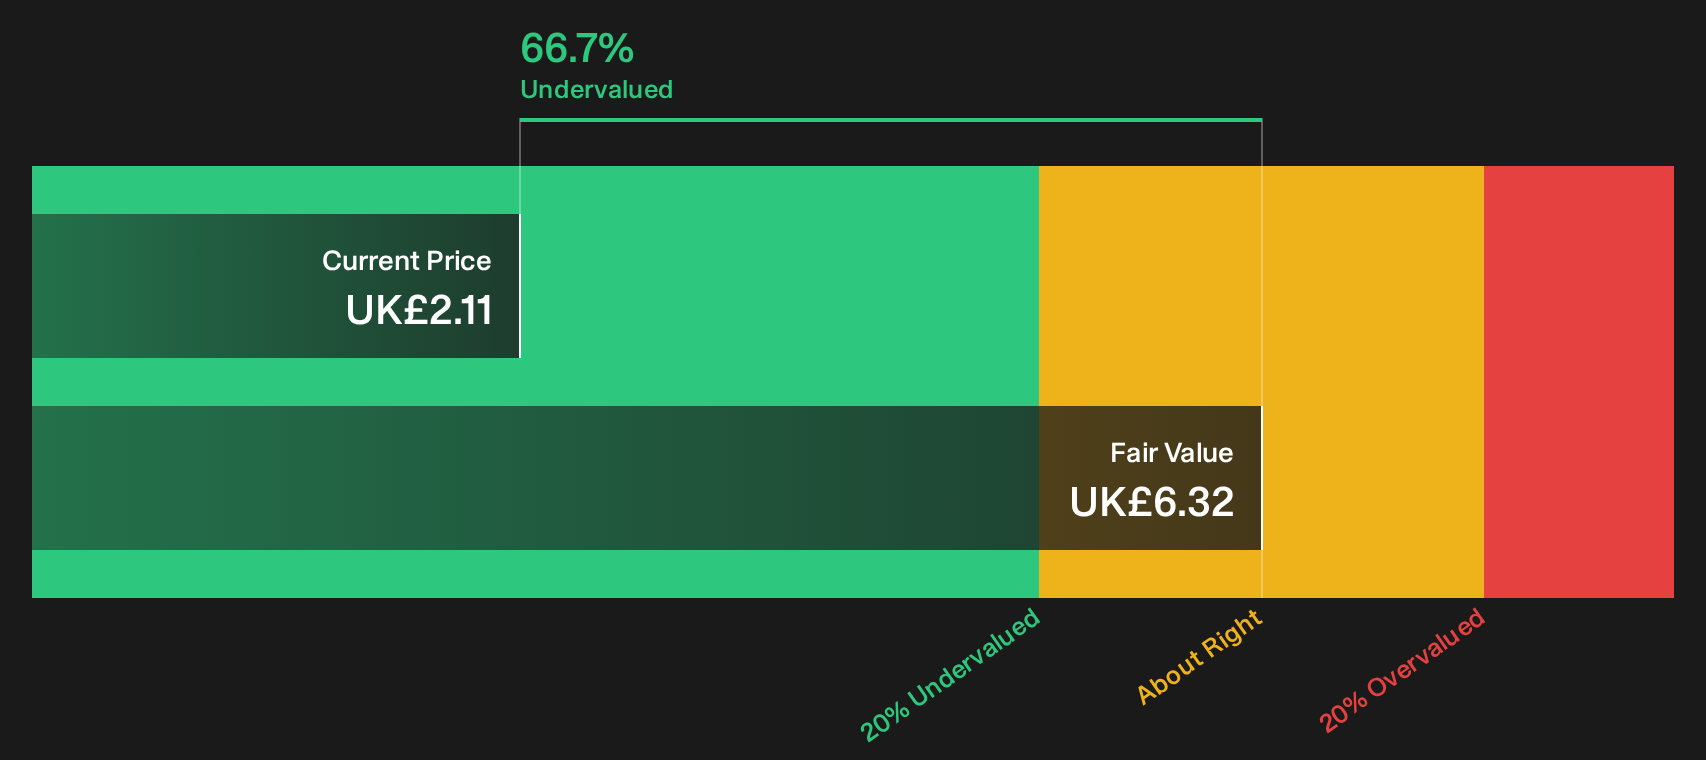
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Mitie Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 6 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or clear opportunity: either way the next move rests with you, so take a moment to weigh both sides of the story and walk through the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Mitie Group?
Mitie Group might be on your radar already. The next strong contender in your portfolio could be hiding in plain sight on a targeted screener.
- Spot potential bargains before the crowd by scanning companies that screen as high quality and potentially mispriced through the 6 high quality undervalued stocks.
- Build a steadier portfolio base by focusing on businesses that pass strict balance sheet filters with our list of solid balance sheet and fundamentals (9 results).
- Hunt for underfollowed opportunities by filtering for resilient fundamentals in the 5 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com