
Wynn Resorts (WYNN) Hit By Encore Revenue Slump, Is The Stock Still 40% Undervalued?
The Massachusetts Gaming Commission reported that Encore Boston Harbor’s Gross Gaming Revenue fell 22% year over year and 26% month over month, coinciding with a strike by 1,350 workers that has disrupted operations.
For investors tracking Wynn Resorts, the Encore Boston Harbor hit comes on top of a weak run for the stock, with the 30-day share price return down 9.07% and the year-to-date share price return down 38.19% as labor disruption and softer sentiment have weighed on momentum. Over a longer horizon the picture is also challenging, with the 1-year total shareholder return down 35.95% and the 5-year total shareholder return down 14.47%. This signals that recent losses are adding to already muted long-term performance rather than a brief pullback after a strong run.
Scan beyond Wynn Resorts and stress test your thesis against our hand picked 33 high quality undervalued stocks that currently trade at a discount with solid cash flows and sturdier balance sheets.
Wynn Resorts has dropped hard, while analyst and intrinsic value estimates still sit far higher than the current US$75.76 share price. How wide is the real gap between today’s quote and fair value?
Most Popular Narrative: 40% Undervalued
Against Wynn Resorts’ last close at $75.76, the most followed narrative anchors fair value closer to $127. This frames a sizeable valuation gap that hinges on how new luxury projects and higher costs play out over the next few years.
Expansion of Wynn Resorts' premium-focused footprint through the Enclave tower at Wynn Palace, which is planned to add 432 all-suite rooms and materially increase room and suite capacity in Macau, could support higher gaming and non-gaming revenue once ramped. Management estimates point to roughly US$400 million of incremental gross gaming revenue and US$150 million to US$175 million of EBITDA.
See why 26 investors see Wynn Resorts as 40% undervalued.
Result: Fair Value of $127 (UNDERVALUED)
Still, the Encore Boston Harbor strike and rising operating costs in Las Vegas could squeeze Wynn Resorts’ margins and undercut the optimistic fair value story.
Find out about the key risks to this Wynn Resorts narrative.
Another View: What Multiples Say About Wynn Resorts
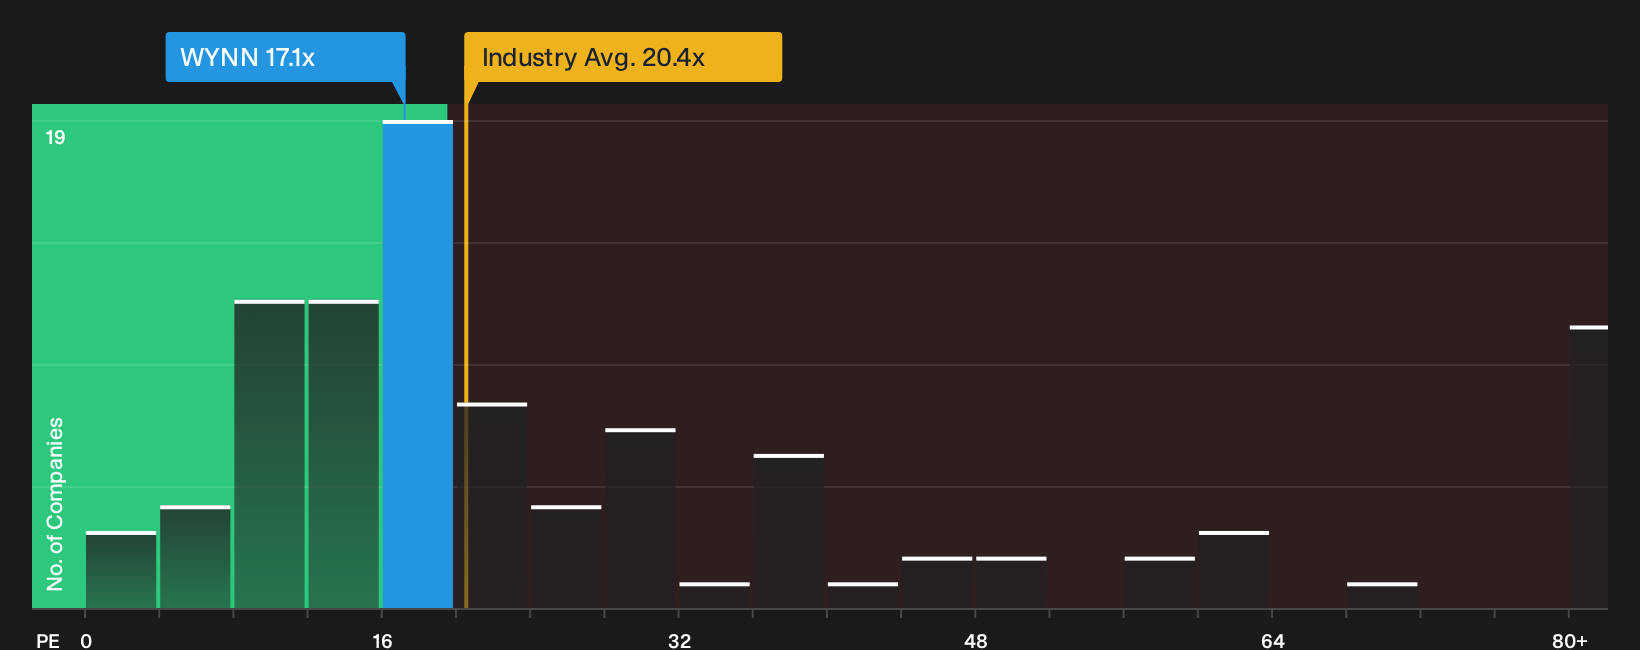
There is a different read on Wynn Resorts once you stop looking at fair value models and instead ask what investors are paying for each dollar of earnings. The stock trades on a P/E of 17.1x versus a 12.7x peer average and a fair ratio estimate of 18x.
That gap indicates the market is already assigning Wynn Resorts a premium to similar hospitality stocks, yet still slightly below where the fair ratio estimate suggests the P/E could settle over time. For anyone weighing upside against downside, the key question is whether this premium appears justified or potentially vulnerable if growth were to disappoint.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Wynn Resorts can feel messy, so move quickly from headlines to hard numbers and decide where you land on the risk reward line. To weigh both sides of the argument in one place, start with the 4 key rewards and 2 important warning signs.
Looking for more ideas beyond Wynn Resorts?
If Wynn Resorts leaves you torn between upside and risk, broaden your watchlist with a few focused stock groups that match different investing angles.
- Target potential turnaround stories by scanning the 10 elite penny stocks with strong financials that already pair tiny share prices with solid financial footing.
- Zero in on value by reviewing the 21 high quality undiscovered gems that combine strong fundamentals with limited market attention.
- Prioritise resilience by checking the 31 resilient stocks with low risk scores that already score well on financial strength and downside protection.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com