
Did AI Welding Launch Just Shift Lincoln Electric Holdings' (LECO) Investment Narrative?
- Lincoln Electric Holdings recently launched XpertLINC, a physical AI-enabled platform for its Cooper welding cobots that combines vision, coordinated motion, sensors and process control to adjust weld paths and parameters in real time without traditional programming or CAD files.
- The new system aims to address persistent automation pain points such as downtime, scrap and long changeovers by embedding Lincoln Electric’s welding know-how directly into the cobot workflow, which could influence adoption of its higher value automation solutions over time.
- We will now look at how Lincoln Electric’s investment narrative could shift as XpertLINC’s AI driven welding automation comes into focus.
Scan other robotics and automation plays riding similar trends to Lincoln Electric Holdings by reviewing the hand picked 93 robotics and automation stocks, which is shaping the next wave of factory-floor AI adoption.
Lincoln Electric Holdings Investment Narrative Recap
To own Lincoln Electric Holdings, you need to believe its welding automation and RISE efficiency program can keep turning a mature industrial franchise into a steadier compounder. XpertLINC fits that story by leaning into higher value cobots and systems, which ties directly into the push for better mix, margin structure and multi quarter automation backlog visibility.
The near term swing factor still looks operational rather than financial. Execution on automation orders and pricing actions matters more than this single product launch. Key risks stay grounded in cost inflation, softer automotive demand and geopolitical disruptions, any of which could pressure the margin uplift that the current efficiency narrative leans on.
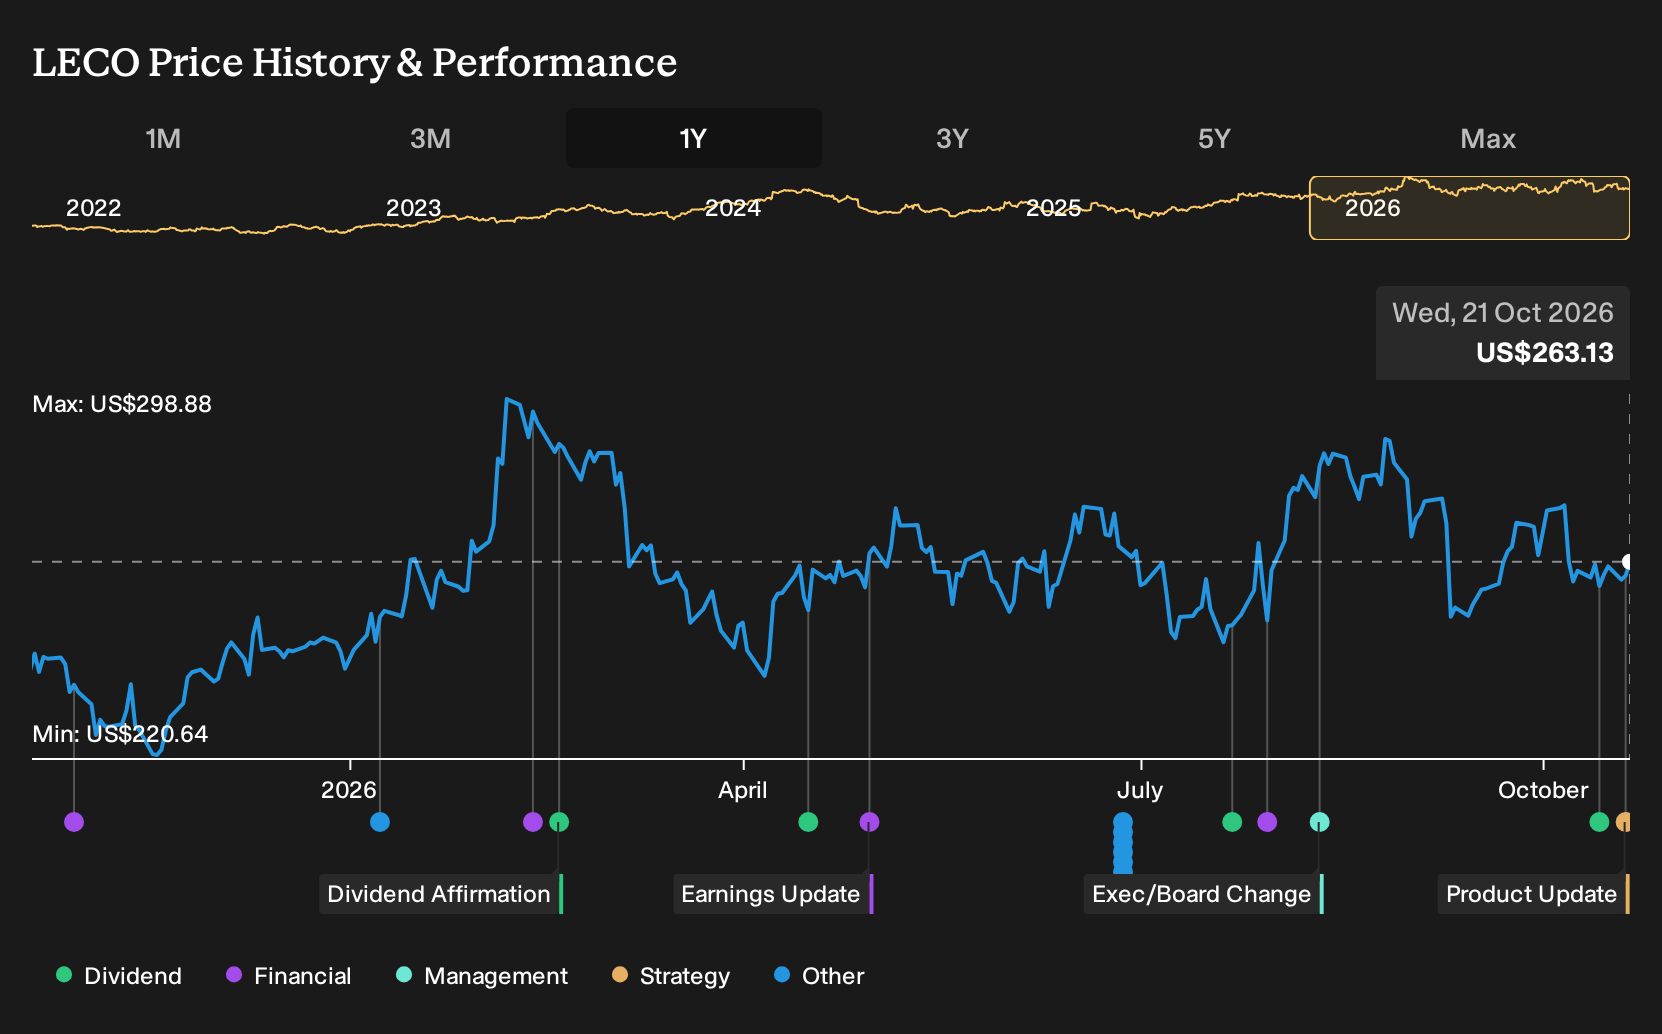
The most relevant fresh data point alongside XpertLINC is the 10% increase in the quarterly dividend to US$0.87 per share, or US$3.48 annualized, payable in January 2027. That move signals management’s confidence in cash generation from the existing welding, cutting and automation portfolio, not just from new AI driven platforms rolling out on Cooper cobots.
For you as a shareholder, this payout decision matters because it competes with R&D, automation capacity and bolt on deals for capital. Lincoln Electric Holdings has leaned on internal investment and acquisitions to add several points of annual sales growth. Sustaining both a richer dividend stream and those reinvestment plans will test how resilient margins and free cash flow really are if input costs or end market demand wobble.
What XpertLINC Means For Lincoln Electric Holdings' Forecasts
Lincoln Electric Holdings' AI focused welding push with XpertLINC builds on an already ambitious analyst playbook. Consensus models call for revenue to compound at 6.9% a year over the next few years, with profit margins expected to move from 12.4% today to 14.2% by around 2029 as automation, RISE efficiencies and mix help the income statement do more with each dollar of sales.
On earnings, the gap is clear enough for any shareholder to track. Analysts see profit rising from US$553.6 million today to US$778.7 million by 2029, which is roughly a 40% uplift in absolute dollar terms. That path also assumes the share count drifts lower by about 0.95% each year for three years, so per share economics tighten even if top line growth hits a speed bump at some point.
Those same forecasts sit underneath the current P/E debate around Lincoln Electric Holdings. The stock is on about 26.5x earnings today. Analyst targets effectively underwrite a 26.6x P/E on those 2029 estimates, compared with 23.7x for the US Machinery industry. For investors, the focus is less on a major rerating and more on whether the business can sustain that premium against peers while funding AI enabled automation like XpertLINC, supporting dividend growth and keeping buybacks in the mix.
Lincoln Electric Holdings' current analyst script points to US$5.5b in revenue and US$778.7 million in earnings by 2029, built on 6.9% yearly top line growth and an earnings increase of about US$225 million from US$553.6 million today.
Uncover why Lincoln Electric Holdings' fair value indicates a 16% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view on Lincoln Electric Holdings focuses on valuation risk. Those more cautious analysts were only pencilling in about US$5.3b of revenue and US$766.8 million of earnings by 2029 and a P/E near 21.5x before XpertLINC. That is a much cooler story. Use this launch as a prompt to compare these different expectations yourself.
Explore 4 other Lincoln Electric Holdings fair value estimates, including one that suggests it could be worth just $268.60.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Lincoln Electric Holdings research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Lincoln Electric Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lincoln Electric Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Lincoln Electric Holdings?
Lincoln Electric Holdings might be at the center of your watchlist today, but your next strong idea could sit in a very different corner of the market. Use the Simply Wall St Screener to widen the opportunity set without losing focus on quality and risk.
- If you want to limit downside first and upside second, start with a 31 resilient stocks with low risk scores that aims to keep drawdowns more manageable.
- For investors who care most about resilient balance sheets and steady fundamentals, filter the universe through a list of solid balance sheet and fundamentals (25 results) that can handle tougher conditions.
- When you are hunting for underappreciated opportunities with room for sentiment to catch up to fundamentals, scan the market using a 21 high quality undiscovered gems that many investors may not be watching yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com