
What Kesko Oyj (HLSE:KESKOB)'s Sales Growth Means For Shareholders
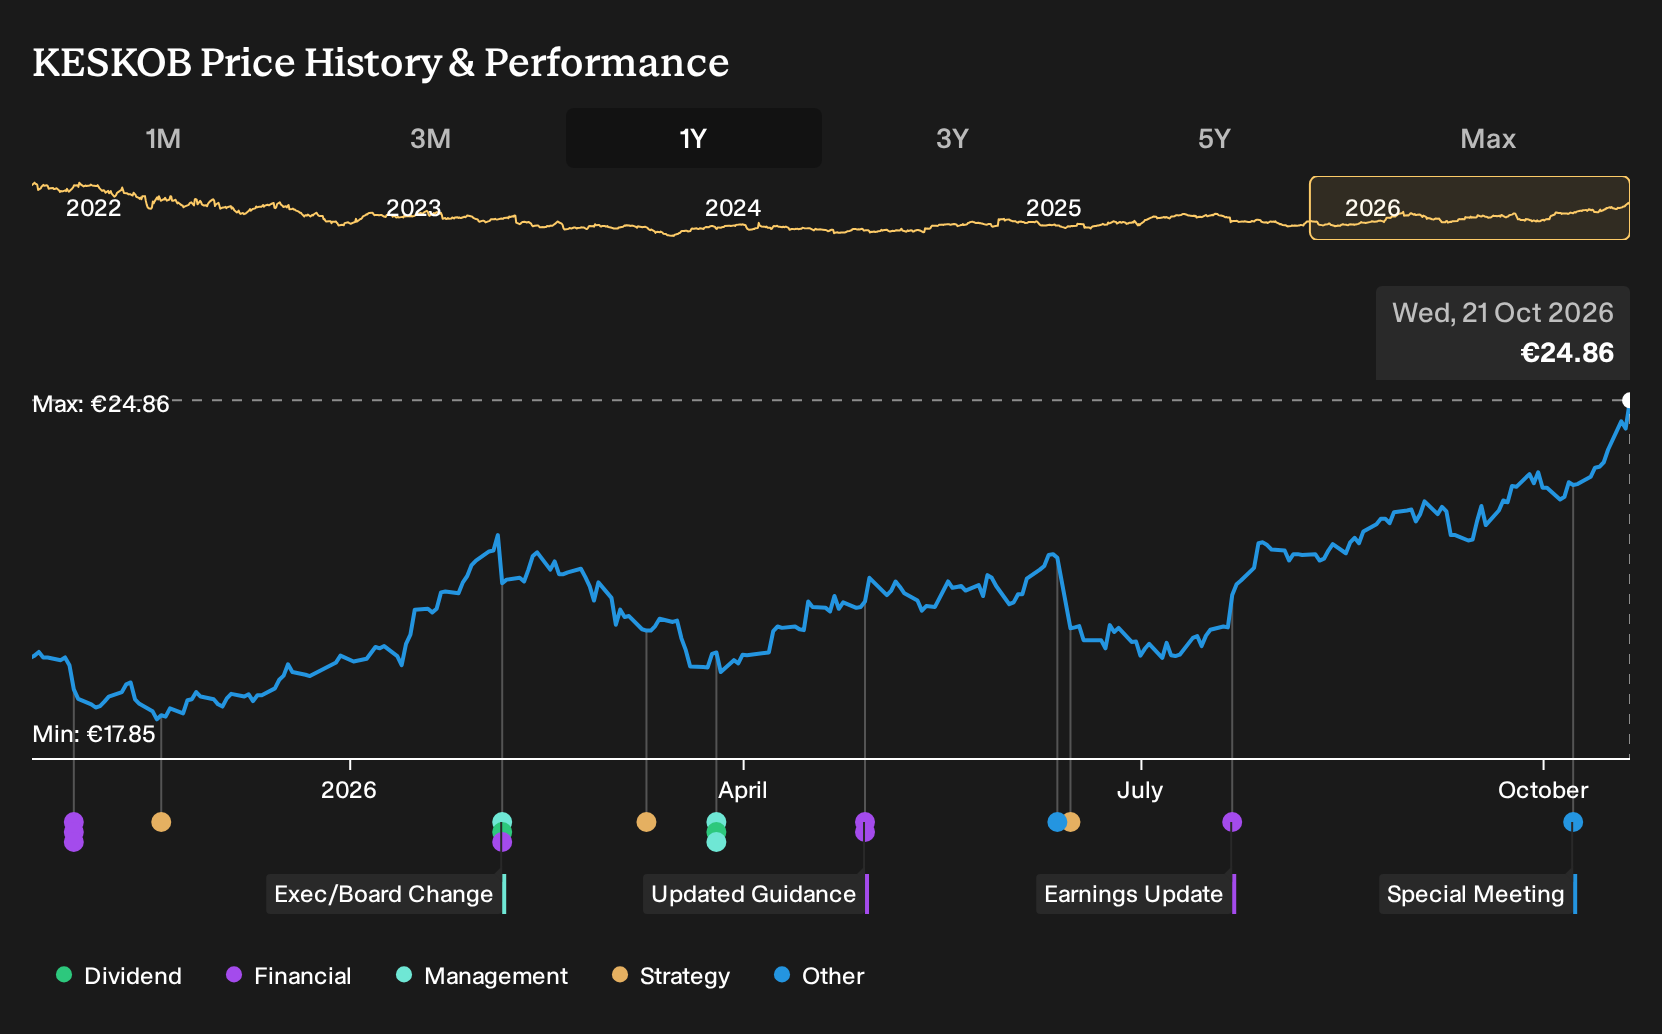
- Kesko Oyj reported Group sales of €1,198.4 million for September 2026, up 4.8%, with year-to-date Group sales reaching €3,477.8 million.
- The combination of monthly and year-to-date sales growth indicates demand across Kesko Oyj’s core retail segments rather than a one-off spike.
- We will now look at how Kesko Oyj's September sales performance could reshape the investment narrative already built around it.
Scan how Kesko Oyj’s solid September sales compare with other retailers by tracking hand-picked consumer stocks in the 190 high quality undervalued stocks that may also be seeing steady demand.
Kesko Oyj Investment Narrative Recap
Owning Kesko Oyj means believing that multi format retail across grocery, building and technical trade, and car trade can compound steadily even when individual end markets move at different speeds. The September Group sales of €1,198.4 million and year to date figure of €3,477.8 million support the idea that customer demand is present across the portfolio rather than concentrated in one month.
In the near term, the key swing factor remains how well Kesko converts its heavy grocery and B2B investments into traffic and mix quality without giving up pricing power. The biggest risk is that a structurally slow Finnish grocery market and intense competition in technical trade keep margins tight, limiting any earnings uplift from the recent sales momentum.
Among recent information, the September sales update is the clearest operational signal for your thesis. It links directly to the core catalysts analysts focus on, such as expected 3.5% annual revenue growth and 8.8% forecast earnings growth, because it shows how the current store network and logistics setup are performing in real time.
Those same numbers also highlight the tension in Kesko Oyj’s story. Earnings grew 10.3% over the past year and margins ticked up to 3.3%. At the same time, the business carries high debt, faces slower expected revenue growth than the Finnish market, and operates with a P/E of 23.7x compared with lower sector averages. The sustainability of monthly sales prints like September’s matters for how these trade offs resolve.
Kesko Oyj’s current analyst script points to revenues of €14.6b and earnings of €589.7 million by 2029, based on an assumed 4.4% yearly increase in revenue and a move in profit from €418.2 million today to that 2029 consensus. That earnings path implies an increase of about €171.5 million from current levels, which investors can compare directly with today’s margins and the expected 4.0% profitability target in the forecast year.
Uncover why Kesko Oyj's fair value indicates a 6% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
The three fair value views from the Simply Wall St Community span roughly €23.3 to €48.0, which is a wide bracket for the same Kesko Oyj equity story. Those private forecasts were set before the September sales update. Treat them as a starting grid, and then weigh them against grocery CapEx risks and any recovery in European construction.
Explore 2 other Kesko Oyj fair value estimates, including one that suggests there may be as much as 93% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Kesko Oyj research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Kesko Oyj. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kesko Oyj's overall financial health at a glance.
Looking for more investment ideas beyond Kesko Oyj?
If the Kesko Oyj story has sharpened your thinking, use that momentum to widen your watchlist with a few focused stock shortlists built around clear, testable traits.
- For investors who care most about valuation and quality together, start with a curated set of companies that screen as 190 high quality undervalued stocks.
- If resilience and balance sheet strength sit at the top of your checklist, scan a list of solid balance sheet and fundamentals (203 results) that can help surface sturdier options for the next leg of your research.
- When you want to hunt for less crowded stories, broaden your search with a 618 high quality undiscovered gems that may sit off the usual radar but still show solid fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com