
Redeia Corporación (BME:RED), What Is Behind The Fresh Attention?
Nexans being picked as Preferred Supplier by Red Eléctrica, a subsidiary of Redeia Corporación (BME:RED), for the Mallorca Menorca 3 power link brings fresh attention to Redeia’s project pipeline and regulated infrastructure role.
At a share price of €14.73, Redeia Corporación has seen its 1-day share price return edge up 0.75%, although the 30-day and year-to-date share price returns are down 3.09% and 3.54%. The 1-year total shareholder return has declined 8.66%, while longer term 3-year and 5-year total shareholder returns of 10.67% and 1.93% point to relatively modest momentum building over time.
Scan 42 power grid technology and infrastructure stocks to see other regulated infrastructure plays that, like Redeia Corporación, could benefit from big-ticket grid upgrade projects and long-term electricity transmission demand.
Redeia Corporación’s shares have ticked up on the Nexans news after a weaker few months, which leaves you weighing an early entry versus waiting for a pullback. So what does the current valuation actually say?
Price-to-Earnings of 16.5x: Is it justified?
On the numbers, Redeia Corporación trades on a P/E of 16.5x, which sits slightly above the European electric utilities average of 15.5x but below the peer group at 28x. At a share price of €14.73, that leaves the stock looking neither outright cheap nor stretched when judging it against similar businesses.
The P/E ratio compares what you pay per share to the earnings that Redeia Corporación generates per share. For a regulated grid operator with steady but moderate forecast earnings growth of 4.8% per year, this kind of earnings multiple often reflects investors paying for income stability and cash generation rather than rapid expansion.
There is a split picture once you compare this valuation more broadly. Against the European electric utilities sector, Redeia Corporación looks expensive, which suggests the market is willing to pay a premium relative to that group. Against its selected peers on a P/E of 28x and an estimated fair P/E of 16.9x, the current 16.5x looks much closer to a level the market could drift toward, implying only a small adjustment would be needed to line up with that fair ratio.
Explore the SWS fair ratio for Redeia Corporación.
Result: Price-to-Earnings of 16.5x (ABOUT RIGHT)
Still, Redeia Corporación’s story can be knocked off course if regulated returns are reset less favorably or if large grid projects face political or permitting delays.
Find out about the key risks to this Redeia Corporación narrative.
Another view on Redeia Corporación’s value
There is a different signal coming from our DCF model. On that measure, Redeia Corporación at €14.73 is trading above an estimated future cash flow value of €12.79, which points to the shares looking overvalued rather than fairly priced. So which lens should investors rely on when earnings and cash flow suggest different conclusions?
Look into how the SWS DCF model arrives at its fair value.
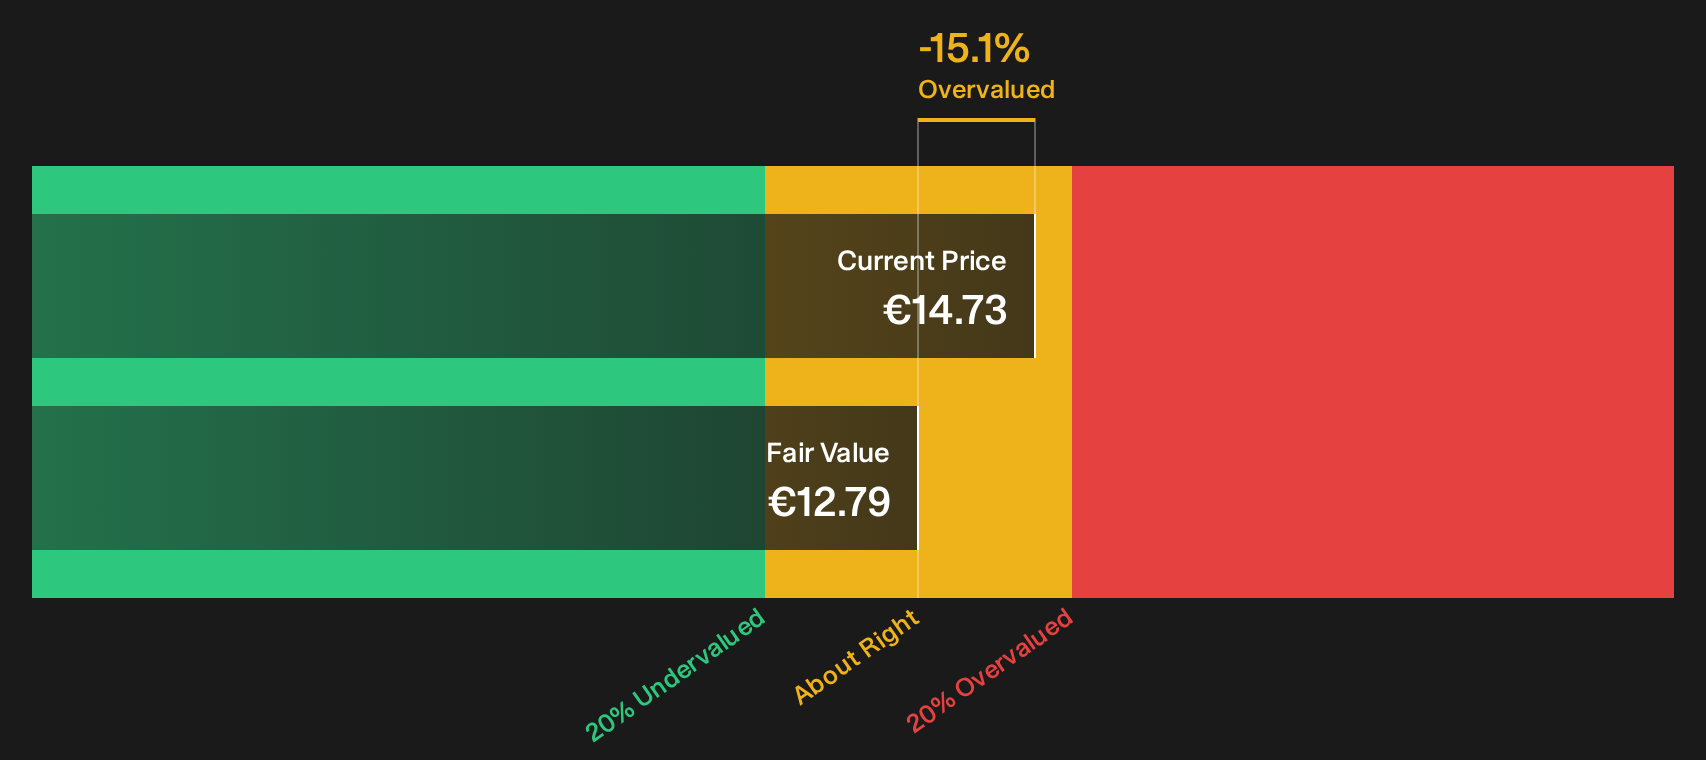
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Redeia Corporación for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 189 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Redeia Corporación so far, right. If you want to move quickly yet on your own terms, weigh both the risks and the potential upside in the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Redeia Corporación?
If Redeia Corporación has your attention, do not stop here. Line up a few more quality candidates so you are not relying on a single opportunity.
- Target resilient income potential while keeping quality in focus through 221 dividend fortresses.
- Hunt for mispriced opportunities with sturdy fundamentals using the 189 high quality undervalued stocks.
- Prioritise capital protection first by scanning the 227 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com