
How Investors May Respond To First Merchants Stock As Earnings Beat Meets Higher Charge Offs
- First Merchants reported Q3 2026 net interest income of US$161.07 million and net income of US$68.32 million, with adjusted earnings per share of about US$1.10, while net charge offs for the quarter reached US$29.389 million compared with US$5.148 million a year earlier.
- The bank paired stronger earnings and higher net interest income with a sizable jump in charge offs, highlighting both revenue traction and rising credit costs inside the loan book.
- The focus now is on how First Merchants' investment narrative reflects stronger earnings alongside materially higher credit charge offs this quarter.
First Merchants Investment Narrative Recap
To own First Merchants, you need to believe the bank can keep building earnings from its Midwestern loan and fee franchises while keeping problem credits contained. The Q3 print supports the earnings side, with higher net interest income and EPS from continuing operations, but the spike in net charge offs puts more weight on credit discipline as the key short term swing factor.
The main near term catalyst is still execution on the balance sheet remix into higher yielding loans and continued operating efficiency from digital investments. The largest risk is that elevated credit costs persist rather than prove temporary. If that happens, the extra revenue power has less impact on bottom line progress.
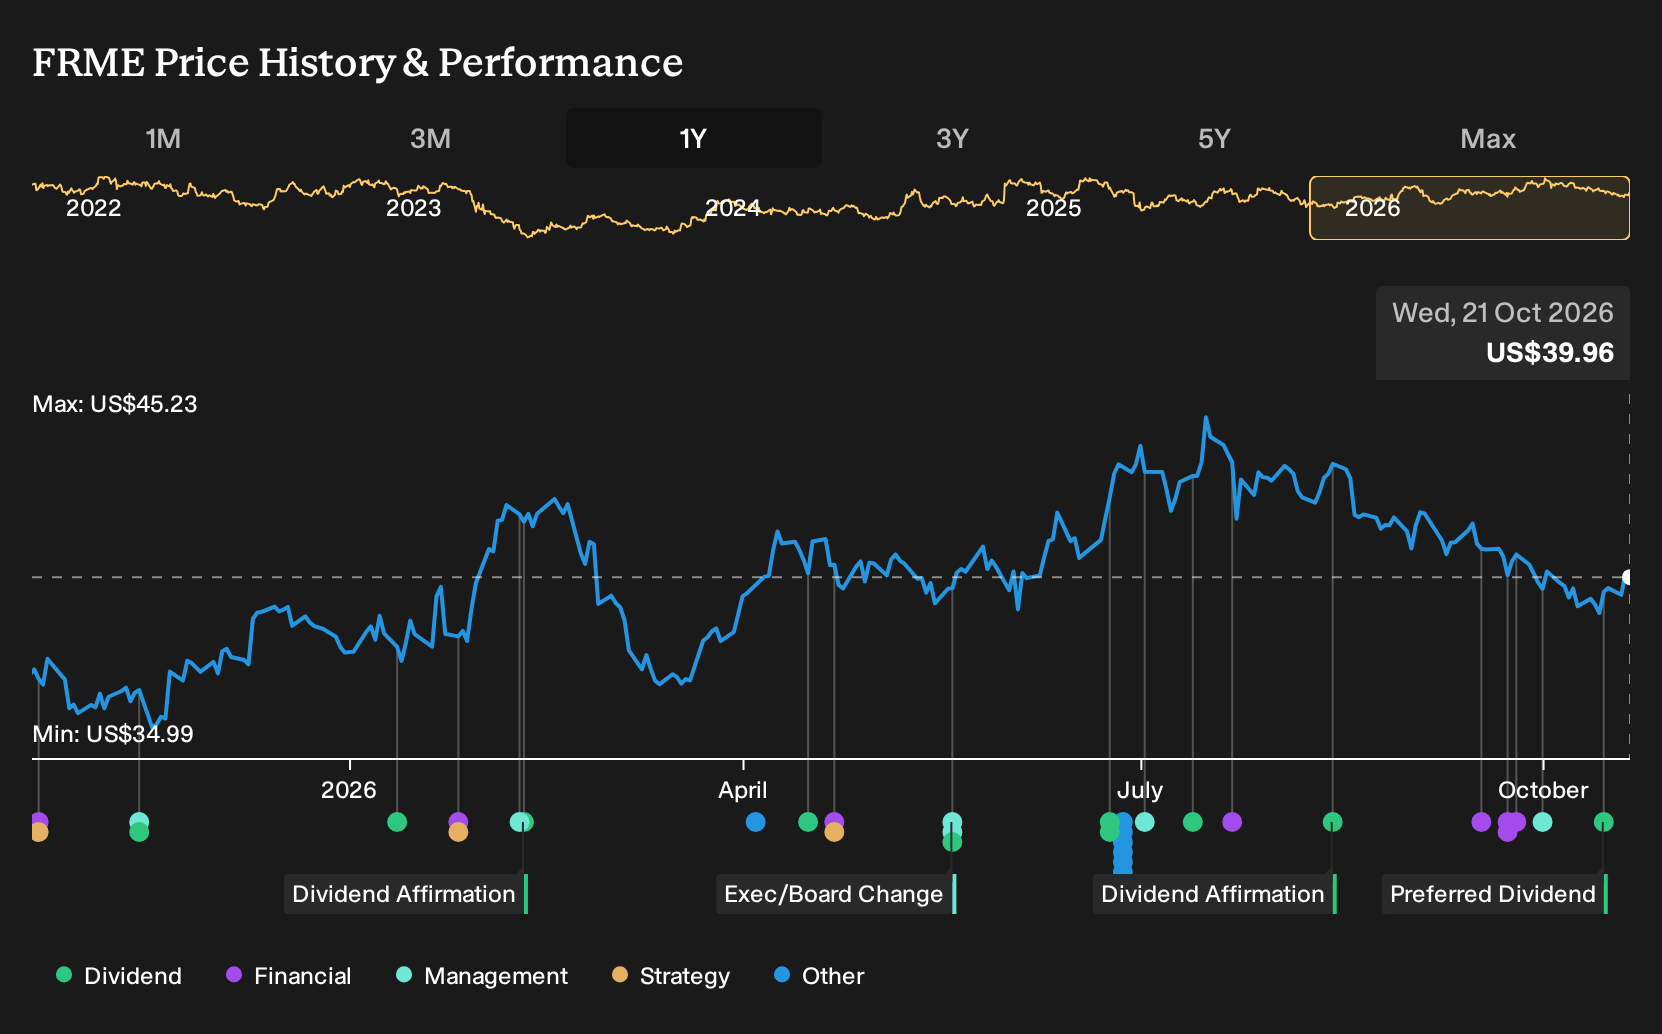
The recent preferred dividend declaration on the 7.50% Series A is the most relevant companion to these results. It underscores that First Merchants continues to service higher cost capital instruments at the same time credit expenses rose sharply in the quarter. That combination keeps the spotlight on how much earnings capacity is left after funding costs.
For investors watching catalysts, the preferred payout interacts directly with the existing story around capital deployment, buybacks and common dividends. Higher charge offs tighten the room for error. The more cash flow committed to preferred dividends and subordinated debt interest, the more important it becomes that loan growth, noninterest income and credit performance all stay aligned with the current plan.
First Merchants' current analyst story points to forecast revenue of US$985.3 million and earnings of US$347.2 million by 2029, built on an assumed 15.3% yearly revenue growth rate and an earnings increase of about US$163.1 million from US$184.1 million today.
Uncover how First Merchants' fair value indicates an 18% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
Fair value estimates for First Merchants from 2 private investors in the Simply Wall St Community span roughly US$47 to about US$73 per share, so you are seeing very different expectations in play. When you set those against rising net charge offs and higher cost capital instruments, the spread in opinions makes sense. Use this as a prompt to compare several viewpoints before deciding how these earnings and credit trends fit your own thesis.
Explore another First Merchants fair value estimate, including one that suggests it could be worth just $47.00.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your First Merchants research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for First Merchants. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate First Merchants' overall financial health at a glance.
Looking for more investment ideas beyond First Merchants?
Once you have a view on First Merchants, it helps to line it up against other options that fit different roles in your portfolio. Use the Simply Wall St Screener to quickly filter for stocks that match the mix of earnings quality, balance sheet strength and income profile you care about.
- For investors who like to balance growth with financial resilience, start with a list of solid balance sheet and fundamentals (25 results) that can help anchor a portfolio through different parts of the cycle.
- If income is a priority, scan for yield opportunities with the 7 dividend fortresses that combine meaningful payouts with underlying business strength.
- Those hunting for mispriced quality can review a 21 high quality undiscovered gems that might not be widely followed yet still show solid fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com