
Harmony Biosciences Holdings (HRMY) Names Its Next CEO, Is It Still Below Fair Value?
Harmony Biosciences Holdings (HRMY) is moving through a planned leadership handover, with long-time CEO Jeffrey M. Dayno, M.D., set to retire and Chief Operating Officer Peter Anastasiou stepping into the top job on January 1, 2027.
Against that leadership backdrop, Harmony Biosciences Holdings has had a mixed run on the screen. The share price is up 7.01% over the past 90 days but down 9.00% over 30 days. Meanwhile, the 1-year total shareholder return of 45.83% and 3-year total shareholder return of 97.37% point to momentum that has been built over a longer stretch than the recent pullback suggests.
Spot 37 healthcare AI stocks that, like Harmony Biosciences Holdings, are tying specialized therapies and management shifts to potential inflection points in their share price profiles.Given Harmony Biosciences Holdings has pulled back over 30 days yet kept its 1 year and 3 year returns firmly positive, does it make more sense to step in now or hold out for a cheaper entry and clearer succession?
Most Popular Narrative: 20% Undervalued
Harmony Biosciences Holdings closed at $38.31, while the most followed valuation narrative anchors fair value around $47.64 and points to a wider $165.35 future cash flow estimate, which frames the recent pullback very differently to the near term chart.
Use of Harmony Biosciences Holdings' cash position of about US$962.5 million against US$155 million of debt, together with ongoing profitability, provides capacity to fund R&D and business development transactions aimed at products with 2028 to 2032 launch windows. These can support post 2030 revenue and earnings. Execution on an intellectual property and litigation program that includes a multilayered pitolisant patent estate, settlements with most generic filers and new amorphous pitolisant rights, supports WAKIX market exclusivity into March 2030 and potentially longer through next generation formulations. This can help sustain revenue and cash flow while pipeline assets mature.
See why 104 investors see Harmony Biosciences Holdings as 20% undervalued.
Result: Fair Value of $47.64 (UNDERVALUED)
Still, the Harmony Biosciences Holdings story can crack if WAKIX concentration bites harder than expected, or if late stage pitolisant programs encounter approval or timing setbacks.
Find out about the key risks to this Harmony Biosciences Holdings narrative.
Another View: Harmony Biosciences Holdings Through Market Ratios
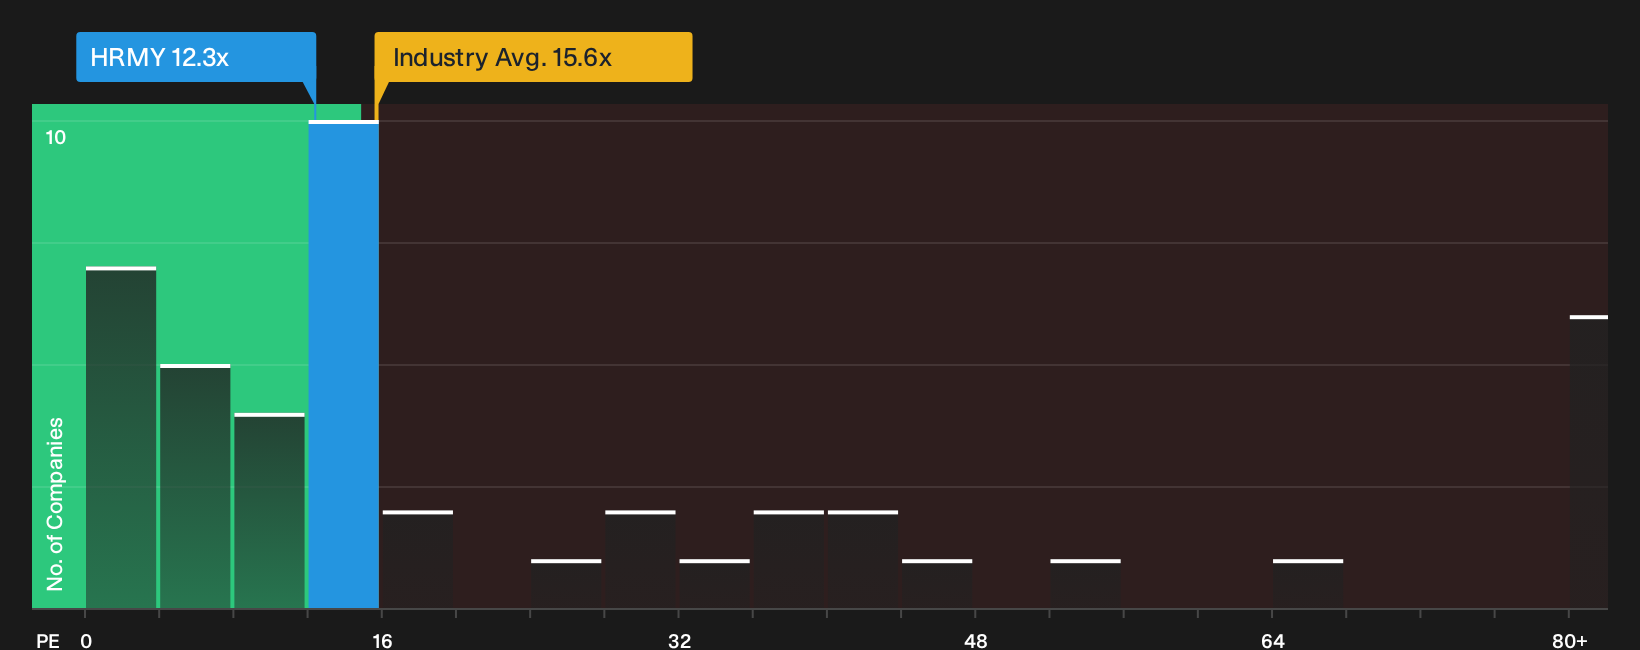
A second lens is far simpler than a cash flow model. Harmony Biosciences Holdings trades on a P/E of 12.3x, almost identical to its peer group at 12.2x, yet below an estimated fair ratio of 17.8x. That mix points to limited downside help from valuation if growth stumbles, but some upside if sentiment shifts toward the fair ratio. Which side of that tradeoff feels more compelling to you?
See what the numbers say about this price in more detail in our valuation breakdown, then decide how much weight to give earnings multiples versus long term cash flows yourself. See what the numbers say about this price — find out in our valuation breakdown.
Relative pricing versus similar pharmaceuticals, and against the market's own fair ratio, matters because it shapes how quickly sentiment can swing if expectations change.
Next Steps
Curious whether the optimism around Harmony Biosciences Holdings really stacks up for you personally? Take a quick pass through the data, then weigh those potential upsides yourself by checking the 3 key rewards.
Looking for more Harmony Biosciences Holdings style ideas?
If Harmony Biosciences Holdings has sharpened your focus, do not stop here. Fresh ideas often show up where the market is not looking yet.
- Target more conservative opportunities by scanning a 31 resilient stocks with low risk scores that aims to keep downside pressures contained while you assess potential upside.
- Hunt for quality at a discount by reviewing a 33 high quality undervalued stocks that blends solid cash generation with balance sheets that can handle tougher conditions.
- Spot early-stage potential by checking a 21 high quality undiscovered gems where fundamentals matter more than headlines and liquidity can still work in your favour.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com