
Did Higher Earnings Estimates Just Shift Emerson Electric's (EMR) Investment Narrative?
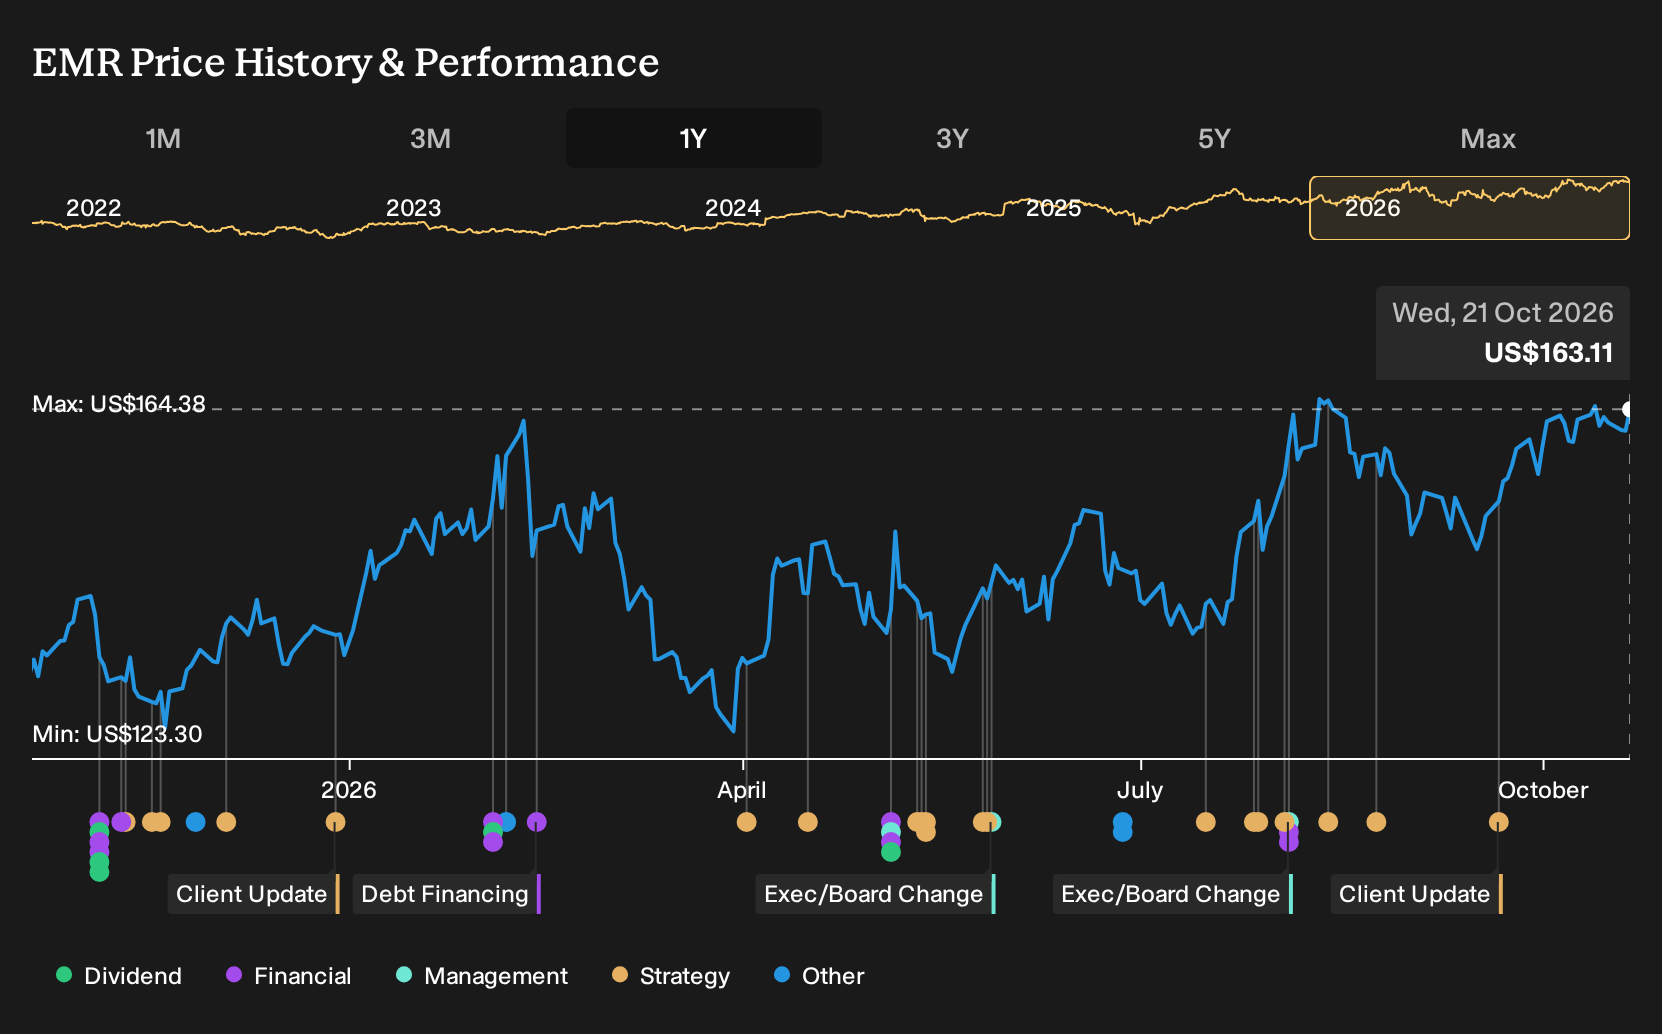
- Emerson Electric recently became a focus for investors after its shares outperformed both the S&P 500 and its manufacturing electronics peers, ahead of an earnings report scheduled for 4 November 2026 that carries higher analyst projections for quarterly earnings per share and revenue.
- The more interesting angle is how these higher earnings estimates and the Zacks Rank #2 rating reflect confidence in Emerson Electric’s ability to convert its current order and project funnels into stronger reported results, rather than just short term optimism about the stock.
- We will now look at how Emerson Electric’s investment narrative could be affected by these upbeat earnings revisions ahead of the upcoming report.
Scan how Emerson Electric’s setup compares with other potential breakouts by running your eye over our handpicked 33 high quality undervalued stocks that also carry upbeat earnings sentiment.
Emerson Electric Investment Narrative Recap
To own Emerson Electric, you need to believe its big project funnels in power, LNG, software and Test & Measurement keep turning into actual equipment deliveries and recurring software contracts. The upbeat earnings expectations put a spotlight on near term execution. The key short term catalyst is still converting those large backlogs into revenue without slipping schedules.
The biggest operational risk remains disruption in key regions and verticals. Conflict related shutdowns in the Middle East and weak demand in China, especially in chemicals, already weigh on expectations. The recent optimism around the upcoming earnings report does not remove those pressures; it just raises the bar on delivery.
The most relevant recent development is the upward revision in earnings and revenue estimates tied to Emerson Electric ahead of the 4 November 2026 report. That revision effectively tightens the link between order strength in areas like AI enabled automation, LNG and power projects and what has to show up on the income statement over the next few quarters.
For you as a shareholder, the catalyst is straightforward and operational. Investors now watch whether software annual contract value around US$1.64b to US$1.68b, the US$3b power funnel and the US$2.2b LNG funnel keep translating into higher margin sales and recurring revenue, while project delays, regional conflicts and China softness remain contained.
What The Current Analyst Setup Implies For Emerson Electric
Analysts are effectively tying Emerson Electric’s story to a multi year ramp in both sales and profitability. Consensus numbers point to revenue growing by 5.6% a year over the next 3 years, with profit margins moving from 13.8% today to 17.2% by around 2029. Earnings are projected to rise from US$2.6b today to US$3.8b by that same point, which is an increase of about 46%. Those assumptions sit behind a forecast for 2029 revenue of US$21.9b and earnings of US$3.8b, while the share count is expected to shrink by 0.71% annually as buybacks chip away at outstanding shares.
Emerson Electric's narrative projects revenues of US$21.9b and earnings of US$3.8b by 2029. This setup implies 5.6% yearly revenue growth and an earnings increase of about US$1.2b from current earnings of US$2.6b.
On top of the operating forecasts, the pricing discussion comes down to what multiple you think those future profits deserve. The current analyst framework assumes the stock would trade on a P/E of 33.4x in 2029, just below the 33.6x tag today and under the 35.2x level cited for the broader US electrical peer group. At a current share price of US$155.10, the consensus target of US$173.68 sits 10.7% higher. However, the spread between the most optimistic target of US$205.00 and the most cautious at US$104.00 shows how wide the range of views still is.
Uncover how Emerson Electric's fair value indicates a 6% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
You see one sharp point of disagreement around renewal risk. The lowest analysts focus on recent software renewal headwinds and frame a story where revenue only reaches about US$21.5b and earnings about US$3.7b by 2029. Those views sit well below today’s excitement and may shift once this earnings news is fully absorbed.
Explore 3 other Emerson Electric fair value estimates, including one that suggests as much as 49% downside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Emerson Electric research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Emerson Electric. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Emerson Electric's overall financial health at a glance.
Looking for more investment ideas beyond Emerson Electric?
Once you have a view on Emerson Electric, it helps to compare that thesis with a wider watchlist so you are not relying on a single story. The Simply Wall St Screener can surface very different types of opportunities, each with its own risk and return profile.
- If you want a wider margin of safety in volatile conditions, scan a curated 31 resilient stocks with low risk scores that score well on resilience and business stability.
- For investors who care about balance sheet strength first and everything else second, filter for a list of solid balance sheet and fundamentals (25 results) that can better withstand funding shocks and downturns.
- When you are hunting for future leaders that do not yet have broad coverage, sift through a 21 high quality undiscovered gems that combine quality fundamentals with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com