
SPIE (ENXTPA:SPIE) Has Investors Looking Closer, What Is Behind The Attention?
SPIE (ENXTPA:SPIE) has refinanced its sustainability-linked bonds by issuing a new €500 million instrument with a 5.5-year maturity and a 4.875% coupon, a move that directly affects balance sheet flexibility.
SPIE’s refinancing arrives after a stretch where the share price has eased, with the 30 day share price return down 4.23% and the year to date move down 16.30%. Even so, the 5 year total shareholder return of 122.50% shows how strong longer term holders have fared.
Scan refinancers like SPIE alongside other balance sheet focused opportunities using our hand picked 227 resilient stocks with low risk scores to see which businesses also prioritise resilience and funding flexibility.
SPIE’s refinancing and recent share price slide pull in opposite directions. Are investors reacting to sentiment swings, or to what the balance sheet and cash flows actually justify on today’s valuation multiples?
Most Popular Narrative: 21% Undervalued
SPIE’s most followed narrative sets a fair value of €52.00 against a last close of €41.18, which points to a meaningful valuation gap that depends on how execution, funding choices and segment mix develop over time.
Even though SPIE reports structurally strong cash generation, negative working capital around €800m and access to ESG linked financing including a €600m sustainability linked bond that supports more than €1.5b of liquidity, the continued use of this capacity for extensive M&A and shareholder returns raises the risk that any downturn in acquired activities such as industrial automation or cleanroom services would feed through disproportionately to free cash flow resilience and leverage metrics.
See why 4 investors see SPIE as 21% undervalued.
Result: Fair Value of €52.00 (UNDERVALUED)
Still, if SPIE continues to expand EBITDA margins above 6% and deploys its more than €1.5b in liquidity without increasing leverage, the rationale for the cautious €52.00 fair value case could diminish.
Find out about the key risks to this SPIE narrative.
Another View: What SPIE’s P/E Is Telling You
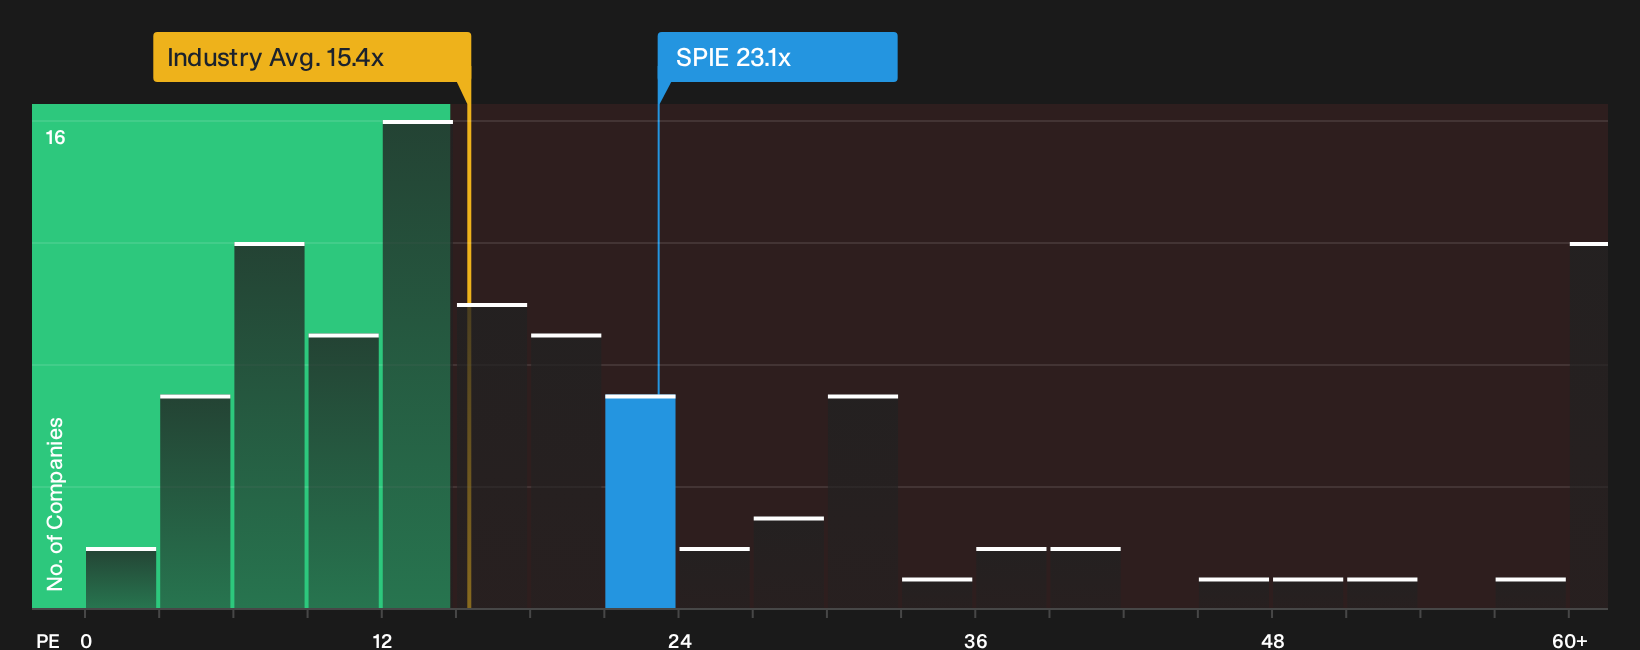
The earlier narrative leans on a fair value of €52.00. A different lens comes from SPIE’s current P/E of 23.1x, which is higher than the European Commercial Services group on 15.4x, its peer average on 14.8x, and the fair ratio estimate of 20.6x.
That gap suggests investors today are paying a richer price than both sector and fair ratio benchmarks imply. This raises the question of how much execution or earnings disappointment room the SPIE share price really has before that premium narrows.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Curious whether the mixed mood around SPIE really matches the numbers? Take a closer look at both sides of the story and weigh the 4 key rewards and 2 important warning signs.
Looking for more ideas beyond SPIE?
If SPIE has you thinking harder about valuation, liquidity and risk, you can use the same lens to explore other opportunities before they move without you.
- Hunt for quality at a discount by scanning companies that screen as high quality yet overlooked using our 190 high quality undervalued stocks.
- Aim to anchor your portfolio with income by zeroing in on sturdier payers through our 220 dividend fortresses.
- Prioritise resilience first by focusing on businesses with cleaner finances and funding strength using our list of solid balance sheet and fundamentals (203 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com