
Is Cochlear (ASX:COH) A Bargain After TIME Backed Its Nucleus Nexa System?
Cochlear (ASX:COH) is back in focus after TIME named its Nucleus Nexa System one of the Best Inventions of 2026, highlighting the smart cochlear implant platform with upgradeable firmware.
Despite the TIME recognition, Cochlear’s recent trading record is mixed. The A$140.59 share price follows a 90-day share price return of roughly 26%, but a year-to-date share price decline of about 46%, while the 1-year total shareholder return is down around 51%.
See how Cochlear compares with other high quality medical and technology leaders by reviewing a hand picked list of 15 high quality undiscovered gems in the market right now.
Cochlear shares have rebounded sharply over the past three months while still sitting well below where they started the year. This leaves a simple fork in the road for investors: pay up for the recent momentum now or wait for a cheaper entry as the valuation case unfolds next.
Most Popular Narrative: 101% Overvalued
Cochlear last closed at A$140.59, while the most followed narrative on the stock, according to Robbo, anchors fair value nearer A$70. That gap frames the current debate around whether the recent rebound is a temporary squeeze or a mispricing that still has room to unwind.
There has also been a dramatic recent decline in the company’s share price, which may suggest a potential buying opportunity. The sell-off followed an earnings downgrade, with management citing weaker-than-expected demand, hospital constraints, softer referral rates, and geopolitical risks.
See why 15 investors see Cochlear as 101% overvalued.
Result: Fair Value of A$70.00 (OVERVALUED)
Still, any meaningful reset in surgery volumes, or a sharper lift in competitors’ technology, could quickly challenge the current Cochlear overvaluation story.
Find out about the key risks to this Cochlear narrative.
Another View: Cochlear Through The DCF Lens
The fair value call around Cochlear flips completely when you look at our DCF model. On that framework, the A$140.59 share price sits roughly 38% below an estimated future cash flow value of about A$225.95. This frames the current weakness as a potential valuation gap rather than excess.
If cash flows really deserve that kind of premium, the key question for you is whether the earnings path justifies trusting the model or the market mood.
Look into how the SWS DCF model arrives at its fair value.
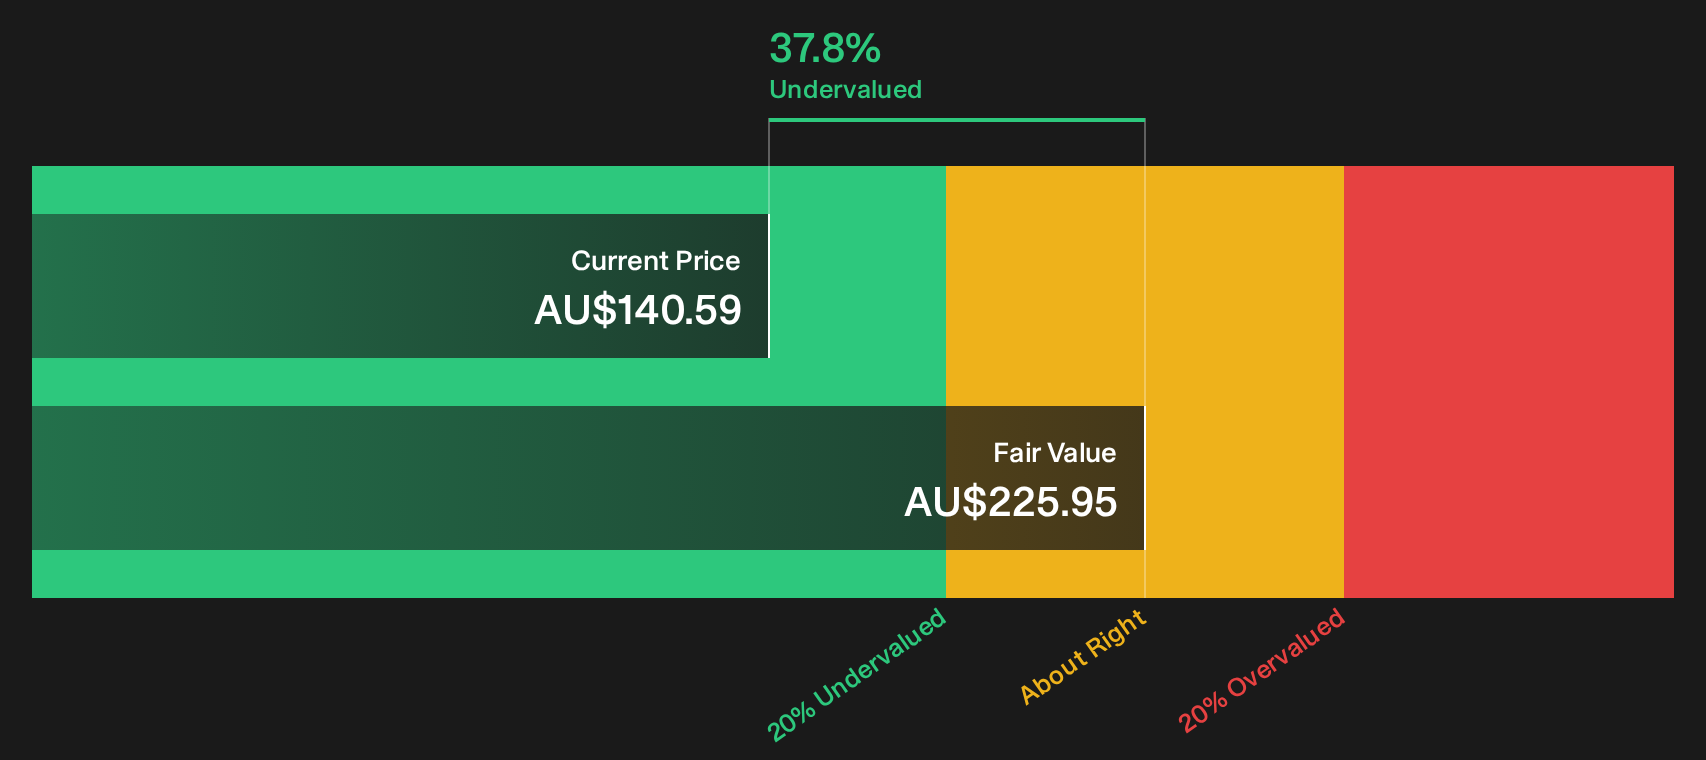
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Cochlear for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 4 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the split views on Cochlear feel sharp, that is the point. You are meant to pressure test the data yourself and decide quickly where you stand. To weigh both sides clearly, start with the 2 key rewards and 2 important warning signs.
Looking for more Cochlear-adjacent investment ideas?
Do not stop with Cochlear. Use this momentum to widen your watchlist, pressure test new themes, and spot opportunities before they crowd up.
- Target potential mispricing across the market by reviewing a hand picked 4 high quality undervalued stocks that may offer more compelling entry points than today’s headline stocks.
- Build resilience into your portfolio by focusing on companies with cleaner finances through our curated list of solid balance sheet and fundamentals (12 results).
- Lock in income-focused ideas by zeroing in on a shortlist of 5 dividend fortresses that could complement growth names like Cochlear.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com