
What Zebra Technologies Holders Bought Into
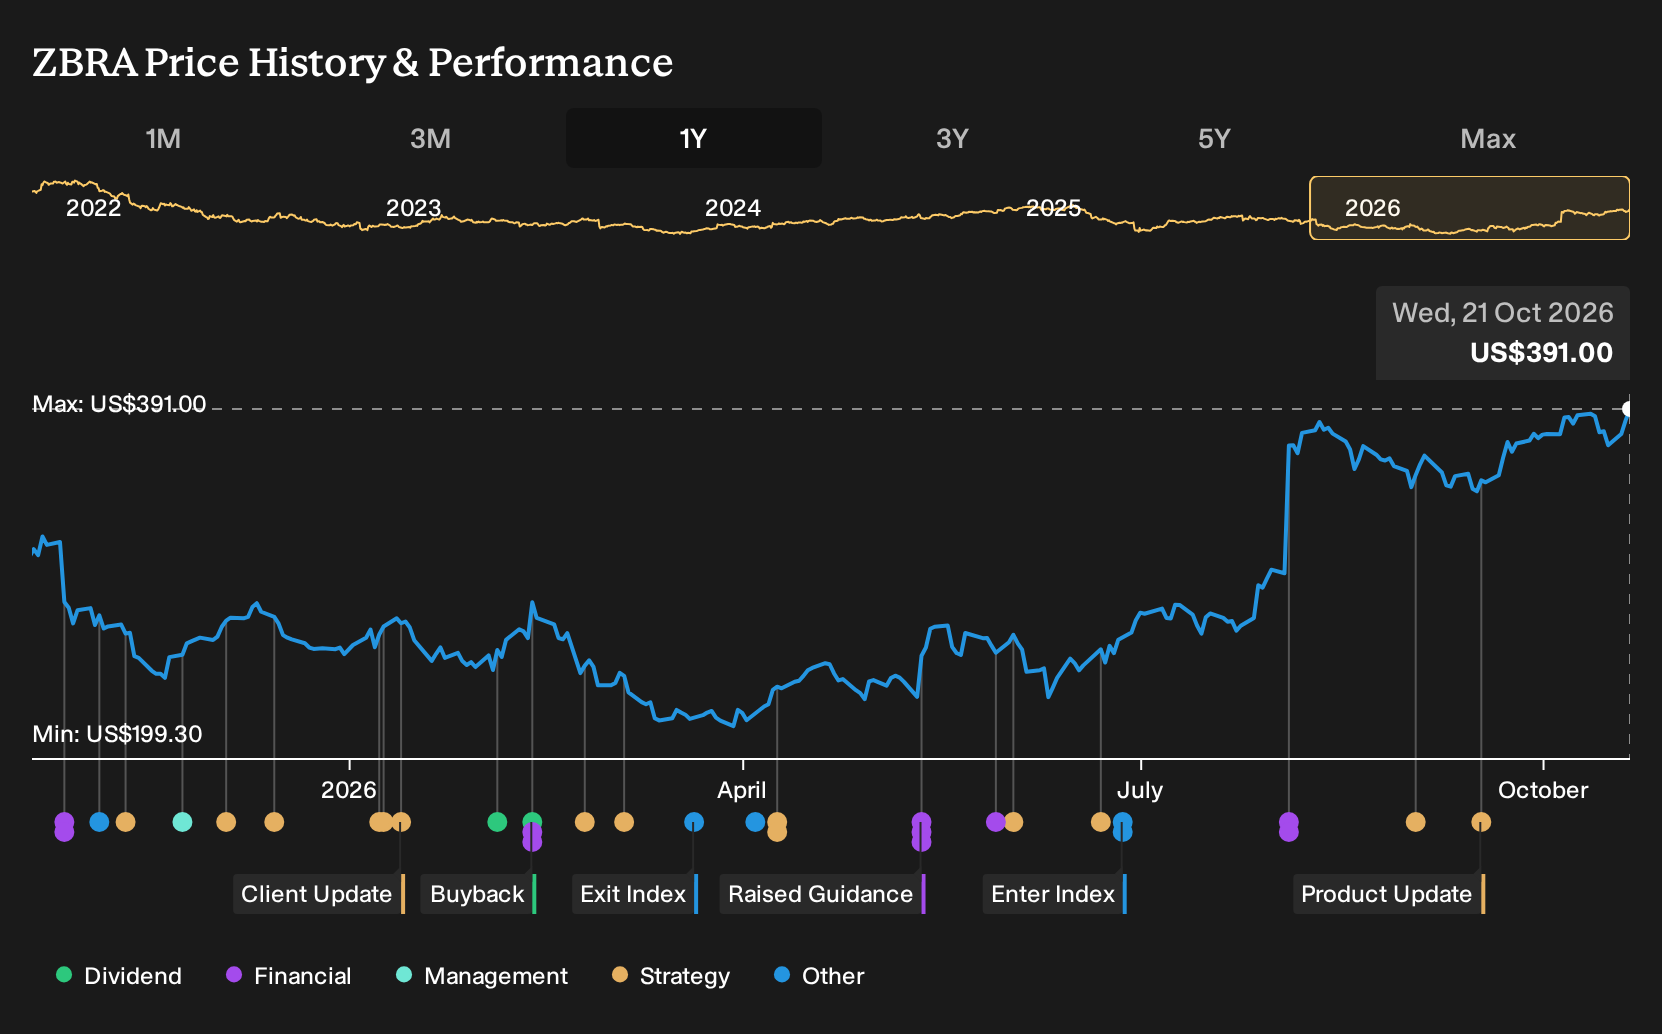
If you had chosen Zebra Technologies instead of sitting in cash, the past twelve months would look very different. Holding Zebra Technologies over the past year would have returned 29.2%, including dividends. That outcome lands between the October 2025 bullish view that digital transformation could justify a higher valuation and the bearish focus on tariff pressure and slower manufacturing demand. If you were making that choice on 21 October 2025, which of those competing stories would have carried more weight?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
Zebra Technologies is not the only name tied to this theme. Zero in on 93 robotics and automation stocks and compare how each one is priced.
The Argument Zebra Technologies Investors Were Weighing Up
The shares cost US$306 at the start of the period, and Zebra Technologies sat between two well defined stories about its future.
The bullish narrative in October 2025 put Fair Value at US$365, 19% above the start price. It leaned on assumptions such as 6.0% annual revenue growth and profit margins reaching 13.9%, supported by automation demand and the Elo acquisition.
The bearish April 2025 view pointed to a Fair Value of US$286, 7% below the start price. It focused on U.S. tariffs that could cut 2025 gross profit by US$70 million and pressure margins if pricing power fell short.
What The Results Changed For Zebra Technologies
Zebra Technologies reported Q2 2026 revenue of US$1.557b and net income of US$233m, compared with US$1.293b and US$112m in Q2 2025. Net margin moved from 8.7% to 15.0%. That improvement supported the bullish October 2025 view that higher profitability was possible, although tariff risks in the cautious case were not disproven. Overall, the evidence supported the optimistic case.
The whole episode turned on whether margins could rise while Zebra Technologies pushed deeper into automation. For a different stock, track net margin alongside any story about mix shift or efficiency, then test that claim each year against reported income and sales.
What Today's Zebra Technologies Price Already Assumes
Zebra Technologies now trades at US$391, up 29.2% over the past year. The selected Narrative places its Fair Value below that level, framing today’s quote as already baking in a confident path for earnings and cash generation.
The crux is execution. For today’s price to hold up, a buyer has to believe Zebra can keep mid 20s EBITDA margins while fully absorbing memory cost pressure through pricing, restructuring and volume.
"The main thing that has to go right is that Zebra Technologies converts secular demand for physical AI, automation and high value adjacencies like machine vision, RFID and Elo Touch into sustained mid 20s EBITDA margins, while fully offsetting the remaining memory cost headwind through pricing, restructuring and volume leverage."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
How Could You Get There Earlier?
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 26% below our estimate - sells injectable therapies for metabolic conditions as physicians broaden eligible patient groups.
- Company 2 - 40% below our estimate - expands targeted deposit verticals and digital payment channels to support relationship-based lending growth.
- Company 3 - 33% below our estimate - builds AI-focused infrastructure and managed multicloud databases supporting recurring enterprise usage commitments.
That is three of the list. See every one of the 33 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com