
October 2026 Global Undervalued Small Caps With Insider Activity
As global markets navigate the turbulence of AI-related sell-offs and inflationary pressures, small-cap stocks have become a focal point for investors seeking value amidst broader market rotations. The recent decline in the Russell 2000 Index highlights the shifting sentiment towards more defensive and value-oriented segments, setting the stage for identifying promising opportunities within undervalued small caps that exhibit insider activity.
Top 10 Undervalued Small Caps With Insider Buying Globally
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Q Technology (Group) | 3.3x | 0.2x | 46.63% | ★★★★★☆ |
| Timbercreek Financial | 16.7x | 9.7x | 38.50% | ★★★★★☆ |
| China Aircraft Leasing Group Holdings | 6.8x | 0.9x | 40.77% | ★★★★★☆ |
| Franchise Brands | 26.6x | 2.0x | 48.64% | ★★★★☆☆ |
| Pizza Pizza Royalty | 11.6x | 8.9x | 39.85% | ★★★★☆☆ |
| Saniona | 8.2x | 3.6x | 23.77% | ★★★★☆☆ |
| Sagicor Financial | 6.7x | 0.5x | -78.68% | ★★★★☆☆ |
| Centurion | 16.0x | 3.1x | 19.47% | ★★★☆☆☆ |
| MCAN Mortgage | 10.4x | 5.9x | -9.42% | ★★★☆☆☆ |
| Travis Perkins | NA | 0.3x | -234.93% | ★★★☆☆☆ |
Let's uncover some gems from our specialized screener.
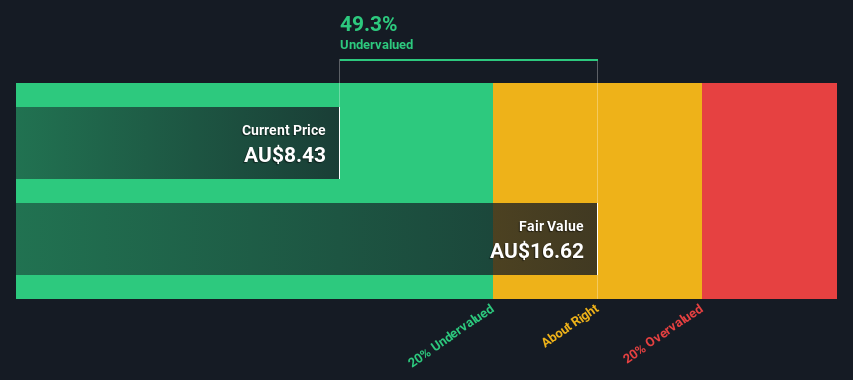
Iress (ASX:IRE)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Iress is a technology company that provides software solutions for the financial services industry, with a market cap of approximately A$1.73 billion.
Operations: The company generates revenue primarily from Global Trading & Market Data, Apac Wealth Management, and UK Wealth & Sourcing. Over recent periods, the gross profit margin has shown variability, with a notable increase to 38.40% in June 2026 from previous years. Operating expenses have fluctuated significantly, impacting net income margins which have also varied over time.
PE: 11.3x
Iress, a smaller company in the financial technology sector, recently reported half-year earnings with revenue at A$251.75 million and net income of A$31.96 million, showing improved profitability despite lower sales compared to last year. They announced an increased interim dividend of A$0.14 per share and have insider confidence through recent share purchases by executives this year. However, their funding relies entirely on external borrowing, adding risk to their balance sheet amidst lowered revenue guidance for 2026.
- Click to explore a detailed breakdown of our findings in Iress' valuation report.
Gain insights into Iress' historical performance by reviewing our past performance report.
RFM (PSE:RFM)
Simply Wall St Value Rating: ★★★☆☆☆
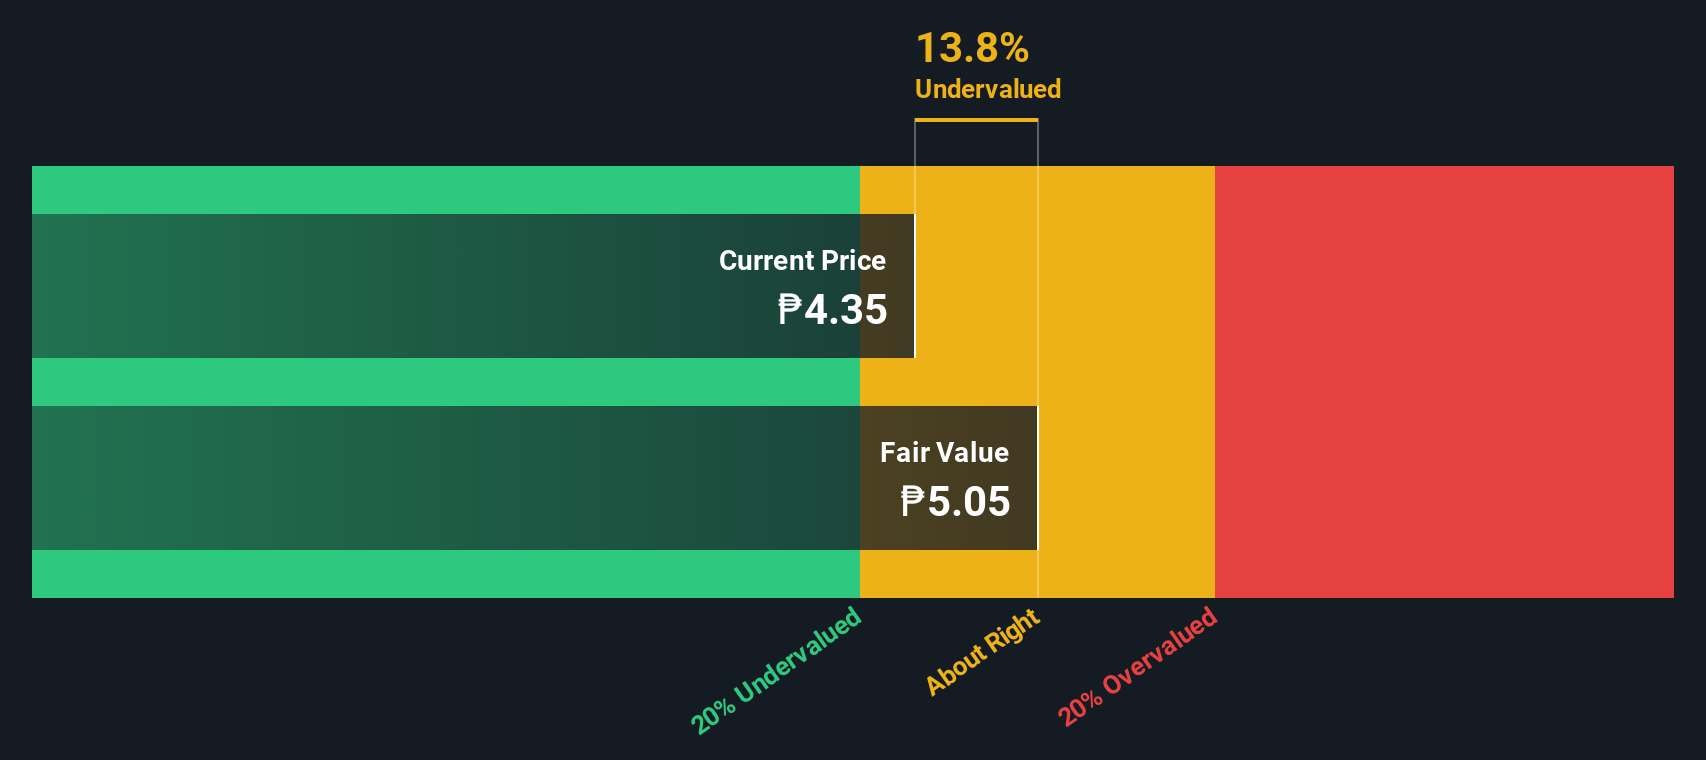
Overview: RFM is a food and beverage company in the Philippines involved in the production and distribution of products such as pasta, milk, ice cream, and flour with a market capitalization of ₱16.75 billion.
Operations: RFM generates revenue primarily through its sales, with a notable gross profit margin of 36.01% as of September 2026. The company's cost structure is heavily influenced by the cost of goods sold (COGS), which was ₱15.33 billion in the same period. Operating expenses, including sales and marketing, are significant components impacting net income margins, which stood at 7.26%.
PE: 10.4x
RFM's recent earnings reveal a solid performance, with third-quarter sales reaching PHP 6.4 billion, up from PHP 5.4 billion last year, and net income increasing to PHP 565 million from PHP 480 million. Basic earnings per share rose to PHP 0.17 from PHP 0.14, indicating growth momentum despite reliance on higher-risk external borrowing for funding. Insider confidence is evident as Emmanuel Bautista acquired shares worth approximately PHP 1.9 million in August, suggesting belief in RFM's potential amidst its small-cap status and current market valuation dynamics.
- Get an in-depth perspective on RFM's performance by reading our valuation report here.
Explore historical data to track RFM's performance over time in our Past section.
Pro Real Estate Investment Trust (TSX:PRV.UN)
Simply Wall St Value Rating: ★★★☆☆☆
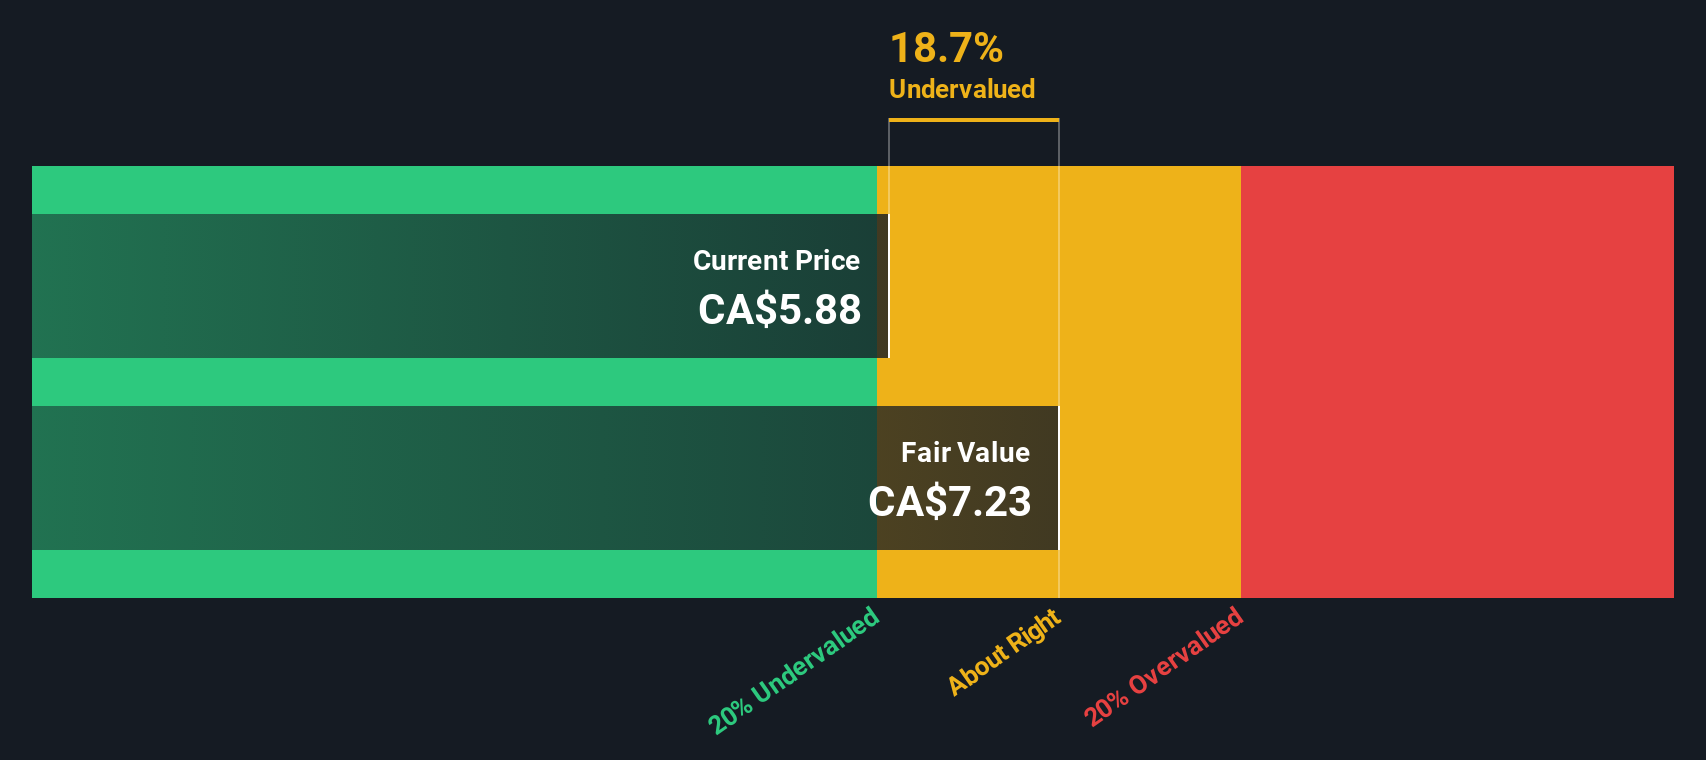
Overview: Pro Real Estate Investment Trust operates in the real estate sector, focusing on office, retail, and industrial properties with a market capitalization of CA$1.2 billion.
Operations: The company's primary revenue stream is from Industrial and Commercial Mixed Use properties, generating CA$96.00 million, significantly overshadowing its Office and Retail segments. The gross profit margin has fluctuated over time, with recent figures around 61.25%. Operating expenses have varied but generally remain a notable component of the cost structure, affecting net income outcomes alongside non-operating expenses.
PE: 13.9x
Pro Real Estate Investment Trust, a smaller player in the real estate sector, has recently maintained consistent cash distributions of C$0.0375 per unit monthly, equating to C$0.45 annually. Despite a dip in quarterly net income from C$5.24 million to C$2.02 million year-over-year, six-month earnings rose to C$24.55 million from C$20.28 million previously, indicating potential for growth amid fluctuating results. Insider confidence is evident with recent share purchases by company leaders within the last year, suggesting optimism about future prospects despite current reliance on external borrowing for funding needs and past shareholder dilution concerns.
Taking Advantage
- Dive into all 119 of the Undervalued Global Small Caps With Insider Buying we have identified here.
- Shareholder in one or more of these companies? Ensure you're never caught off-guard by adding your portfolio in Simply Wall St for timely alerts on significant stock developments.
- Invest smarter with the free Simply Wall St app providing detailed insights into every stock market around the globe.
Seeking Other Investments?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com