
Barrick Mining (TSX:ABX) Could Be 16% Undervalued After Q2 Earnings Jump
Barrick Mining (TSX:ABX) drew fresh attention after second quarter net earnings rose 50% year over year, as higher gold and copper prices coincided with heavier project spending and plans for an IPO of its North American gold assets.
The recent earnings jump and planned IPO have arrived while Barrick Mining’s share price has been choppy, with a 9.39% 90 day share price return but a decline of 4.55% over 30 days and a year to date fall of 5.45% from the current CA$57.22 level. Over a longer stretch, the picture looks stronger, with a 32.49% 1 year total shareholder return and very large 3 and 5 year total shareholder returns. This points to momentum that has cooled in the short term but remains intact over multi year periods.
Scan for other gold producers that show similar earnings momentum and project pipelines using the 35 elite gold producer stocks alongside Barrick Mining.
Earnings are moving in one direction, while the share price has cooled in the short term. For Barrick Mining at about CA$57, does a strong miner still come with a sensible price tag today?
Most Popular Narrative: 16% Undervalued
The most followed narrative on Barrick Mining puts fair value at CA$68.30, above the last close at CA$57.22. This frames the stock as undervalued on that view while still factoring in measured growth and risk assumptions.
Significant ongoing expansion of both gold and copper production capacity, particularly at Lumwana and via organic growth at Fourmile and Reko Diq, is viewed as positioning Barrick to capture elevated long-term demand for gold (as a financial hedge during geopolitical uncertainty and inflation) and copper (driven by electrification and infrastructure investment). This is seen as supporting top-line revenue growth over the coming decade.
Continued focus on Tier 1, long-life assets in stable jurisdictions, and the divestment of non-core projects (for example, Donlin Gold), are seen as enhancing operational resilience and production predictability, which are viewed as likely to result in stronger, more consistent free cash flow and net earnings.
See why 121 investors see Barrick Mining as 16% undervalued.
Result: Fair Value of CA$68.30 (UNDERVALUED)
Still, the bullish Barrick Mining narrative could crack if political issues in regions like Mali flare up again, or if stricter ESG rules push cash costs materially higher.
Find out about the key risks to this Barrick Mining narrative.
Another View On Barrick Mining’s Valuation
A different lens tells a very different story. The SWS DCF model puts Barrick Mining’s value at about CA$49.85 per share, below the current CA$57.22 price, which screens as overvalued on that cash flow view. With one model flagging upside and another pointing the other way, which framework do you trust more for your own checklist?
Look into how the SWS DCF model arrives at its fair value.
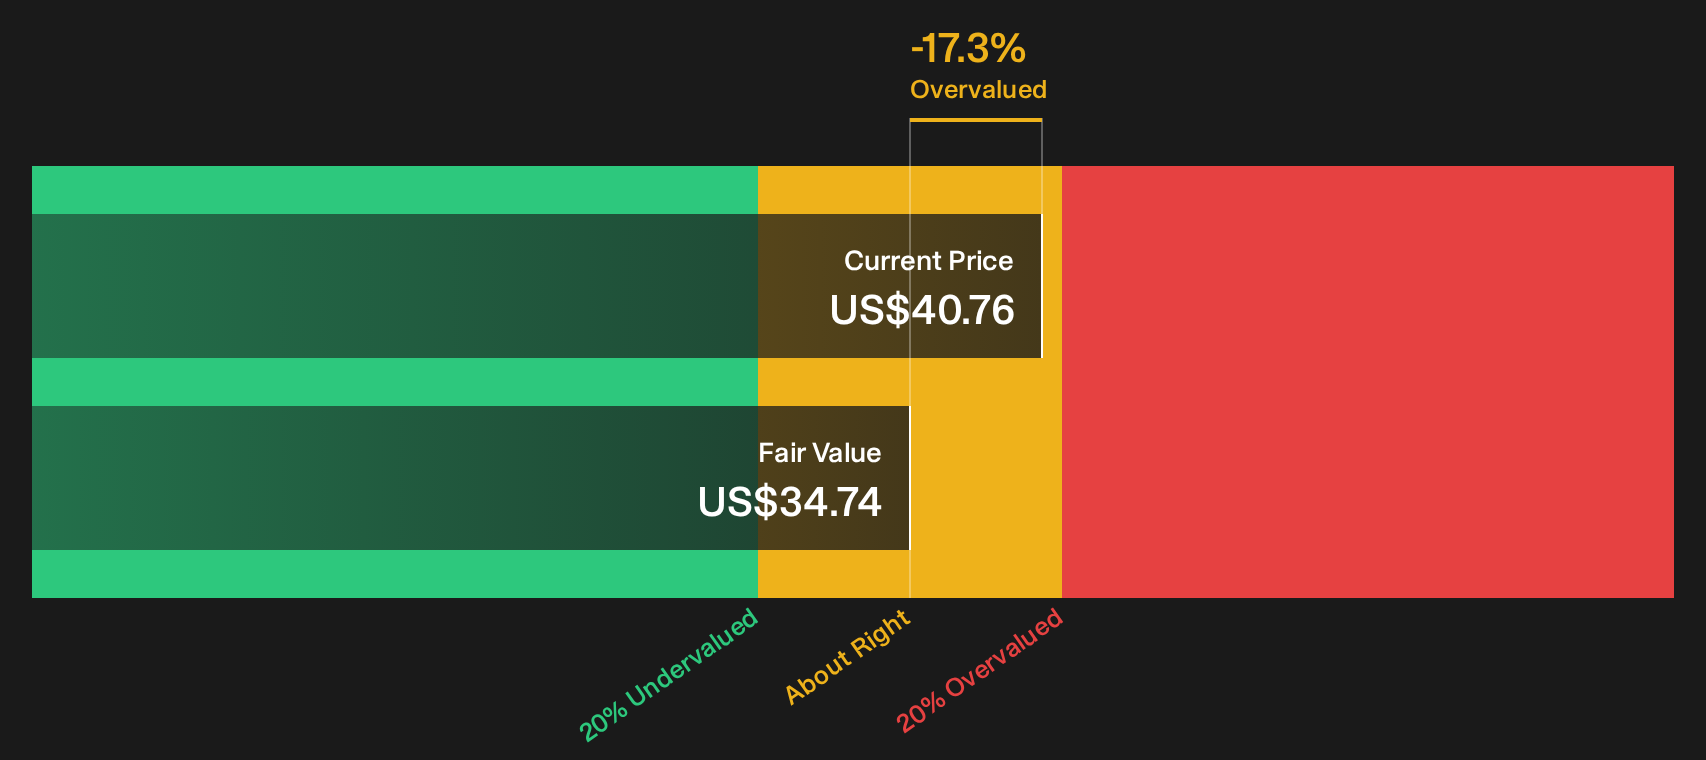
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Barrick Mining for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 4 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Barrick Mining can feel confusing, yet this is exactly when fresh data matters most. Act while the details are still current and test your own thesis by weighing the 4 key rewards and 2 important warning signs.
Hunting For More Ideas Beyond Barrick Mining?
If Barrick Mining has sharpened your focus on where to put fresh capital next, widen the net and compare it with other targeted opportunities on your radar.
- Pinpoint resilient income plays that could complement Barrick Mining by scanning a curated group of 3 dividend fortresses.
- Zero in on potential value opportunities before the crowd by reviewing a focused 4 high quality undervalued stocks.
- Strengthen portfolio quality by filtering for companies with durable finances using a list of solid balance sheet and fundamentals (7 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com