
3 Korean Chip Stocks Retail Investors Are Watching As Export Demand Strengthens
South Korea’s export engines are humming again, and the Bank of Korea’s hawkish tone is forcing investors to rethink which stories can handle tighter money. Higher rates, sticky inflation, and a stronger semiconductor recovery are pulling capital toward companies that can live with expensive funding and rising costs. This article walks through three Korean chip and hardware stocks exposed to that backdrop, and shows how the same macro shock can create both opportunity and risk.
The stocks highlighted below are just a starting sample, and the full screen on Simply Wall St surfaced 18 more Korean semiconductor and tech hardware companies with equally compelling export stories that are not covered here. If you want to go straight to the source and identify, compare, and analyze those additional opportunities before building your own shortlist, head directly into the Korean Export-Oriented Semiconductor and Tech Hardware Stocks screener.
PSK HOLDINGS (KOSDAQ:A031980)
Overview: PSK HOLDINGS produces semiconductor and flat panel display manufacturing equipment, supplying cleaning, surface treatment, and reflow tools to global chipmakers.
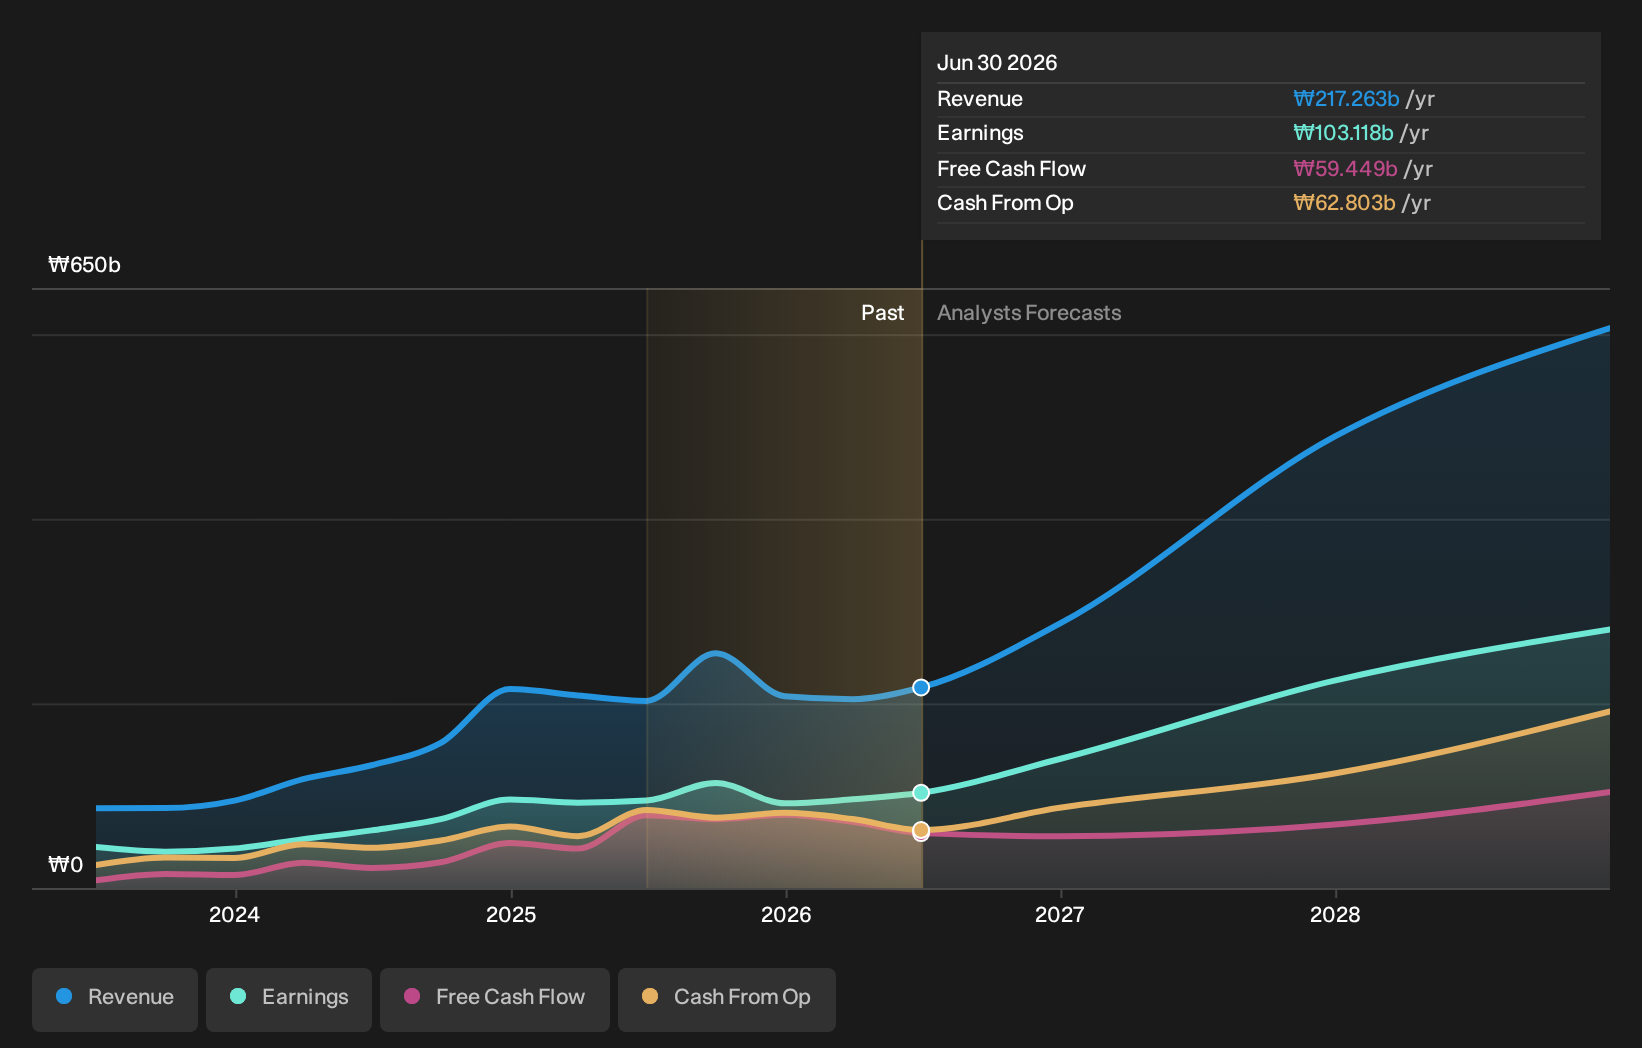
Operations: The group generates about ₩217,263 million from semiconductor manufacturing equipment, with roughly ₩161,659 million from overseas customers and ₩55,605 million from South Korea.
Market Cap: ₩3,965 billion
PSK HOLDINGS plugs directly into the export story, selling wafer and display equipment to overseas chip and panel makers while Korea leans on a semiconductor upswing. Its earnings growth expectations, forecast returns on equity, and margins may be notable in a tighter money environment where capital can focus on efficient hardware suppliers. One potential pressure on future pricing power could be important.
That pricing pressure question is exactly why it is worth scanning the 3 key rewards and 2 important warning signs (1 is major!) to see what could accelerate or stall PSK HOLDINGS from here.
TES (KOSDAQ:A095610)
Overview: TES manufactures semiconductor, display, and compound semiconductor production equipment, supplying PECVD, cleaning, LPCVD, OLED, and optoelectronics tools for global fabs.
Operations: TES generates about ₩405,469 million from semiconductor manufacturing equipment, with roughly ₩357,308 million from South Korea and ₩47,892 million from China.
Market Cap: ₩2,208.9 billion
TES fits the screener theme as a Korean equipment supplier tied to global fab buildouts and export demand in advanced chips. Its earnings are linked to tool orders rather than end consumer demand, and its premium P/E reflects strong growth forecasts at a time when tight money rewards profitable exporters more than long duration stories that depend on cheap funding. The impact will vary depending on how one unseen pressure on capital costs and order timing develops.
Those capital and order risks are exactly why it is worth reviewing the 4 key rewards and 1 important major warning sign to see what could be amplifying or masking TES’s export story.

PSK (KOSDAQ:A319660)
Overview: PSK Inc. builds specialist semiconductor processing equipment used in advanced chip production, directly tying the business to global foundry and memory investment.
Operations: PSK generates about ₩570,871 million from semiconductor processing tools, with roughly ₩160,622 million in Korea and ₩410,249 million from overseas customers.
Market Cap: ₩3,629.5 billion
PSK lines up cleanly with this export-focused semiconductor screen, with all its sales tied to chip equipment and a market value above ₩3,000 billion. Earnings and revenue are both forecast to grow faster than the broader Korean market. This may matter if one unseen pressure on future capex budgets and order timing shifts even slightly.
That capex question is exactly where PSK’s story can accelerate or stall, so scan the 2 key rewards and 1 important major warning sign to see what might be quietly driving the next leg.

Curious About What You Might Be Missing?
Fresh breakout ideas do not stay under the radar for long. Scan new momentum, catch shifts before the crowd, and position while it matters most. Act now.
- Spot cash-generating opportunities that are not just stories on a slide deck by scanning the 38 profitable AI stocks that aren't just burning cash flying under the radar for now.
- Target resilient cash flows that can help cushion portfolio swings by reviewing the 218 dividend fortresses before yields get caught dropping on renewed demand.
- Rotate into potential early-phase growth stories by checking the curated 617 high quality undiscovered gems while they still trade like overlooked ideas rather than crowded trades.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com