
NetApp (NTAP) Earnings Optimism Puts Valuation Back In Focus
Why NetApp Stock Is Back On Investor Radars
NetApp (NTAP) is moving back into focus after a session where the share price outpaced the broader market, as traders responded to optimism around the upcoming earnings release.
That 3.45% 1 day share price return comes after a powerful run, with the 30 day share price return at 9.62% and the year to date share price return at 104.01%. The 1 year total shareholder return of 88.89% and 3 year total shareholder return of 216.34% suggest momentum in NetApp has been building rather than fading as optimism around the upcoming earnings release and projected growth in earnings per share and revenue filters through sentiment.
Scan how NetApp's momentum compares with other fast moving tech opportunities by jumping into our curated list of 21 high quality undiscovered gems while this earnings story is front of mind.
NetApp looks like a robust data infrastructure business, and the recent share price surge reflects that story. The harder question is whether that strength is already fully reflected in today's valuation.
Most Popular Narrative: 3% Overvalued
NetApp last closed at $217.21, while the most widely followed narrative pegs fair value at $211.69 using an 8.63% discount rate. That gap is small, so the debate shifts from where the share price trades today to whether AI and cloud execution can keep justifying this kind of premium.
Expansion of NetApp's AI ready storage and software platform, including Novus for large AI factories and the pending acquisition of PEAK:AIO alongside recent purchases like DataPelago and JetStream, is aimed at higher value AI and cyber resilient workloads and can support higher gross profit dollars and operating margin as these offerings are commercialized.
See why 54 investors see NetApp as 3% overvalued.
Result: Fair Value of $211.69 (OVERVALUED)
Still, rising memory and component costs, along with a near doubling of inventory in Q1 FY27, could pressure NetApp margins if demand absorbs that stock more slowly.
Find out about the key risks to this NetApp narrative.
Another View: NetApp Through A Cash Flow Lens
The fair value narrative built around earnings multiples says NetApp trades a touch rich. Our DCF model tells a different story. On that framework, NTAP at $217.21 screens about 11.1% below an estimated $244.23 future cash flow value, which frames recent strength as less of a pure sentiment move and more of a cash flow debate. Where do you place more weight: on headline P/E or on the stream of cash the business is modeled to produce?
For readers who want to see how this cash flow view is constructed in detail, Look into how the SWS DCF model arrives at its fair value.
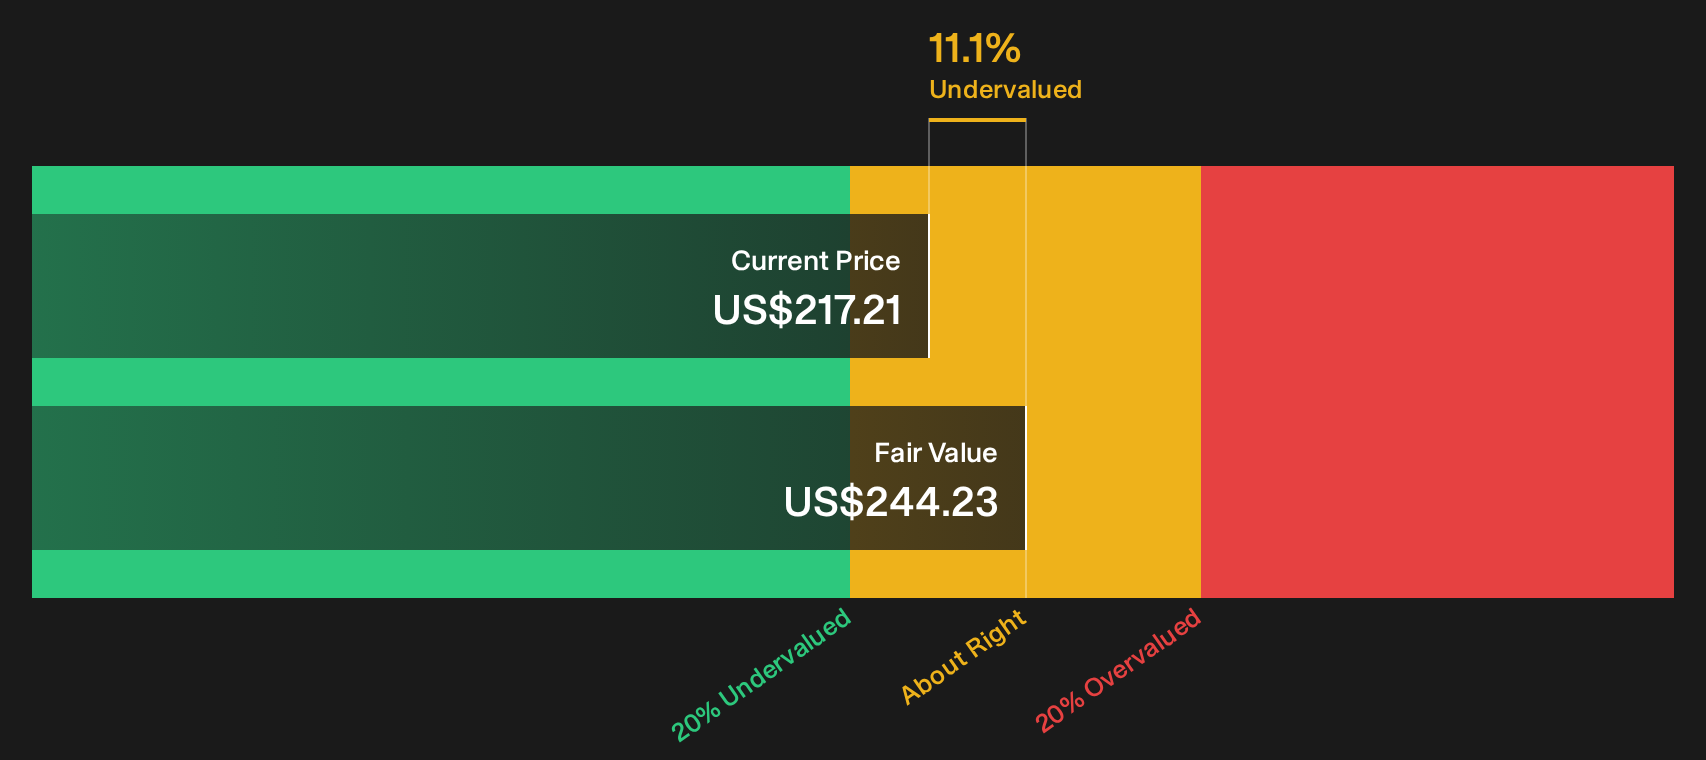
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out NetApp for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Plenty of optimism runs through this NetApp story, although the data also flags some real concerns that deserve attention. Act quickly, review the numbers yourself, weigh both sides of the debate, and then drill into the 3 key rewards and 1 important warning sign
Hunting For Your Next Idea Beyond NetApp?
Do not leave your research at NetApp when you can quickly scan other opportunities that fit different goals, risk levels, and income needs.
- Target resilient compounding by reviewing a 31 resilient stocks with low risk scores that highlights businesses with lower risk scores for steadier potential outcomes.
- Boost potential future income by using a 7 dividend fortresses that focuses on companies offering 5%+ yields with an emphasis on stability.
- Pursue quality at a discount by checking a 33 high quality undervalued stocks that blends strong cash flows with solid balance sheets.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com