
International Seaways (INSW) Stock May Still Be A Bargain Despite A $370 Million Fleet Deal
International Seaways has been on a powerful multi year run, and the stock’s sharp move higher has investors asking whether today’s share price can still be explained by the company’s earnings power. With that question on the table, the focus now shifts away from the share chart and onto what the profit stream really supports.
- Over the past 5 years, International Seaways has delivered a very large total return, which puts real pressure on the current earnings base to justify where the stock trades now.
- The planned US$370 million acquisition of Bruton Limited, which adds four Very Large Crude Carriers to an already sizeable fleet, may support future earnings capacity but also reshapes how investors think about capital allocation and timing of cash flows.
- The analysts covering International Seaways have run their own numbers. See what analysts think International Seaways's shares could be worth.
For investors, the debate is whether International Seaways’ current price is adequately supported by the level and quality of the earnings it generates today.
If you want to ask the same earnings question you are asking of International Seaways across a wider set of companies, start with 33 high quality undervalued stocks.
Is International Seaways Still Cheap on Earnings?
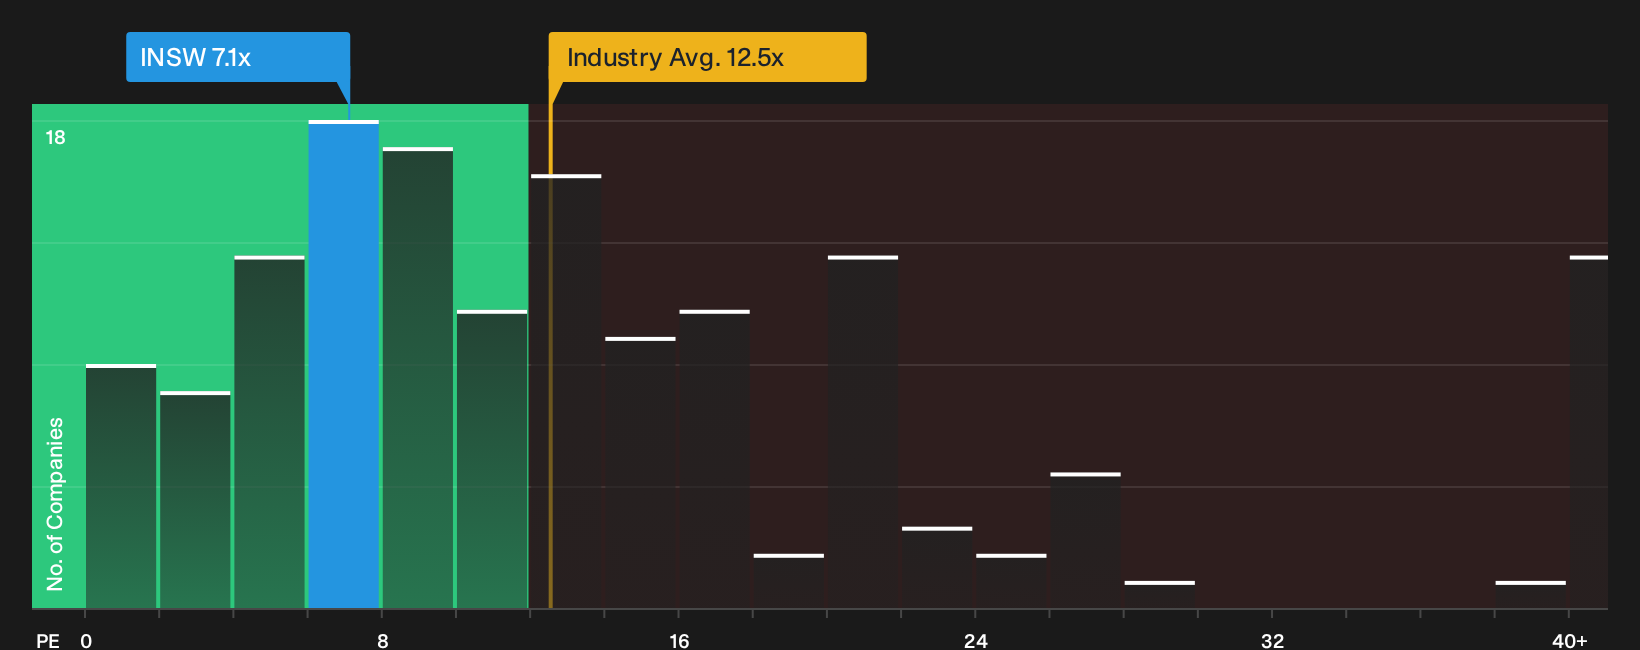
The P/E ratio suits International Seaways because earnings are a key driver of how investors judge shipping companies. On this metric, the stock trades on a P/E of 7.1x, compared with an Oil and Gas industry average of about 12.5x and a peer group near 11.3x, so the earnings stream is priced at a lower level than many comparable businesses.
Because the current multiple sits below what a tailored fair P/E would suggest for International Seaways, the shares screen as undervalued on this model. The planned US$370 million Bruton acquisition, with its additional Very Large Crude Carriers, has lifted attention on the ticker. However, the earnings multiple still reflects a discount relative to those benchmarks. For a holder, the key judgement is whether that gap reflects conservatism about shipping cycles or a genuine mispricing that could close over time. Explore the numbers behind International Seaways's P/E valuation.
The International Seaways Narrative: What Would Justify Today's Price?
Narratives pick up where the P/E puzzle leaves off for International Seaways, by outlining what kind of future growth, profitability and earning power would need to occur for the stock to be worth significantly more or less than it is today on Simply Wall St's Community page. Instead of providing a single valuation output, each scenario explains the assumptions behind its fair value so you can track those inputs against actual results as they are reported.
Community valuation views on International Seaways are split between investors who see limited upside and those who think the recent run already bakes in rich expectations.
Bull case: 7% undervalued
"International Seaways is adding four LR1 newbuildings scheduled to deliver in the second half of 2028, on top of six sister vessels ordered earlier…"
Discover why this Narrative puts International Seaways at 7% undervalued.
Bear case: 26% overvalued
"The surge in International Seaways’ share price of roughly 73 to 88% year to date and more than 135% over one year, combined with reports that the stock may trade 40 to 80% above some estimates of intrinsic value and over US$39 million of insider selling without corresponding insider buying…"
Explore why this Narrative puts International Seaways at 26% overvalued.
International Seaways: why the current share price is only half the story
Valuation frames where International Seaways trades today, but analyst projections a few years out give you a separate reference point to compare with that snapshot and judge how expectations line up. Explore where analysts expect International Seaways to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com