
UK's Top 3 Growth Stocks With Strong Insider Ownership
In recent times, the UK market has faced challenges, with the FTSE 100 index experiencing a downturn due to weak trade data from China and its impact on global economic recovery. Amid these fluctuations, investors often seek growth companies with strong insider ownership as they can indicate confidence in the company's potential and resilience in uncertain markets.
Top 10 Growth Companies With High Insider Ownership In The United Kingdom
| Name | Insider Ownership | Earnings Growth |
| TEAM (AIM:TEAM) | 32% | 85.3% |
| Quantum Base Holdings (AIM:QUBE) | 31.8% | 111.8% |
| Mortgage Advice Bureau (Holdings) (LSE:MAB1) | 18.4% | 22.4% |
| Hochschild Mining (LSE:HOC) | 38.3% | 21.4% |
| Gulf Keystone Petroleum (LSE:GKP) | 12.5% | 21.1% |
| Energean (LSE:ENOG) | 19.3% | 32.8% |
| EARNZ (AIM:EARN) | 10.1% | 90.6% |
| Crimson Tide (AIM:TIDE) | 33.5% | 119.1% |
| Built Cybernetics (AIM:BUC) | 22.6% | 122.1% |
| Afentra (AIM:AET) | 32.4% | 60.6% |
Let's dive into some prime choices out of the screener.
Optima Health (AIM:OPT)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Optima Health plc offers occupational health and wellbeing services to both public and private sectors in the UK and Republic of Ireland, with a market cap of £264.87 million.
Operations: The company's revenue segment is primarily derived from the provision of occupational health and wellbeing services, totaling £120.64 million.
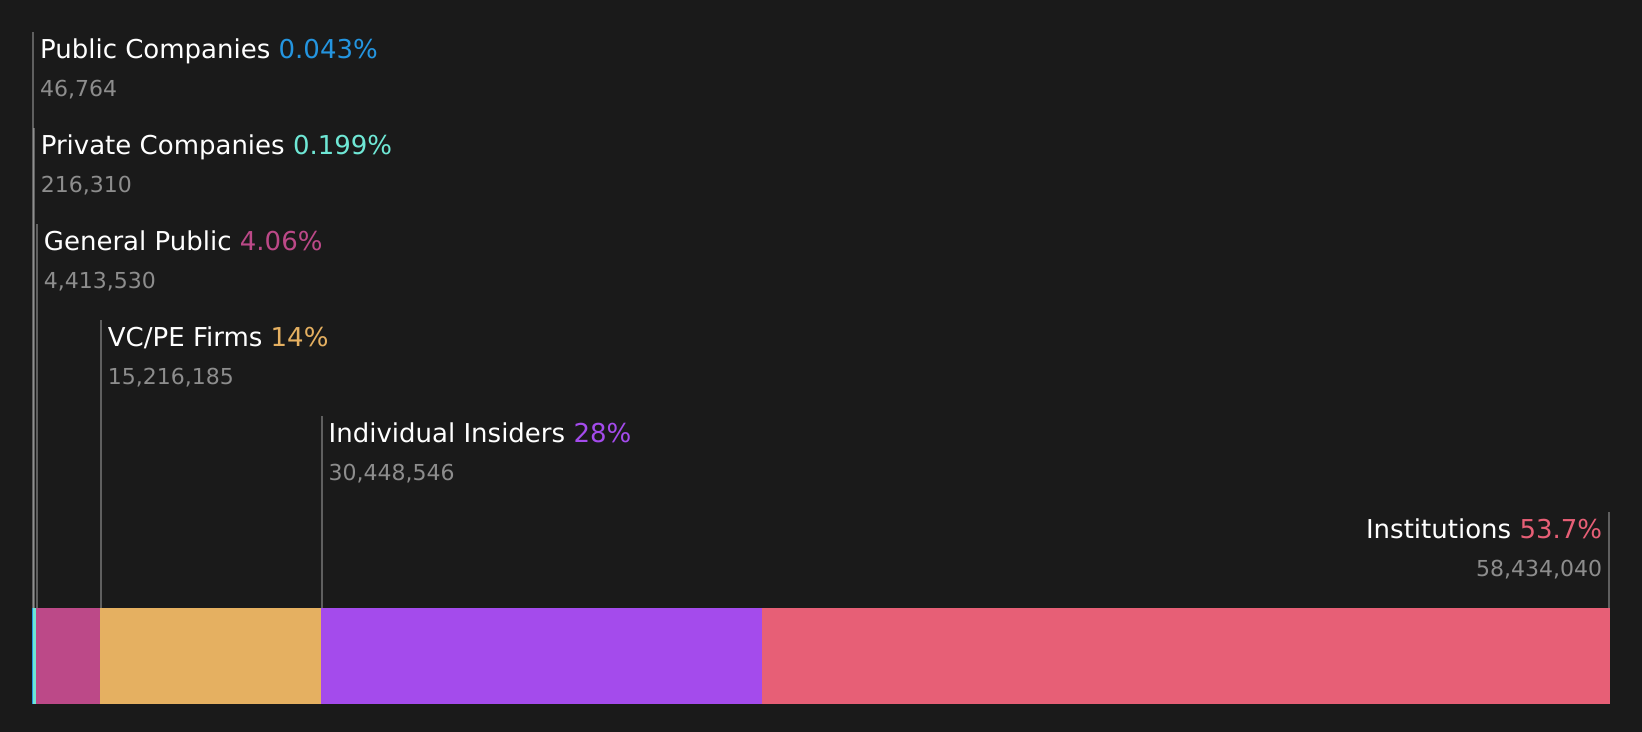
Insider Ownership: 27.8%
Optima Health is positioned for substantial growth, with earnings projected to rise significantly at 68.8% annually, outpacing the UK market. Despite trading at 62.8% below estimated fair value, past shareholder dilution and low forecasted return on equity (10%) are concerns. The company seeks strategic M&A to leverage its UK platform for economies of scale and expansion into complementary areas, reflecting a disciplined capital allocation strategy amid recent revenue growth from £105.05 million to £120.64 million.
- Navigate through the intricacies of Optima Health with our comprehensive analyst estimates report here.
- Our expertly prepared valuation report Optima Health implies its share price may be lower than expected.
Gulf Keystone Petroleum (LSE:GKP)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Gulf Keystone Petroleum Limited explores, evaluates, develops, and produces oil and gas in the Kurdistan Region of Iraq with a market cap of £455.54 million.
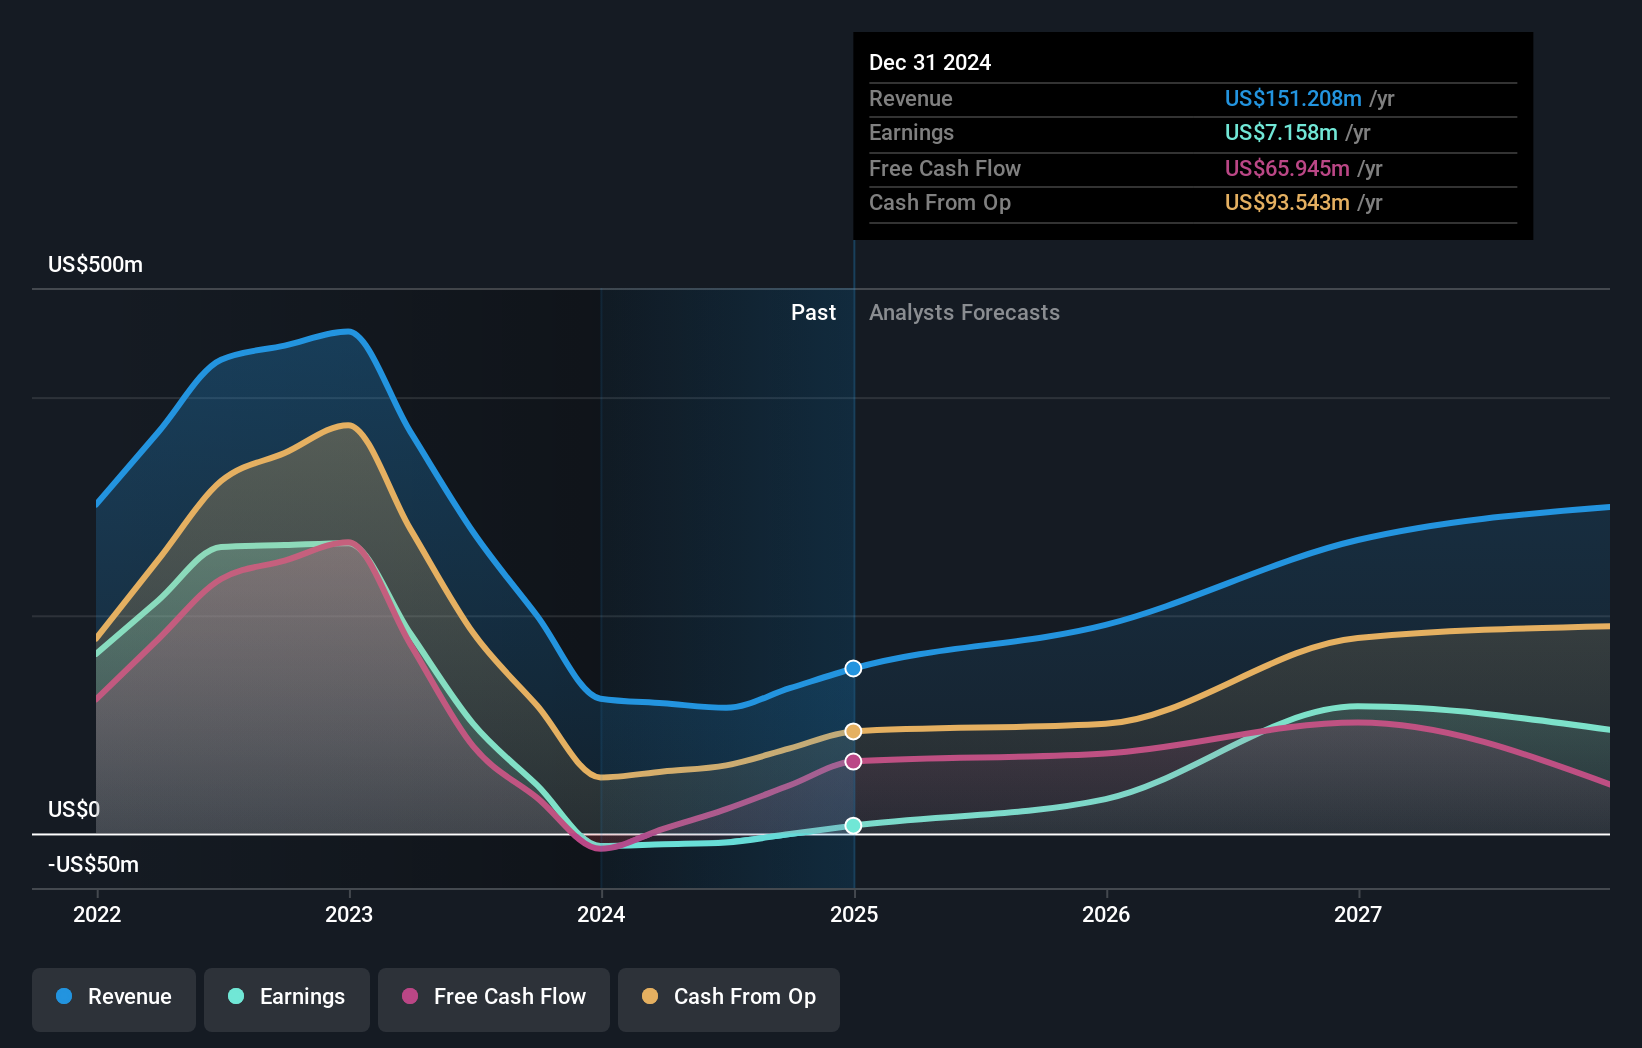
Operations: The company's revenue segment consists solely of the exploration and production of oil and gas, generating $192.76 million.
Insider Ownership: 12.5%
Gulf Keystone Petroleum is poised for growth with projected revenue and earnings increases of 21.9% and 21.1% per year, respectively, surpassing UK market averages. Despite trading at 83.8% below estimated fair value, concerns include a low forecasted return on equity (19.2%) and unsustainable dividends (3.69%). Recent developments include a reverse merger with ShaMaran Petroleum valued at NOK 6.3 billion, aiming to consolidate listings on Euronext Oslo Børs by mid-2027 for enhanced liquidity.
- Dive into the specifics of Gulf Keystone Petroleum here with our thorough growth forecast report.
- The analysis detailed in our Gulf Keystone Petroleum valuation report hints at an deflated share price compared to its estimated value.
Saga (LSE:SAGA)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Saga plc operates in the United Kingdom, offering package and cruise holidays, general insurance, and personal finance products and services, with a market cap of £1.19 billion.
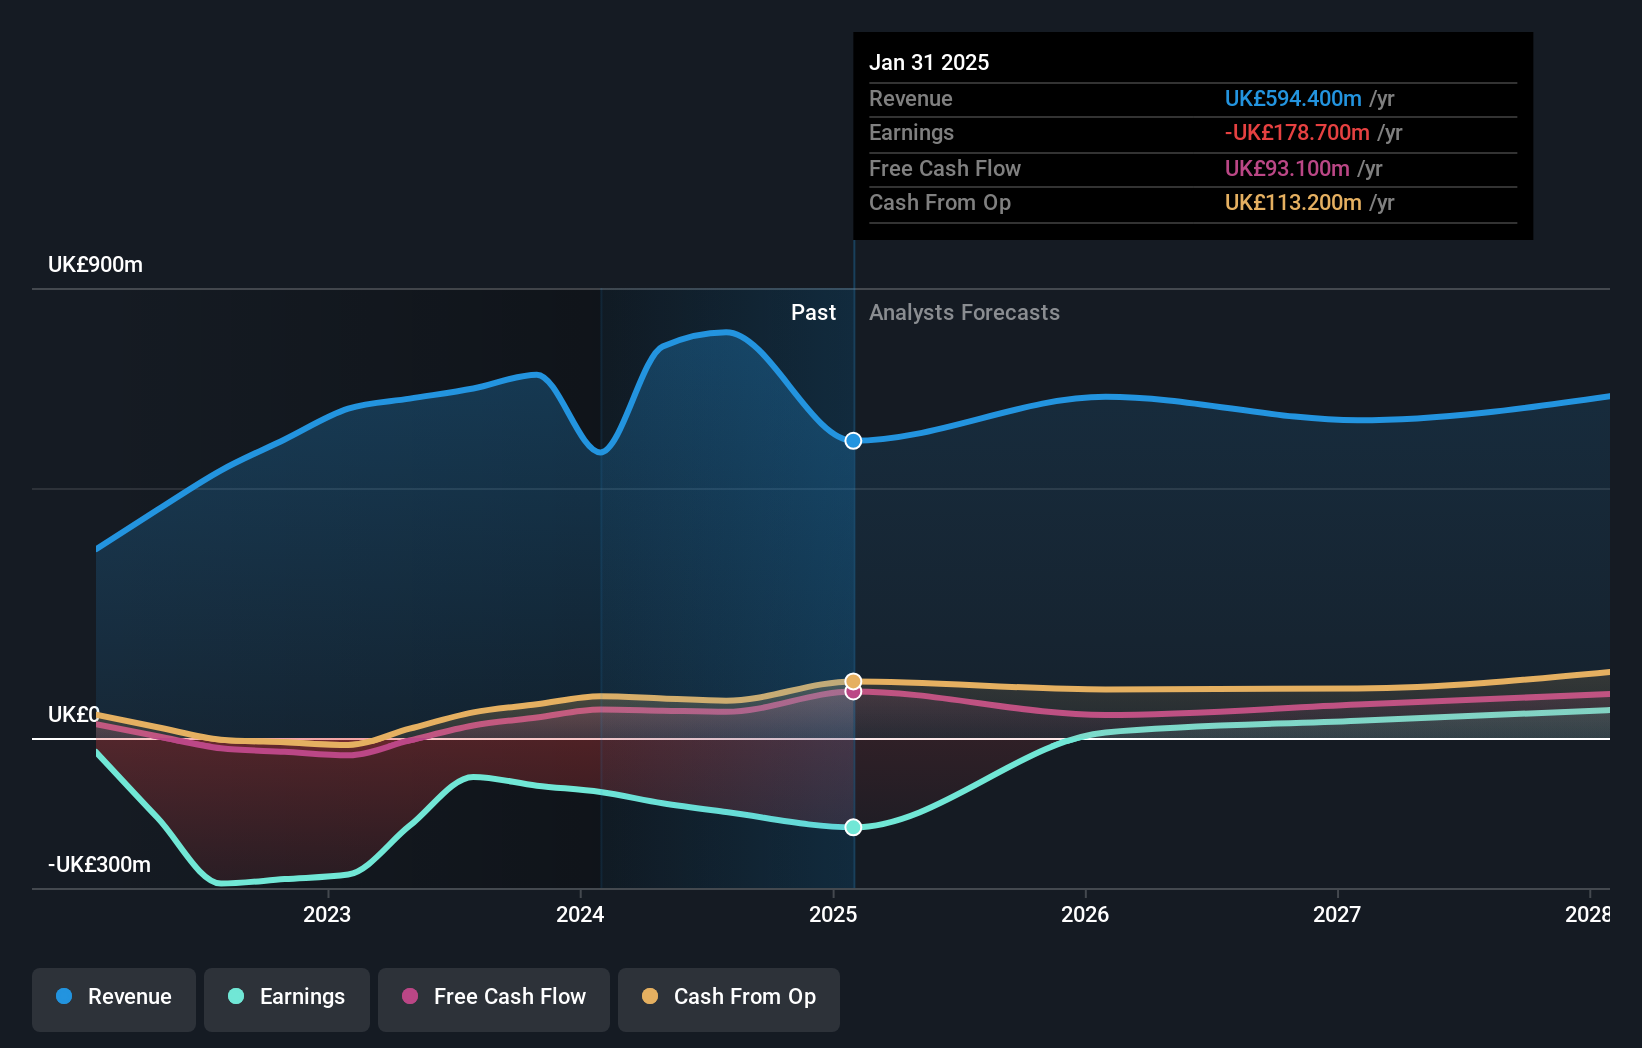
Operations: Saga's revenue is derived from several segments, including £143.60 million from Insurance Broking, £193.70 million from Travel - Holidays, £282.20 million from Travel - Ocean Cruise, and £62.40 million from Travel - River Cruise.
Insider Ownership: 36.5%
Saga plc has demonstrated a turnaround, reporting a net income of £29.4 million for H1 2027 compared to a loss the previous year. Despite high share price volatility, its earnings are forecasted to grow significantly at 40% annually, outpacing the UK market average. Revenue growth is expected at 5.6% per year, slightly above market rates. Recent board additions with consumer-focused expertise may bolster strategic direction and governance as Saga eyes future profitability improvements.
- Click here to discover the nuances of Saga with our detailed analytical future growth report.
- Our valuation report here indicates Saga may be overvalued.
Seize The Opportunity
- Get an in-depth perspective on all 66 Fast Growing UK Companies With High Insider Ownership by using our screener here.
- Want To Explore Some Alternatives? Uncover the next big thing with financially sound penny stocks that balance risk and reward.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com