
Mesoblast (ASX:MSB) Shares Climbed, What Is Driving Fresh Attention?
Mesoblast (ASX:MSB) is back in focus after the FDA approved its cell therapy Ryoncil. Broad commercial and Medicaid coverage is sharpening attention on how this could influence the group’s future revenue mix.
Recent trading tells a mixed story. The A$1.86 Mesoblast share price has climbed 5.68% on a 1 day basis, yet the 30 day share price return is down 12.68% and the year to date share price return has fallen 32.85%. At the same time, the 3 year total shareholder return of over 4x signals that longer term investors have still seen very large gains, despite the 31.11% decline in total shareholder return over the past year.
Scan beyond Mesoblast and line up other potential FDA or late-stage biotech catalysts using the curated 7 healthcare AI stocks that could be next in line for attention.
Mesoblast now trades at A$1.86 while analyst and intrinsic estimates cluster closer to double that level. Does the recent FDA win justify that gap, or are expectations already crowded into the story?
Most Popular Narrative: 48% Undervalued
Mesoblast’s most followed valuation story pegs fair value around A$3.59, which is roughly double the recent A$1.86 share price. That gap rests on a view that the current pipeline and product traction eventually translate into far higher earnings power than today’s loss making profile suggests.
The heart failure program for rexlemestrocel L, with RMAT designation and FDA feedback that existing trial data could support an accelerated approval filing alongside a planned confirmatory study, gives Mesoblast a potential entry into a very large cardiovascular market. Outcomes would primarily influence long term revenue scale and the path to sustainable earnings.
See why 14 investors see Mesoblast as 48% undervalued.
Result: Fair Value of A$3.59 (UNDERVALUED)
Still, Mesoblast’s story hangs on costly trials across multiple indications, along with an early Ryoncil rollout that currently requires far more cash out than product revenue.
Find out about the key risks to this Mesoblast narrative.
Another View: Mesoblast Through The Sales Multiple Lens
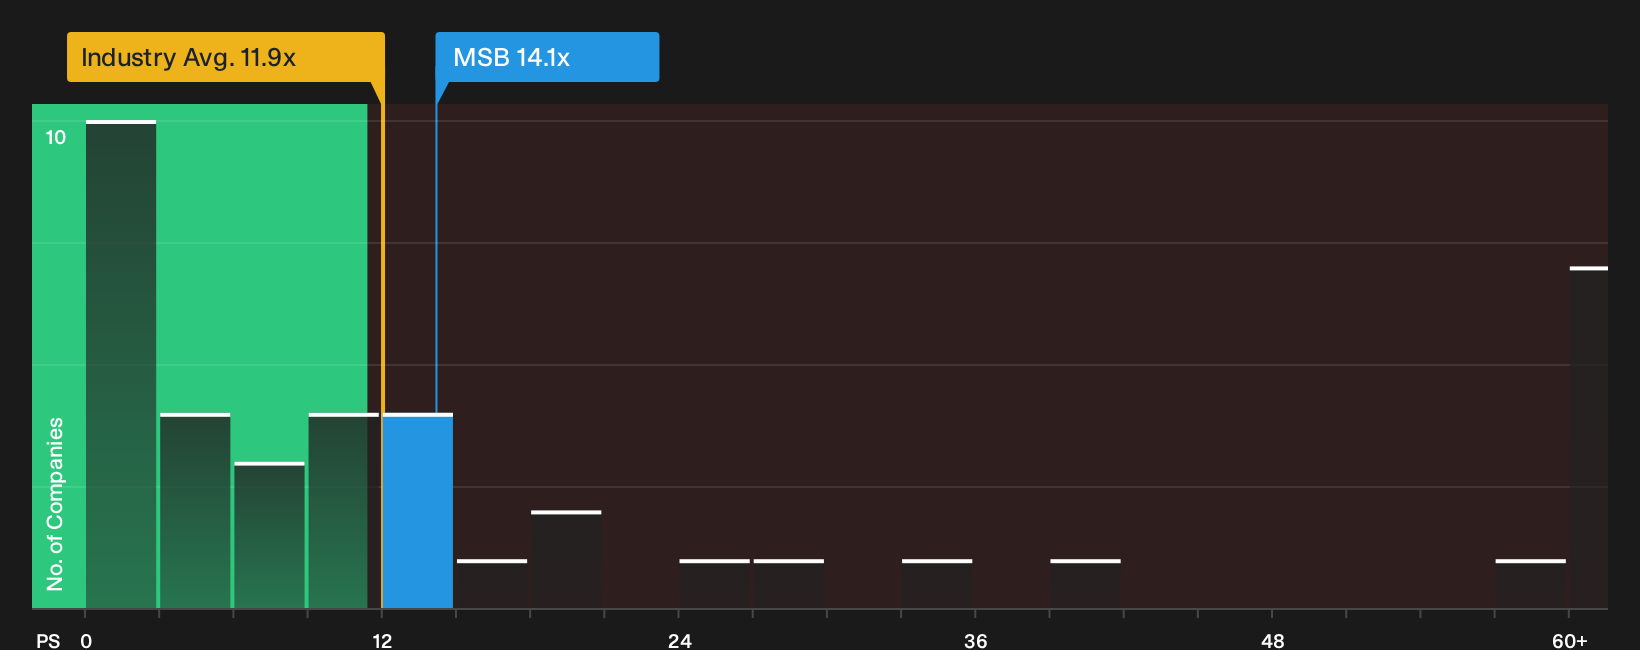
The story shifts once you swap the fair value and DCF style thinking for a simple sales multiple. Mesoblast trades on a P/S of 14.1x while the Australian biotech group sits closer to 12.5x and the fair ratio comes in at 9.9x. That gap points to richer expectations baked into the current A$1.86 price. Could that premium narrow if sentiment cools or rivals catch up?
For a closer look at how this pricing stacks up against peers and the market, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this Mesoblast story feels finely balanced between promise and risk, move fast on the homework and shape your own view using the 3 key rewards.
Looking for more investment ideas beyond Mesoblast?
Mesoblast might be front of mind today, yet your next strong opportunity could sit in a very different corner of the market, waiting for fresh attention.
- Chase potential mispricing before the crowd spots it by scanning a 4 high quality undervalued stocks that couples quality fundamentals with discounted valuations.
- Strengthen your income stream by reviewing a 5 dividend fortresses that focuses on higher yielding companies with more robust payout profiles.
- Dial down portfolio stress by working through a 6 resilient stocks with low risk scores built around businesses with more resilient financial and risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com