
Home Depot (HD) Could Be 23% Undervalued As Earnings Come Into Focus
Why Home Depot Stock Is Back In Focus
Home Depot (HD) has jumped back onto traders' screens after climbing 1.67% and beating the S&P 500, just weeks before its November 17 earnings update, which has expectations for improved EPS.
Under the surface, Home Depot has seen a sharp 6.3% 7 day share price return and a 5.7% 30 day gain, even though the year to date share price return is down 9.2% and the 1 year total shareholder return has declined 17.0%. This hints that recent momentum is building as traders reassess earnings potential and risk around higher mortgage rates and delayed remodeling projects.
Scan how traders are repositioning around housing and remodeling by comparing Home Depot with a hand picked group of 33 high quality undervalued stocks.
Home Depot now sits between two stories. Recent gains could be a simple mood swing after a rough year, or a cleaner read on what this retailer is actually worth.
Most Popular Narrative: 18% Undervalued
Against Home Depot's last close at $314.14, the most followed narrative pegs fair value at $385. That gap frames the recent rebound as more than just a short term bounce and puts the focus on how the business earns its returns over time.
Home Depot’s competitive advantages, scale, brand, real estate portfolio, supply chain, knowledgeable associates, and deep Pro relationships position it to capture a larger share of higher-ticket, complex remodeling and construction work. Pros already generate stronger average tickets and more consistent demand than pure DIY shoppers. Integrating specialty distribution with the retail footprint, digital tools (such as AI-powered material list builders, Magic Apron, and Project Planning), Express Delivery, and online capabilities (recent double-digit online comps) aims to create stickier relationships and higher lifetime value.
See why 10 investors see Home Depot as 18% undervalued.
Result: Fair Value of $385 (UNDERVALUED)
Still, higher mortgage rates and weaker big ticket transactions could derail the housing rebound that supports the Home Depot Pro-focused story.
Find out about the key risks to this Home Depot narrative.
Another View On Home Depot’s Valuation
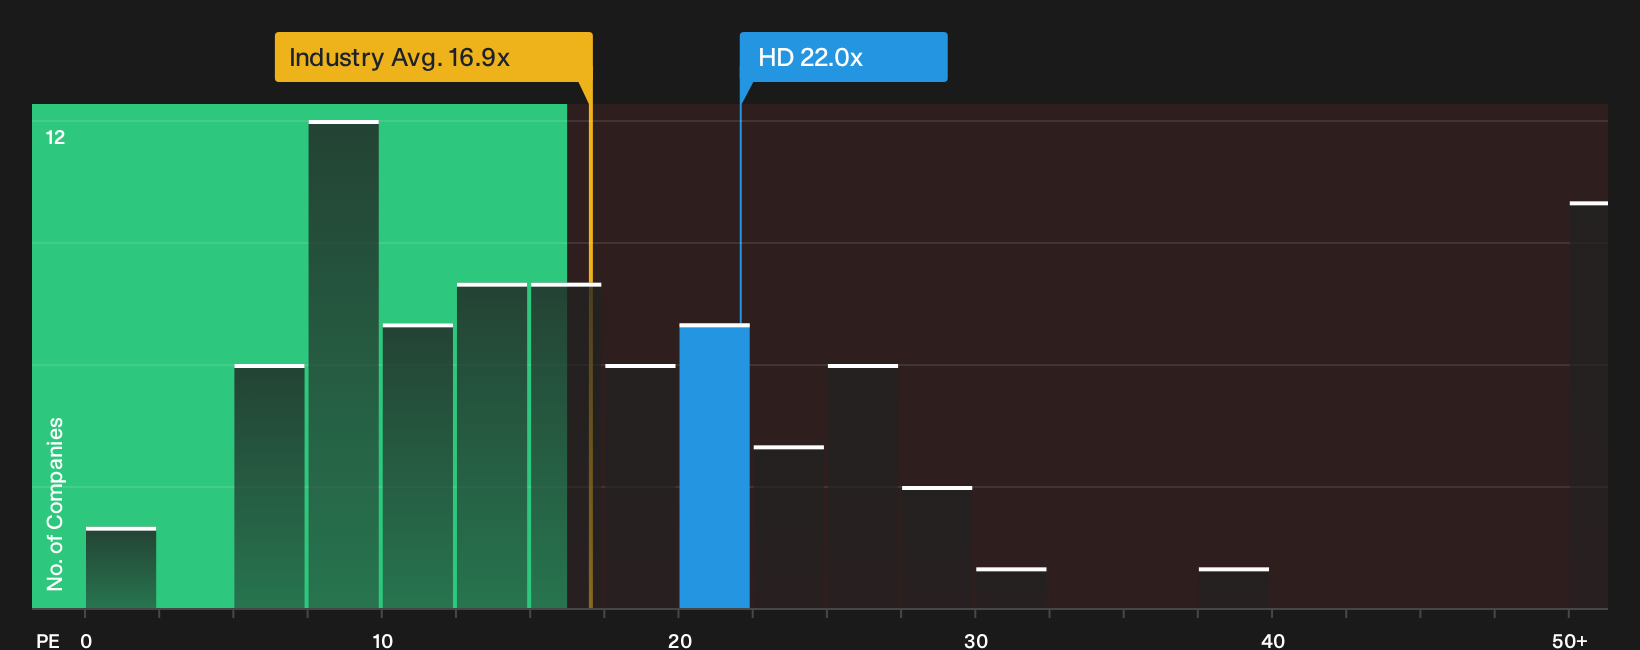
That $385 fair value from the community sits next to a simpler message from the market. Home Depot trades on a P/E of 22x compared with 16.9x for the US Specialty Retail group and a peer average of 21.8x, while the fair ratio sits at 21.7x.
That premium is not huge in absolute terms, yet it nudges HD into the “priced slightly rich” camp and trims the margin for error if earnings or housing data disappoint. The question for investors is whether a small valuation cushion is enough given the recent share price rebound.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Home Depot is clearly split right now, and that tension is exactly where thoughtful investors can move first and test their own thesis. Before deciding how to treat the recent rebound, weigh the 3 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond Home Depot?
If you only stop at Home Depot, you miss a wider field of opportunities. Put a few minutes into comparing alternatives and your future self may thank you.
- Target steady cash generators and filter for resilient balance sheets and consistent fundamentals using our list of solid balance sheet and fundamentals (25 results).
- Hunt for mispriced opportunities by scanning companies with strong business quality that still trade below fair value through the 33 high quality undervalued stocks.
- Spot lesser known potential and track under-the-radar businesses with healthy metrics using the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com