
Thermo Fisher (TMO) Q3 Earnings Ride Margin Expansion And Raised Guidance
Thermo Fisher Scientific walked into this Q3 2026 report with a premium reputation in life science tools and a stock that had already climbed about 21% over the past three months. The share price barely flinched on the day after results, up just under 1%. The real story is sharper than that move suggests. Management posted about US$12.1b in quarterly revenue and lifted full year guidance, while adjusted operating income grew faster than sales, pointing to margin expansion as the key surprise. For a business often treated as a steady compounder, profitability did the talking this quarter.
Love Thermo Fisher Scientific's margin expansion but want a wider set of high quality compounders with strong balance sheets on your radar too? Take a look at our list of solid balance sheet and fundamentals stocks (25 results)
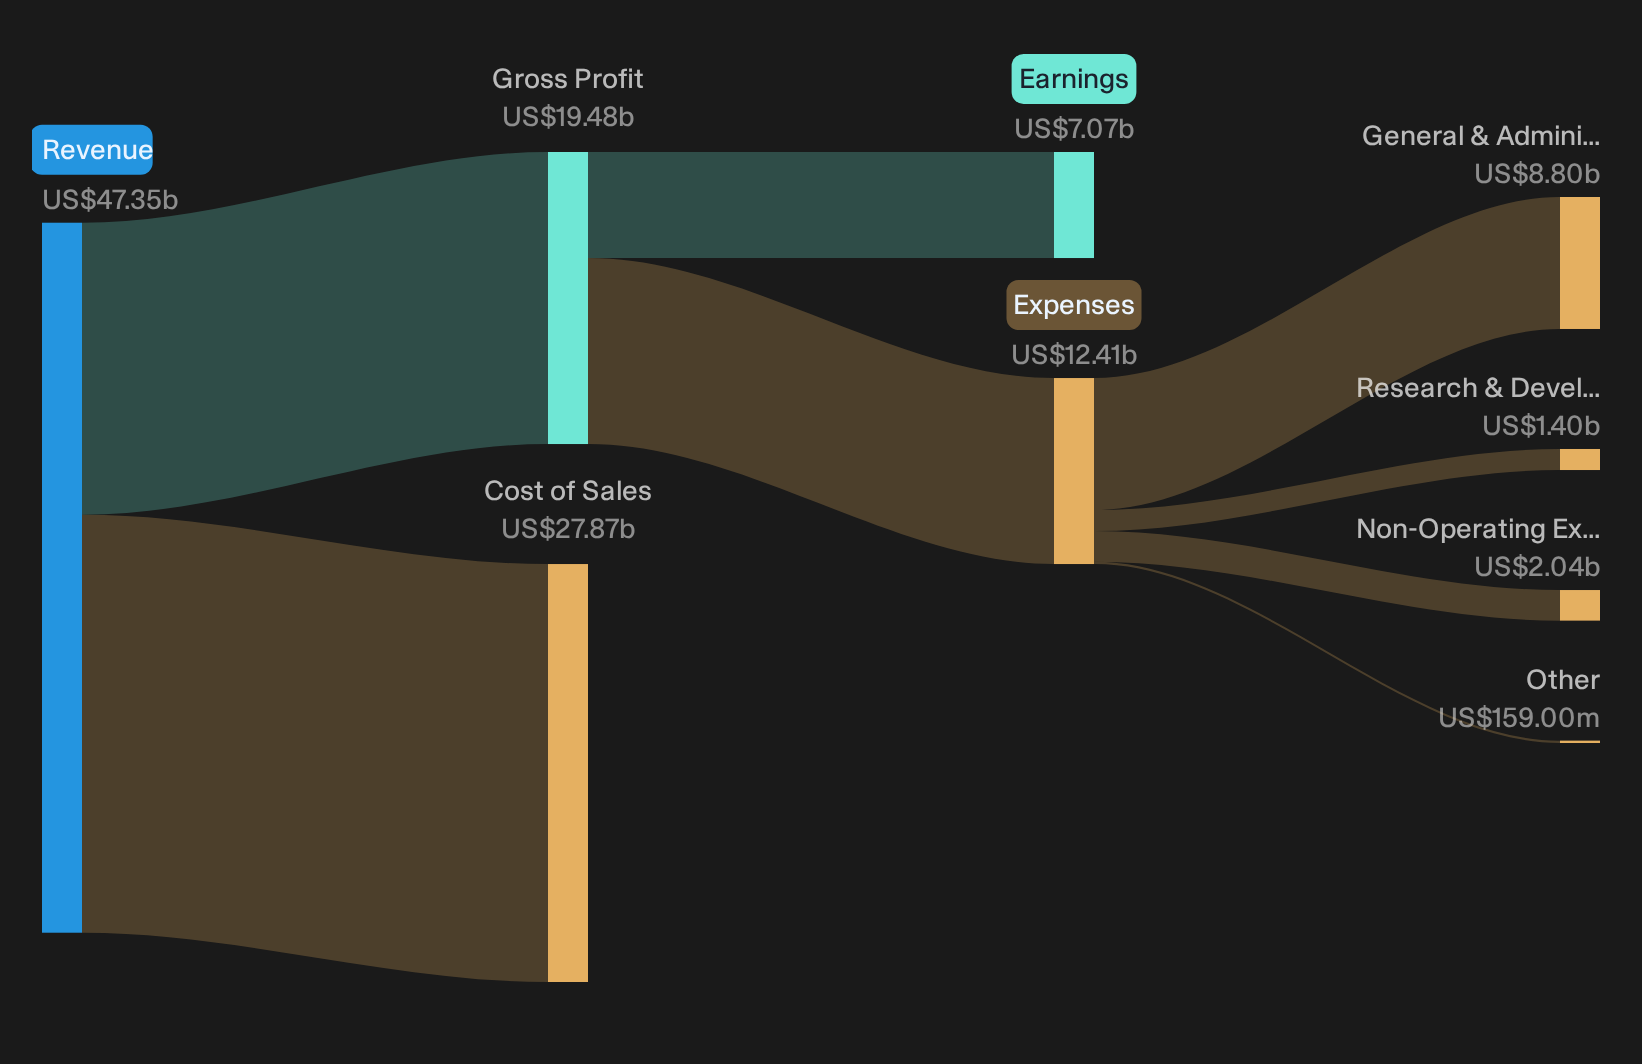
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$12,137m vs. US$11,122m (up 9%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$1,721m vs. US$1,616m (up 6.5%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$4.65 vs. US$4.28 (up 8.8%)
- Adjusted Operating Margin (Q3 2026 vs. Q3 2025): 24.5% vs. 23.3% (expanded 120 bps)
Ask Charlie what Thermo Fisher isn’t saying about its AI push.
Thermo Fisher Bull Case: Services Mix Starts To Show
Thermo Fisher Scientific bulls argue that data heavy services and digital workflows can turn today’s product reach into richer recurring earnings.
"The main thing that has to go right is that Thermo Fisher Scientific continues to convert its recent acquisitions, AI and digital initiatives, and reshoring driven CDMO contracts into durable organic growth while keeping margins resilient."
Q3 gives that idea some traction. Lab Products & Biopharma Services organic growth of 10% and solid pharma services demand show acquisition heavy clinical offerings pulling their weight. Group organic revenue at 6% and adjusted operating margin up 120 bps indicate early evidence that higher value services and AI supported workflows are lifting profitability rather than just adding volume.
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all.
Thermo Fisher Bear Case: Divestiture Drag Still Untested
The cautious view claims Thermo Fisher could struggle to grow earnings once the microbiology unit is out and slower academic and government budgets bite.
"Some analysts with a bearish view expect Thermo Fisher Scientific's margins and global growth to remain constrained, as the microbiology divestiture reduces earnings and academic and government spending stays muted."
Q3 shows margin expansion of 120 bps, 15% adjusted EPS growth and raised full year guidance, so constrained profitability is not visible yet. Academic and government demand is flat, matching the concern, yet high single digit pharma and industrial growth plus 10% organic in Lab Products & Biopharma Services more than offset it. Crucially, the first full post sale EPS impact is still ahead, so the full drag remains unproven in reported numbers.
Hunt For Quiet Dislocations Now
Thermo Fisher Scientific just showed how a single quarter can shift the earnings story without significantly changing the share price. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 21% below our estimate - equips dense AI data centres with liquid cooling that reduces heat constraints and water usage at scale.
- Company 2 - 40% below our estimate - uses heavier near term spending on AI, payments and branches to pursue higher fee income and operating leverage.
- Company 3 - 33% below our estimate - builds a financial super app that shifts users toward secured lending, payments and commerce within one tightly integrated platform.
Three companies from the same screener. Open the full list of 33 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com