
Is TDK (TSE:6762) Undervalued As AI Infrastructure Optimism Lifts Chipmakers?
Asian chipmakers moved higher after Super Micro Computer issued a stronger than expected preliminary revenue forecast, and TDK (TSE:6762) joined the advance as investors revisited expectations around demand for AI infrastructure hardware.
That AI tailwind is hitting a stock that already has momentum behind it. TDK’s 1 day share price return of 2.42% to ¥2,902.5 follows a 29% year to date share price gain and a 5 year total shareholder return of 286.77%. However, the 7 day share price return is down 7.92% and the 90 day share price return is down 6.85%, which suggests short term sentiment has cooled despite the stronger longer term performance.
Scan other AI infrastructure plays that are moving on similar momentum with the curated 55 AI infrastructure stocks.
TDK now sits between strong multi year returns and a recent pullback that cooled the chart. Does it make more sense to lean into this AI bump, or to wait for a cleaner entry based on valuation instead?
Most Popular Narrative: 31% Undervalued
TDK last closed at ¥2,902.5, while the most followed narrative anchors fair value at ¥4,190.63 using a 7.11% discount rate. That gap matters because the thesis leans heavily on how AI focused projects could reshape the mix of what TDK sells and how consistently it earns from those products.
The expansion of the SensEI edge AI platform, including the evolution into predictive and prescriptive maintenance with an AWS partnership and the launch of the edgeRX Pro module for harsh industrial environments, targets a market expected to grow around 35% and is directed at lifting recurring solution revenue and improving earnings quality.
See why 3 investors see TDK as 31% undervalued.
Result: Fair Value of ¥4,190.63 (UNDERVALUED)
Still, the narrative can crack if new US tariffs pressure end demand in key export markets, or if prolonged softness in automotive and industrial orders lingers.
Find out about the key risks to this TDK narrative.
Another View: TDK Looks Full On Cash Flows
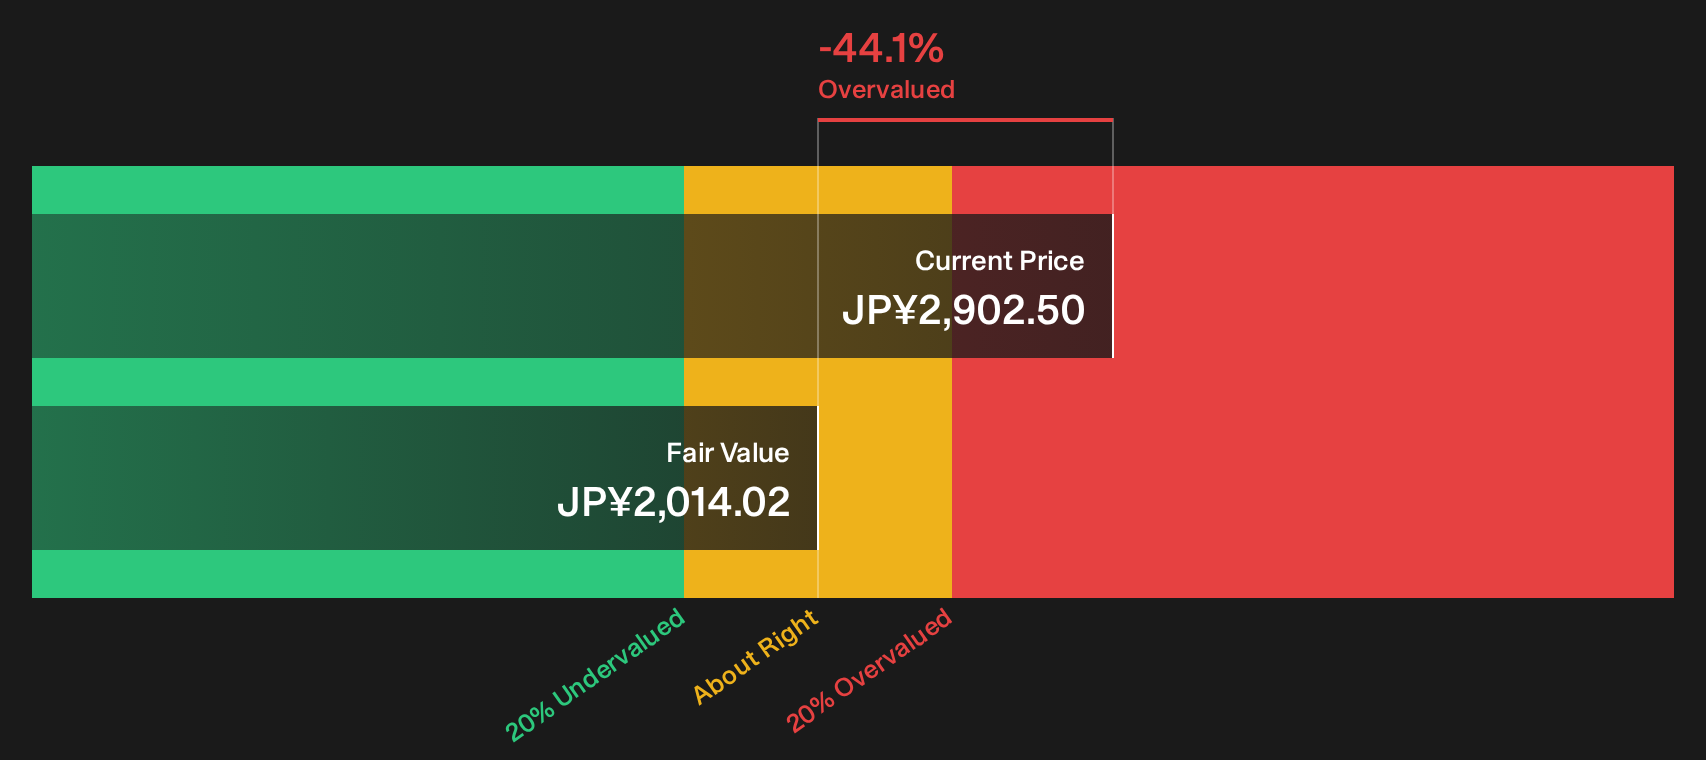
The earlier narrative leans on a fair value of ¥4,190.63, yet our DCF model tells a less generous story. On a future cash flow basis, TDK screens as overvalued, with the current ¥2,902.5 price sitting above an estimated ¥2,014.02 fair value. Which lens do you trust more for sizing your risk?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment on TDK is split, with strong long term returns on one side and valuation pushback on the other. Move quickly and pressure test the assumptions that matter most to you by weighing up the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond TDK?
If TDK has you rethinking how AI and valuation fit together, do not stop there. Broader context from other opportunities can sharpen every decision you make.
- Target potential mispricings by scanning a curated 13 high quality undervalued stocks that filters for quality first, then price.
- Prioritise resilience by reviewing a 22 resilient stocks with low risk scores that screens for companies with more measured risk profiles.
- Hunt for fresh opportunities by checking a 73 high quality undiscovered gems that highlights under-the-radar businesses with solid fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com