
AddLife (OM:ALIF B) Q3 Results Sharpen Margin And Cash Flow Case
AddLife entered its Q3 2026 report riding a strong run, with the share price at SEK190.6 after a solid three month climb. The stock carries a premium style multiple on a trailing P/E of 36.1x, yet still sits below both the wider life sciences group and direct peers, which matters when sentiment is already warm.
The fresh quarter delivered what long term backers wanted most. Adjusted EBITA grew faster than sales and the adjusted EBITA margin reached 11.5%, backed by cash conversion above 100%. The price reaction now needs to catch up to the reality of improving profitability and tighter cash discipline.
Love the improving margins and strong cash conversion at AddLife, but wary of paying up for a premium P/E? Screen for peers that combine pricing power with disciplined balance sheets in our list of solid balance sheet and fundamentals stocks (203 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): SEK 2,599m vs SEK 2,429m (up 7.0%)
- Net Income (Q3 2026 vs Q3 2025): SEK 127m vs SEK 81m (up 56.8%)
- Basic EPS (Earnings Per Share) (Q3 2026 vs Q3 2025): SEK 1.04 vs SEK 0.66 (up 56.8%)
- Adjusted EBITA Margin (Q3 2026 vs Q3 2025): 11.5% vs 10.4% (improved by 1.1 percentage points)
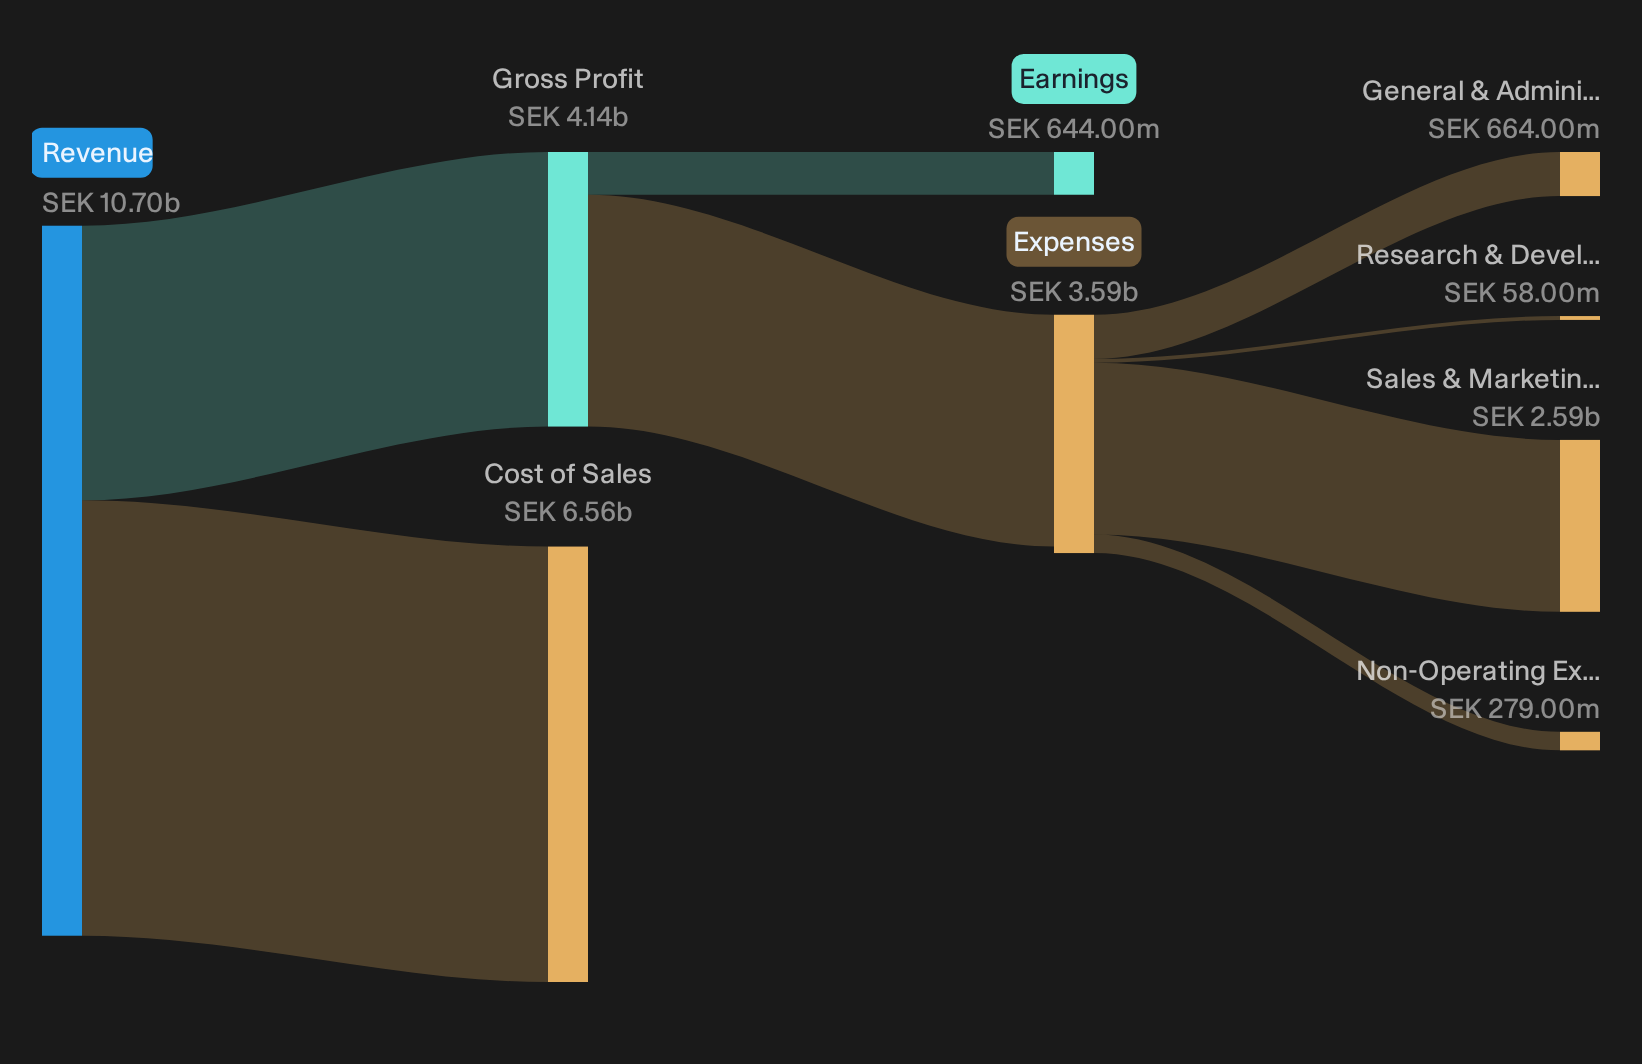
AddLife margin play meets real cash progress
Supporters argue that AddLife can refine its product mix and use a stronger balance sheet to turn higher quality growth into better profitability.
"AddLife is prioritizing organic growth and profitability improvements through initiatives such as optimizing their product portfolio by removing less profitable products, which is expected to enhance gross margins and overall earnings."
Q3 shows that thesis taking shape. Gross margin improved by about 1 percentage point and adjusted EBITA margin reached 11.5%. Operating cash flow rose 62% and cash conversion stayed above 100%, while net leverage of roughly 2.5x and refinanced bank lines keep firepower available for further bolt ons.
Bear risks on funding and supply not yet decisive
On the worry side, the story centers on external funding and supply chain strain eroding growth and profitability.
"AddLife is facing some market hesitation regarding investment in academic research, which could affect future revenue growth if funding in this area does not improve."
Recent figures show 7% revenue growth with 4% organic, helped by tender activity and acquisitions like Unicam and Lehnen. Labtech, where research exposure is meaningful, reported higher margins and growth, while management flagged headwinds more from Spanish healthcare labor disputes and timing of public spending than from broad research funding cuts.
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there.
Hunt Quiet Dislocations In Plain Sight
AddLife recently highlighted how a clearer margin narrative can shift expectations. The real opportunity sits in studying stocks that could be undervalued before the market reassesses them.
- Company 1 - 45% below our estimate - sells oncology planning software that connects with rival machines so hospitals standardize workflows without replacing existing hardware.
- Company 2 - 32% below our estimate - rides renewed chip equipment budgets as customers restart tool purchases and prioritize higher margin photonic systems.
- Company 3 - 27% below our estimate - adds smaller neighborhood formats and online grocery options that redirect spending from larger traditional stores.
Those are three of them. See every one of the 190 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com