
Taiwan Semiconductor Manufacturing (TSM) Gets A Moody's Upgrade, Is It Now Overvalued?
Moody’s decision to lift Taiwan Semiconductor Manufacturing (NYSE:TSM) to an Aa2 issuer rating, with a stable outlook, puts fresh attention on the chip maker’s balance sheet strength and funding flexibility for investors.
Over the past year, Taiwan Semiconductor Manufacturing has combined a 35.13% year to date share price gain with a 50.72% one year total shareholder return. That longer track record, including a three year total shareholder return of just over 4x, suggests momentum remains firm even though the 30 day share price return is down 2.98% from a recent peak.
Scan beyond Taiwan Semiconductor Manufacturing and see how other chip and AI infrastructure plays measure up in our hand picked list of 55 AI infrastructure stocks for this theme.
Bulls see Taiwan Semiconductor Manufacturing as the AI infrastructure kingpin, while bears see a capital intensive giant loaded with 2nm and overseas build costs. Which story does the current valuation actually support?
Most Popular Narrative: 14% Overvalued
Against a fair value of $378.29 from the most followed narrative, Taiwan Semiconductor Manufacturing last closed at $431.89, which places the stock well above that appraisal and squarely in the debate over how much optimism is already in the price.
TSMC is the rarest of things: a monopoly whose dominance is rooted not in regulatory capture or historical accident, but in genuine technological supremacy. The company has spent decades perfecting the art of manipulating matter at atomic scales, and the cumulative knowledge embedded in its fabrication processes is essentially irreproducible.
See why 128 investors see Taiwan Semiconductor Manufacturing as 14% overvalued.
Result: Fair Value of $378.29 (OVERVALUED)
Still, two pressure points could flip this Taiwan Semiconductor Manufacturing story fast: any disruption around Taiwan or a sharp pullback in AI chip spending.
Find out about the key risks to this Taiwan Semiconductor Manufacturing narrative.
Another View: What Multiples Say About Taiwan Semiconductor Manufacturing
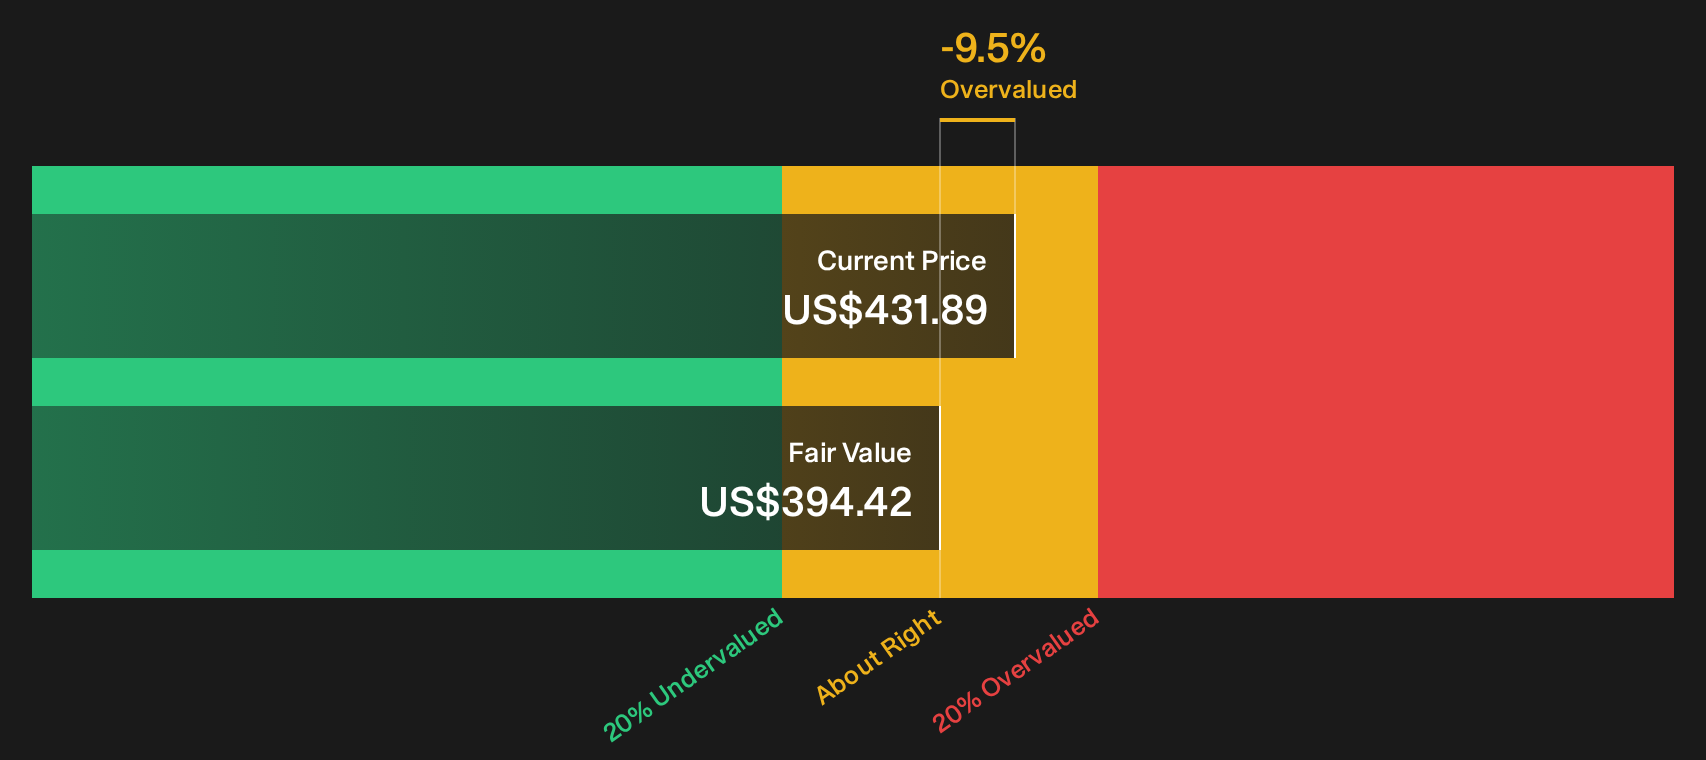
On pure cash flow arithmetic, Taiwan Semiconductor Manufacturing screens as overvalued, with the SWS DCF model pointing to a fair value of $394.42 against a $431.89 share price. The story changes when you look at earnings multiples. A P/E of 24.8x sits well below the US Semiconductor sector on 45.5x and under peer averages of 55.4x. The fair ratio points to 42.5x as a level the market could move toward. That gap hints at upside if earnings forecasts play out, yet it also raises a harder question. Is the DCF being too harsh on risk, or are multiples underpricing it?
For a closer look at how this alternative lens values Taiwan Semiconductor Manufacturing, and how that stacks up against the earnings multiple picture, Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment on Taiwan Semiconductor Manufacturing in this piece is mixed, so treat it as your cue to move fast, pull up the numbers, weigh the concerns against the potential, then ground your stance in 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Taiwan Semiconductor Manufacturing?
If Taiwan Semiconductor Manufacturing has your attention, do not stop here. Broaden your watchlist with fresh ideas that combine quality, resilience, and different income profiles.
Use the Simply Wall St screener to quickly surface stocks that match your risk tolerance, time horizon, and preferred mix of quality, value, and income potential.
- Zero in on potential bargains that pair solid fundamentals with market skepticism through our 21 high quality undiscovered gems.
- Prioritize resilience and capital preservation by focusing on companies flagged in the 31 resilient stocks with low risk scores.
- Target a blend of income and quality by scanning for high yielders in the 7 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com