
Asian Undervalued Small Caps With Insider Action For October 2026
In October 2026, the Asian markets have been navigating a complex landscape marked by heightened volatility in technology stocks and broader concerns about inflation and interest rates. Despite these challenges, small-cap stocks in Asia present intriguing opportunities as investors seek value amidst shifting market dynamics. Identifying promising small-cap companies often involves looking at those with strong fundamentals that can withstand economic pressures and potentially benefit from insider confidence.
Top 10 Undervalued Small Caps With Insider Buying In Asia
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Security Bank | 4.0x | 0.9x | 21.96% | ★★★★★★ |
| Q Technology (Group) | 3.3x | 0.2x | 46.63% | ★★★★★☆ |
| Charter Hall Long WALE REIT | 8.5x | 12.1x | 39.92% | ★★★★★☆ |
| China Aircraft Leasing Group Holdings | 6.8x | 0.9x | 40.77% | ★★★★★☆ |
| DMCI Holdings | 5.5x | 0.8x | 47.07% | ★★★★☆☆ |
| Citicore Energy REIT | 13.1x | 9.9x | 27.34% | ★★★★☆☆ |
| Australian Finance Group | 7.8x | 0.3x | 14.50% | ★★★★☆☆ |
| Clover | 16.3x | 1.7x | 46.94% | ★★★☆☆☆ |
| Centurion | 16.0x | 3.1x | 19.47% | ★★★☆☆☆ |
| FINEOS Corporation Holdings | 96.4x | 2.8x | 49.93% | ★★★☆☆☆ |
Let's take a closer look at a couple of our picks from the screened companies.
Citicore Energy REIT (PSE:CREIT)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Citicore Energy REIT focuses on leasing renewable energy real estate properties and has a market capitalization of approximately ₱15.74 billion.
Operations: CREIT generates revenue primarily from leasing activities, with a notable gross profit margin of 94.43% as of the latest period. The company has experienced fluctuations in net income margin, reaching 75.71% recently, influenced by operating and non-operating expenses.
PE: 13.1x
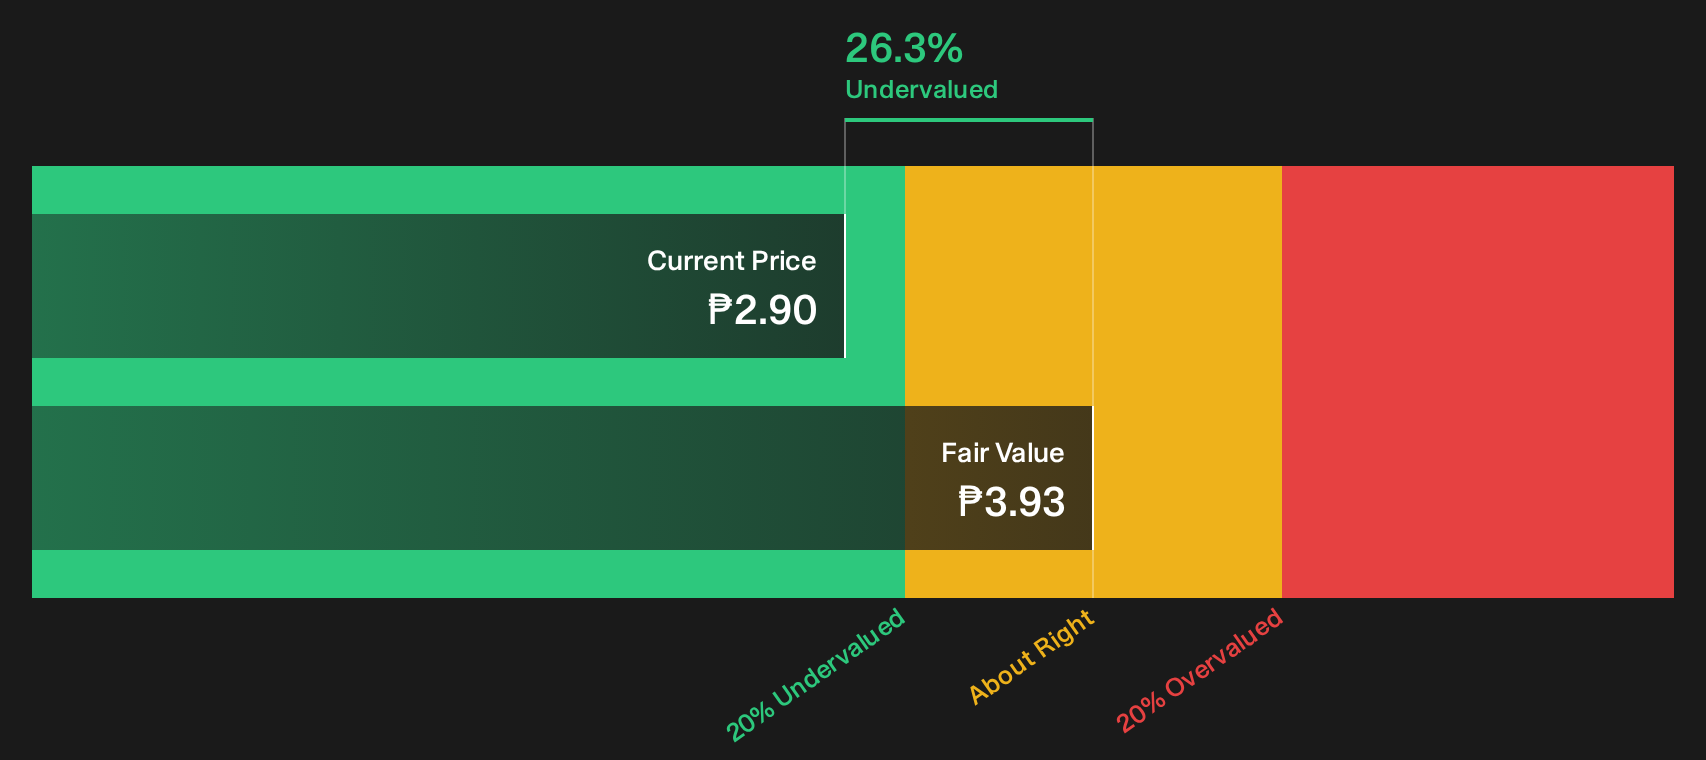
Citicore Energy REIT, a player in the renewable energy sector, shows potential as an undervalued investment. Recent insider confidence is evident with Oliver Tan purchasing over 2 million shares for approximately PHP 5.8 million, boosting their stake by 14%. Despite facing higher-risk funding due to reliance on external borrowing, the company maintains steady earnings growth and declared a cash dividend of PHP 0.049 per share for Q2 2026. Looking ahead, earnings are projected to grow annually by nearly 8%, suggesting positive future prospects amidst financial challenges.
Shougang Fushan Resources Group (SEHK:639)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Shougang Fushan Resources Group is primarily engaged in coking coal mining operations, with a market capitalization of HK$10.59 billion.
Operations: The company's primary revenue stream comes from coking coal mining, with recent revenue reaching HK$6.20 billion. The cost of goods sold is a significant portion of expenses, totaling HK$4.63 billion in the latest period. The gross profit margin has shown variability, recently recorded at 25.25%. Operating expenses include general and administrative costs and sales and marketing expenses, contributing to the overall financial performance.
PE: 16.2x
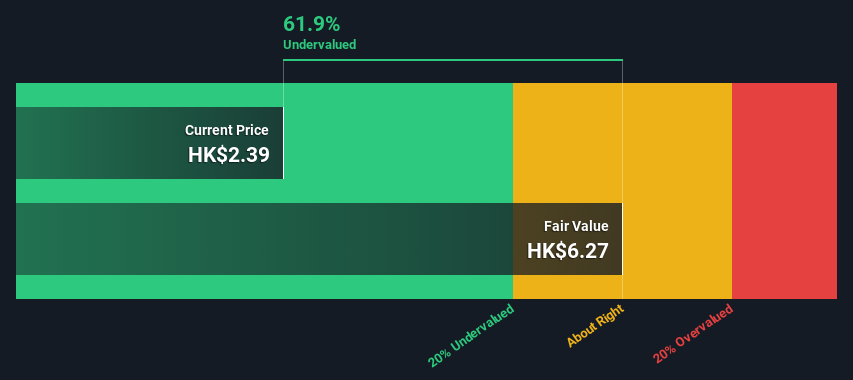
Shougang Fushan Resources Group, a coal-focused entity in Asia, shows potential as an undervalued opportunity. Recent insider confidence is evident with share purchases throughout 2026. The company reported a notable rise in sales to HK$3.24 billion for the first half of 2026, up from HK$2.10 billion the previous year, alongside increased net income of HK$588 million. With new leadership under Li Meng and strategic initiatives like the 2026 share option scheme, future growth appears promising despite reliance on external borrowing for funding.
Ho Bee Land (SGX:H13)
Simply Wall St Value Rating: ★★★★★☆
Overview: Ho Bee Land is a real estate company involved in property investment and development, with a market capitalization of approximately SGD 2.12 billion.
Operations: Ho Bee Land generates revenue primarily through property investment and development, with the latter contributing slightly more. The company's gross profit margin has shown variability, peaking at 91.70% in mid-2020 before declining to 58.96% by mid-2026. Operating expenses have consistently been a notable portion of costs, with recent figures around SGD 39.95 million as of June 2026.
PE: 12.4x
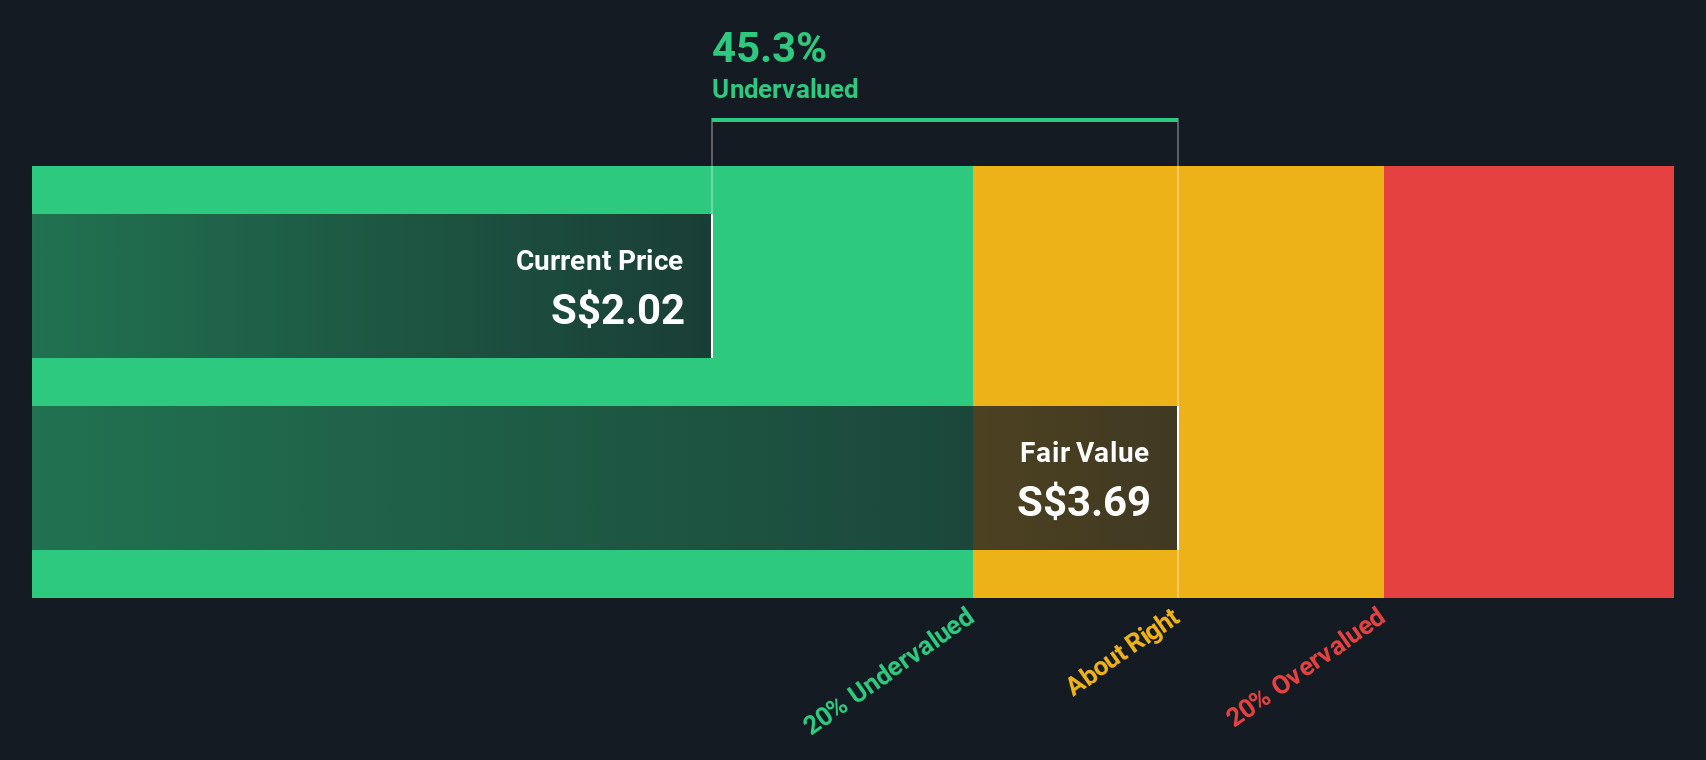
Ho Bee Land, a company with a focus on real estate development, shows potential as an undervalued investment in Asia. The CEO's recent purchase of 220,000 shares for approximately S$451,000 signals insider confidence. Despite lower profit margins than the previous year and reliance on external borrowing for funding, the company is actively pursuing strategic ventures in Australia. Their joint ventures enhance capital efficiency and geographic diversification without significantly impacting earnings or net tangible assets this financial year.
- Get an in-depth perspective on Ho Bee Land's performance by reading our valuation report here.
Evaluate Ho Bee Land's historical performance by accessing our past performance report.
Taking Advantage
- Embark on your investment journey to our 60 Undervalued Asian Small Caps With Insider Buying selection here.
- Got skin in the game with these stocks? Elevate how you manage them by using Simply Wall St's portfolio, where intuitive tools await to help optimize your investment outcomes.
- Maximize your investment potential with Simply Wall St, the comprehensive app that offers global market insights for free.
Looking For Alternative Opportunities?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com