
3 UK Growth Companies With Insider Ownership And 46% Earnings Growth
As the UK market grapples with the ripple effects of China's faltering trade data, reflected in recent declines of the FTSE 100 and FTSE 250 indices, investors are increasingly seeking growth opportunities that can withstand global economic uncertainties. In such a climate, companies with strong insider ownership and significant earnings growth potential are often seen as attractive options for those looking to navigate these complex market conditions.
Top 10 Growth Companies With High Insider Ownership In The United Kingdom
| Name | Insider Ownership | Earnings Growth |
| TPXimpact Holdings (AIM:TPX) | 19.5% | 106% |
| TEAM (AIM:TEAM) | 32% | 85.3% |
| Quantum Base Holdings (AIM:QUBE) | 31.8% | 111.8% |
| Mortgage Advice Bureau (Holdings) (LSE:MAB1) | 18.4% | 22.4% |
| Gulf Keystone Petroleum (LSE:GKP) | 12.5% | 21.1% |
| Energean (LSE:ENOG) | 19.3% | 32.8% |
| EARNZ (AIM:EARN) | 10.1% | 90.6% |
| Crimson Tide (AIM:TIDE) | 33.5% | 119.1% |
| Built Cybernetics (AIM:BUC) | 22.6% | 122.1% |
| Beauty Tech Group (LSE:TBTG) | 19.9% | 23.8% |
Let's review some notable picks from our screened stocks.
Griffin Mining (AIM:GFM)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Griffin Mining Limited is a mining and investment company focused on the exploration, development, and mining of mineral properties, with a market cap of £551.06 million.
Operations: Griffin Mining's revenue is primarily derived from the Caijiaying Zinc Gold Mine, which generated $151.07 million.
Insider Ownership: 11.9%
Earnings Growth Forecast: 33% p.a.
Griffin Mining demonstrates potential as a growth company with significant insider ownership. Its earnings are forecast to grow at 33% per year, outpacing the UK market's 11.2%. The stock trades at a substantial discount to its estimated fair value. Recent executive changes saw Asha Santchurn appointed CFO, bringing extensive expertise in financial reporting and governance. For H1 2026, Griffin reported strong financial results with net income rising to US$20.98 million from US$8.78 million the previous year.
- Click to explore a detailed breakdown of our findings in Griffin Mining's earnings growth report.
- Insights from our recent valuation report point to the potential overvaluation of Griffin Mining shares in the market.
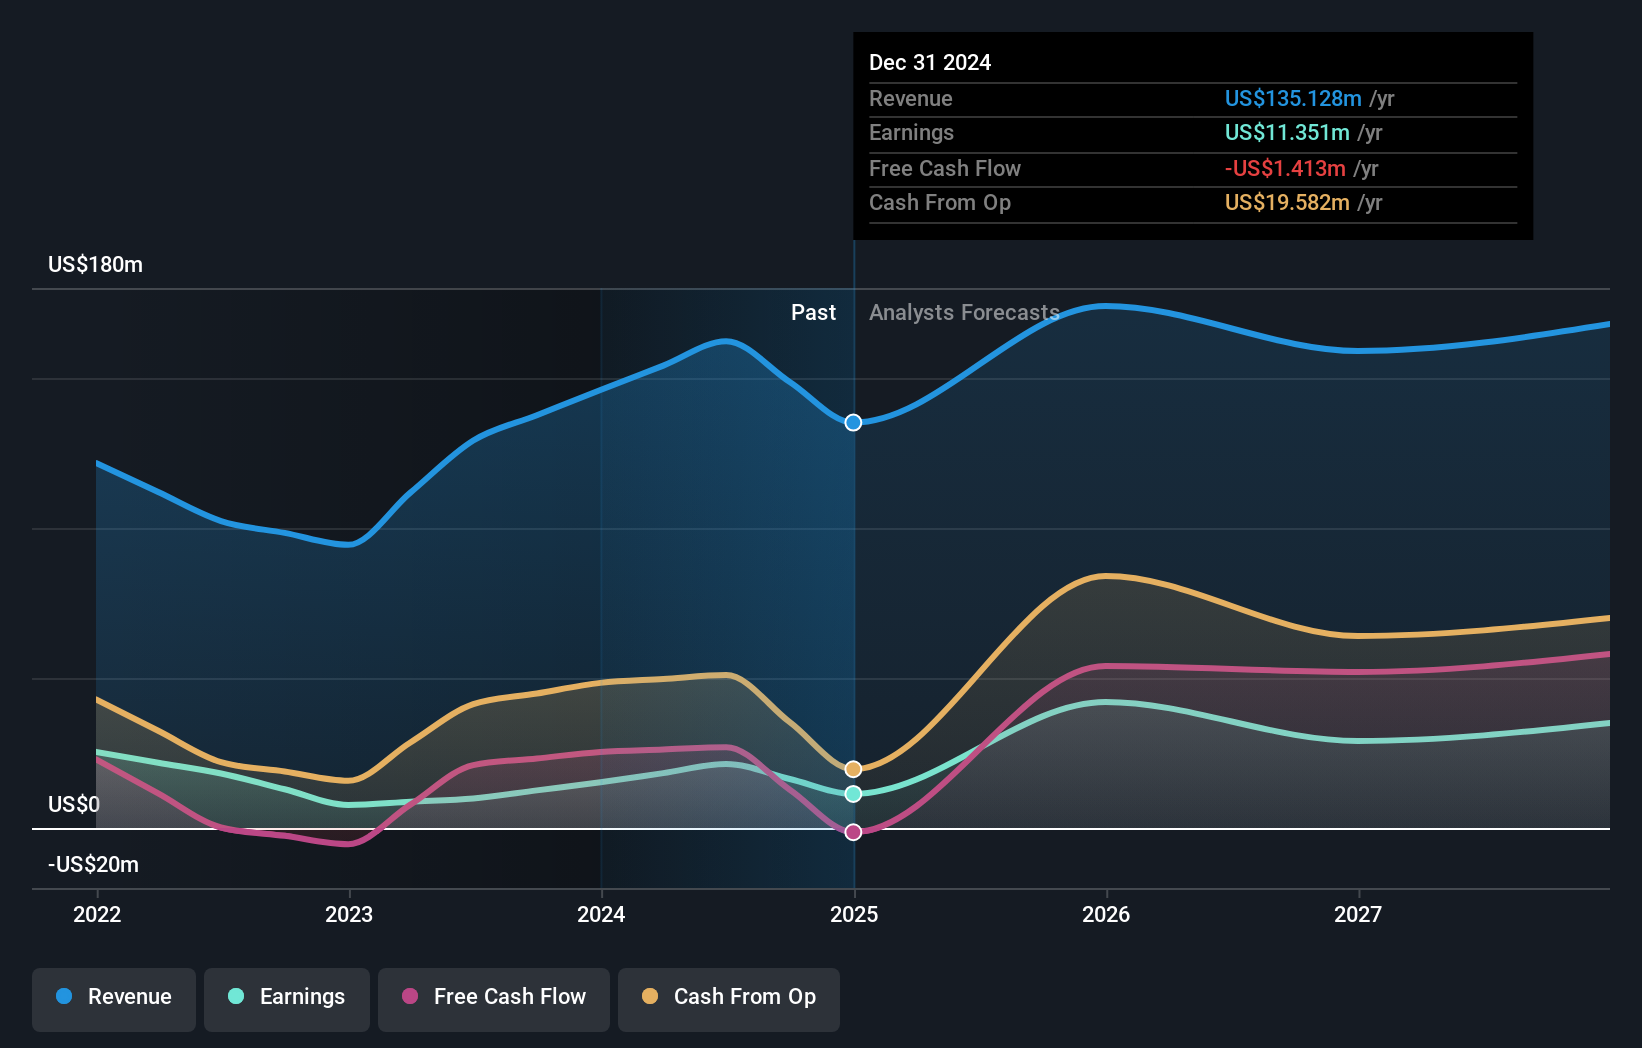
Greencore Group (LSE:GNC)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Greencore Group plc, with a market cap of £2.21 billion, manufactures and sells convenience food products in the United Kingdom and Ireland through its subsidiaries.
Operations: The company generates revenue of £2.34 billion from its Convenience Foods segment in the UK and Ireland.
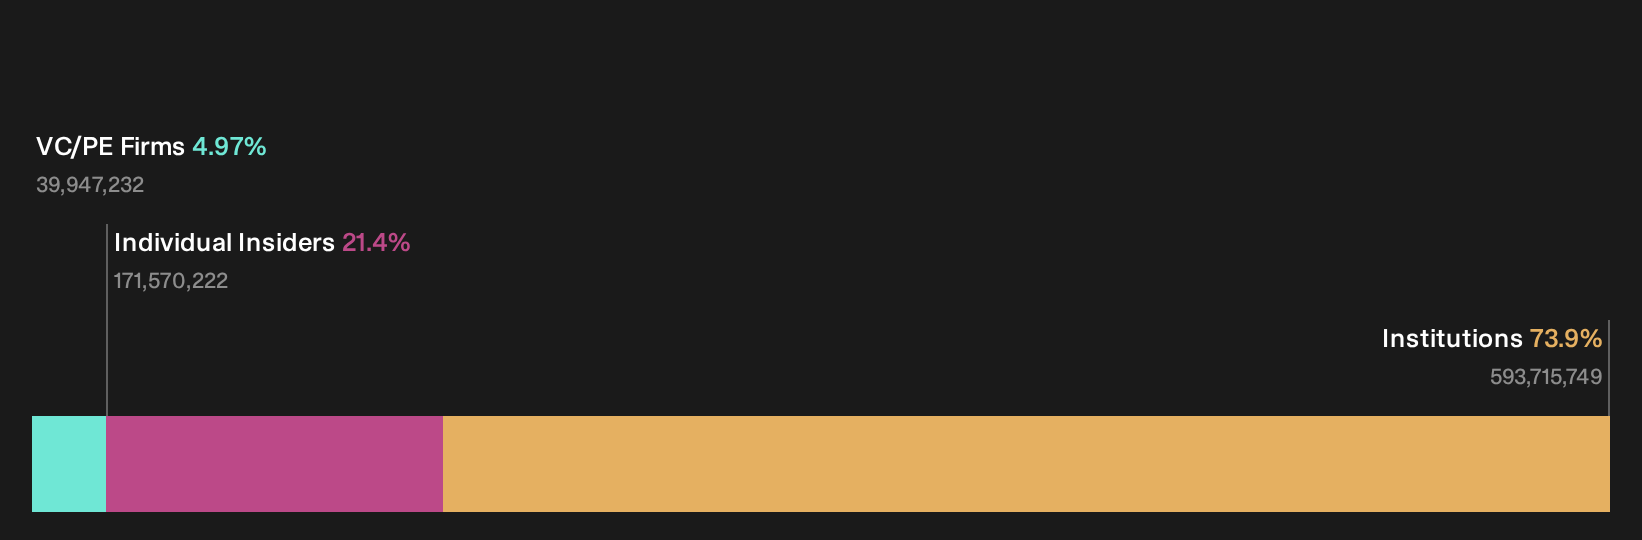
Insider Ownership: 21.4%
Earnings Growth Forecast: 46.7% p.a.
Greencore Group shows potential for growth with substantial insider buying over the past three months, indicating confidence in its future. While revenue is expected to grow at 14.1% annually, outpacing the UK market's 3.8%, earnings are forecast to rise significantly by 46.7% per year, well above market averages. However, recent shareholder dilution and a decline in profit margins from last year highlight challenges despite trading at a significant discount to fair value estimates.
- Navigate through the intricacies of Greencore Group with our comprehensive analyst estimates report here.
- Insights from our recent valuation report point to the potential undervaluation of Greencore Group shares in the market.
International Workplace Group (LSE:IWG)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: International Workplace Group plc, along with its subsidiaries, offers workspace solutions across the Americas, Europe, the Middle East, Africa, and the Asia Pacific with a market cap of approximately £1.75 billion.
Operations: The company's revenue segments include Company-Owned at $3.31 billion and Managed & Franchised at $151 million.
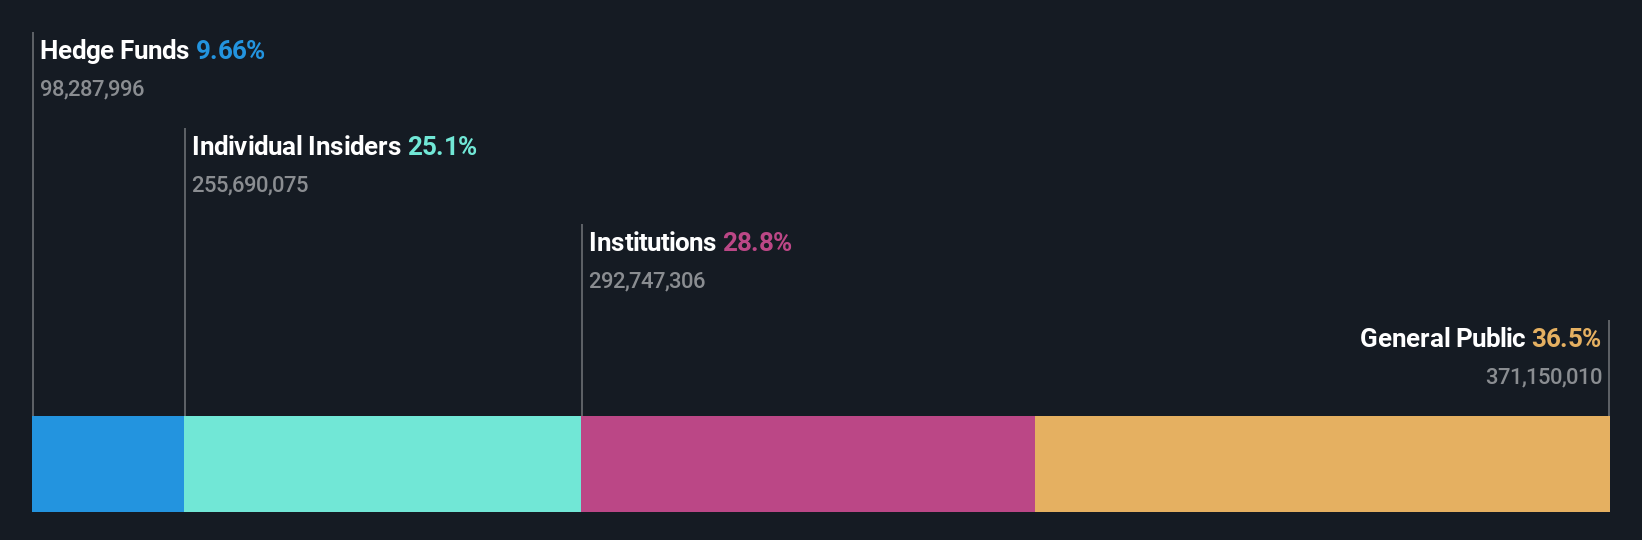
Insider Ownership: 27.1%
Earnings Growth Forecast: 41.9% p.a.
International Workplace Group is positioned for growth with a high forecasted annual earnings increase of 41.9%, outpacing the UK market average. Despite a slower revenue growth projection of 3.2% annually, its return on equity is expected to be very high in three years. The company's recent $50 million buyback plan expansion suggests confidence in its valuation, which trades at 52.3% below fair value estimates, although it faces challenges with negative shareholders' equity and lower profit margins compared to last year.
- Take a closer look at International Workplace Group's potential here in our earnings growth report.
- Our valuation report unveils the possibility International Workplace Group's shares may be trading at a discount.
Key Takeaways
- Gain an insight into the universe of 64 Fast Growing UK Companies With High Insider Ownership by clicking here.
- Interested In Other Possibilities? Trump's oil boom is here — pipelines are primed to profit. Discover the 22 US stocks riding the wave.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com