
Tanger (SKT) Keeps Its Dividend Appeal, Is The Stock Still Cheap?
Tanger (SKT) reaffirmed its income appeal, with the Board declaring a quarterly cash dividend of $0.3125 per share, payable on November 13, 2026, to shareholders of record on October 30.
The dividend news arrives after a mixed stretch for Tanger’s equity. The share price is down about 14% over the past 90 days, but it still shows a 7.58% year to date gain and a 1 year total shareholder return of 12.89%. This builds on very large 3 and 5 year total shareholder returns of 72.51% and 154.39% respectively.
Scan beyond Tanger and compare this dividend REIT story with curated income ideas in the 8 dividend fortresses to see how other high-yield players stack up on quality and resilience.
Tanger’s share price slipped over the past quarter, while analyst targets and intrinsic value estimates still point higher. Is that gap a genuine margin of safety, or a value trap unfolding in slow motion?
Most Popular Narrative: 13% Undervalued
Tanger closed at $35.62, while the most followed narrative assigns a fair value of $41.00 using a 7.98% discount rate. The gap rests on how rent spreads, liquidity and ancillary income play out over time.
The main thing that has to go right is Tanger successfully re-tenanting recaptured and vacant space, especially former Saks Off 5th boxes, at materially higher rents while continuing to grow ancillary revenue at double-digit rates.
The current valuation implies that Tanger’s record leasing activity, raised core FFO guidance, and conservative balance sheet are being discounted more cautiously than a bullish view that the stock is undervalued would suggest.
See why 6 investors see Tanger as 13% undervalued.
Result: Fair Value of $41 (UNDERVALUED)
Still, Tanger’s thesis can crack if leasing momentum slows and recaptured space fails to reach those targeted rent multiples, or if higher operating costs pressure same center NOI.
Find out about the key risks to this Tanger narrative.
Another View: What Multiples Say About Tanger
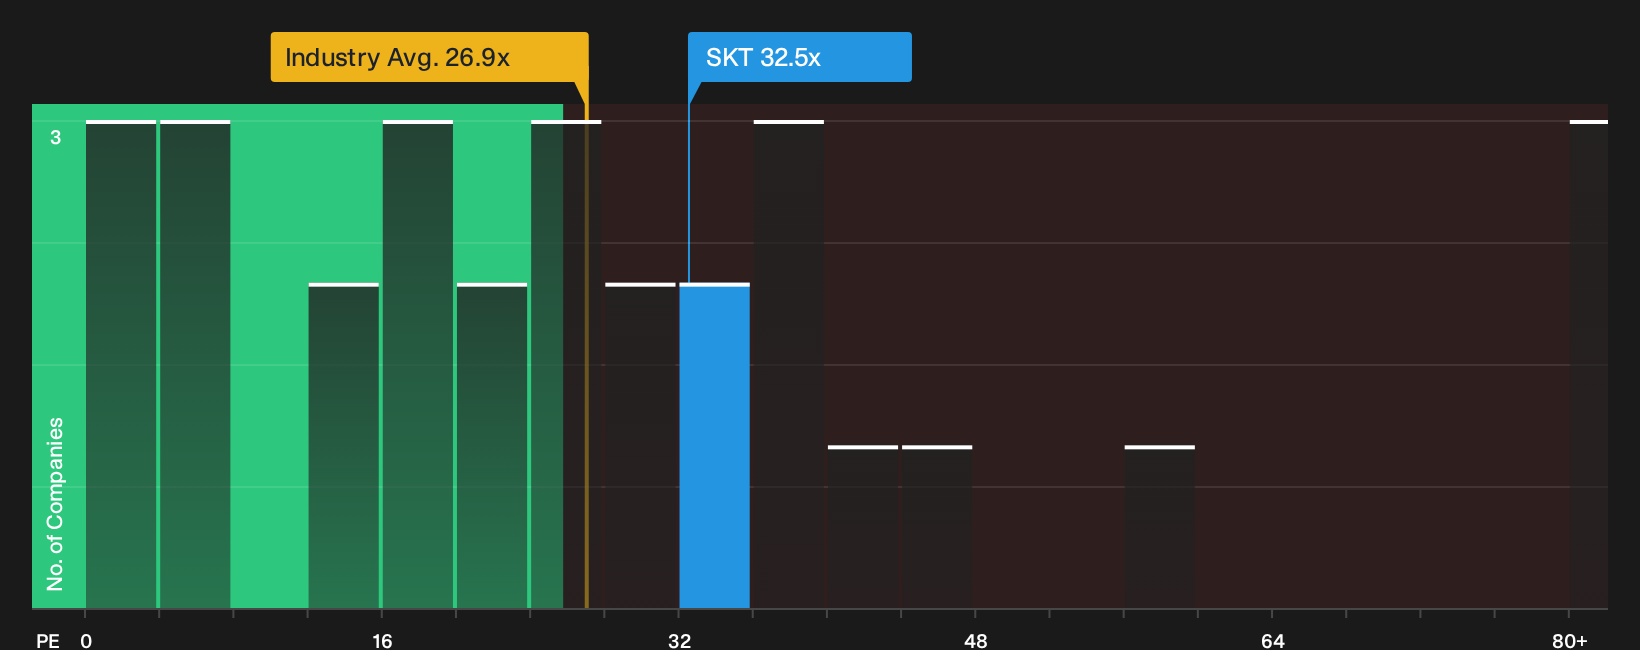
While the SWS DCF model sees Tanger as undervalued, the market’s simple P/E check tells a tougher story. The stock trades at 32.5x earnings, richer than the US Retail REITs industry on 26.5x and slightly above a 32.3x fair ratio. That mix points to less margin of error if growth or rent spreads disappoint.
Before leaning on any single approach, it helps to see how these numbers line up in a fuller valuation breakdown, including how peers are priced and where that fair ratio could drift over time. See what the numbers say about this price — find out in our valuation breakdown.
Here is how Tanger’s valuation compares visually with the broader sector using a simple earnings multiple snapshot.
Next Steps
Mixed messages on Tanger can either paralyze you or push you to inspect the data yourself and decide what really matters. If you want a quick way to balance the upside story against the concerns already on investor radars, start with the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Tanger?
If Tanger has sharpened your thinking on income and value, do not stop here. Use the screener to spot other opportunities before they move without you.
- Target income resilience by checking out dividend payers with staying power through the 8 dividend fortresses.
- Hunt for mispriced quality and see which companies line up in the 34 high quality undervalued stocks.
- Prioritise capital protection first and scan financially sturdy candidates in the 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com