
Why Nemetschek Fell Even As Profit Rose
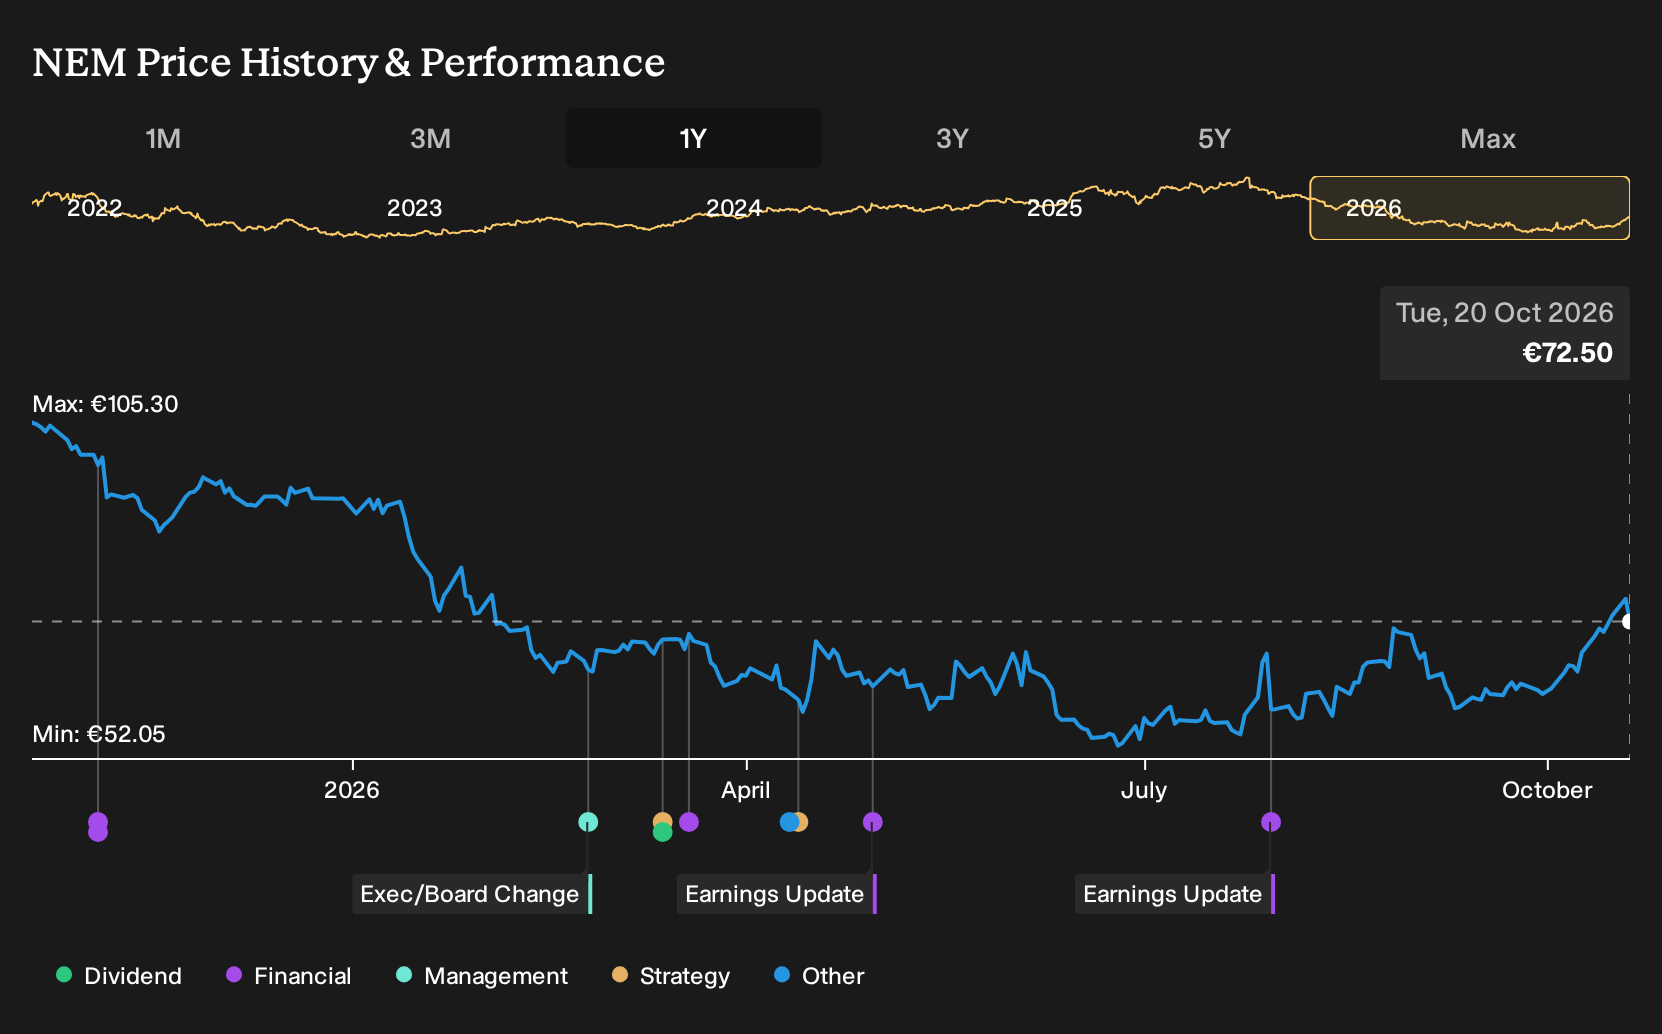
If you only glanced at Nemetschek’s latest headlines, you would see a business talking up recurring software subscriptions, international growth and new AI products, plus reporting higher revenue and profit in the most recent quarter. Holding Nemetschek over the past year would have meant a 30.2% loss, including dividends. If you had been weighing up a purchase in October 2025, what clues were already on the table that this gap between story and outcome might open up?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
The easy part of this move is behind Nemetschek. Zero in on 188 high quality undervalued stocks for companies trading below our estimates.
The Two Nemetschek Stories Investors Had To Weigh
The shares cost €105 at the start of the period, and anyone looking at Nemetschek then had to choose between two very different but plausible stories.
The bullish Narrative put Fair Value at €126, or 19% above the start price. It was built on assumptions of 14.0% annual revenue growth and profit margins rising to 21.7%, helped by the shift to SaaS and expansion in markets such as India and Saudi Arabia.
The bearish case saw Fair Value at €83, or 21% below the start price. It focused on risks such as shrinking multiyear subscription deals and AI features becoming commoditized, which could pressure pricing and margins.
What The Results Changed For The Nemetschek Story
The clearest new fact for Nemetschek was delivery of Q2 2026 revenue of €327.656m and net income of €66.038m, with net margin at 20.2% versus 18.1% a year earlier. That shift in profitability leaned toward the bullish case that expected margin progress, while the share price slide kept the bearish valuation worries in play, so the evidence cut both ways.
The useful lesson is where to point your attention. When a thesis leans on expanding profitability, watch the reported net margin line first and treat any rich P/E as a separate bet you are making on what others will pay later.
What Nemetschek’s Lower Price Is Asking You To Believe
Nemetschek now trades at €72.5, with the past year’s return down 30.2%. The selected Narrative still places Fair Value above that level, tied to a story about recurring contracts, HCSS and AI tools shaping earnings power.
The key bet a buyer tests today is that Nemetschek’s high share of subscription revenue and Build segment expansion can support meaningfully stronger profit margins over time.
"Ongoing transition of Nemetschek’s customer base from perpetual licenses to subscription and SaaS, with recurring revenue already at 95% of group revenue and subscription and SaaS at 80% in H1 2026, supports higher revenue visibility and can improve earnings quality through a more predictable margin profile."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Looking One Step Beyond Nemetschek
Nemetschek’s story leans on software shaping how physical assets are planned and built. You could look one ring further out.
As more projects rely on connected data, security and control move up the priority list. It is not just architects and engineers who care.
Another specialist focuses on turning sensitive information into something large organisations can use safely. Its tools sit inside critical workflows where mistakes carry real-world consequences.
Those customers face similar questions to Nemetschek’s base about trust, lock-in and resilience. If secure AI becomes standard infrastructure, that role may matter more.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 88% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com