
Madison Square Garden Entertainment (MSGE) After LeBron Debut Buzz Is It Still Undervalued
Madison Square Garden Entertainment (MSGE) is back in the spotlight as the arena hosts LeBron James’ first regular season game as a 76er, alongside the Knicks’ 2025-26 championship celebration.
For investors watching Madison Square Garden Entertainment, the LeBron debut and Knicks banner night land at a time when momentum has already been building, with a 48.47% year-to-date share price return and a 76.93% total shareholder return over one year, alongside a 162.29% total shareholder return over three years, which together point to strong long term compounding even before these high profile events and new partnerships feed into perception of future growth and risk.
Scan beyond Madison Square Garden Entertainment and see how other event driven media plays stack up in our curated list of 21 high quality undiscovered gems.
Madison Square Garden Entertainment has already moved sharply this year. This sets up a simple fork in the road for you: lean into the current price and momentum, or wait and risk that the window has already shifted.
Most Popular Narrative: 12% Undervalued
On the numbers, the most followed narrative pegs Madison Square Garden Entertainment’s fair value at $91.63 versus a last close of $80.68. This puts the current quote at a clear discount and turns attention to what needs to keep working in the underlying venues and events.
The main thing that has to go right is that high event volumes, marquee content like the Christmas Spectacular, and sponsorship and premium hospitality spending continue to offset higher operating and SG&A costs as the company invests in technology and venue upgrades.
The current numbers, including share repurchases and management’s guidance for significant underlying free cash flow in fiscal 2027, imply the share price assumes the company will convert its busy venues and long-dated arena license fees into durable cash generation, with limited disruption from legal and data-privacy risks.
See why 1 investors see Madison Square Garden Entertainment as 12% undervalued.
Result: Fair Value of $91.63 (UNDERVALUED)
Still, this depends on Madison Square Garden Entertainment controlling rising operating and legal costs tied to data breach lawsuits and facial recognition scrutiny.
Find out about the key risks to this Madison Square Garden Entertainment narrative.
Another View: What MSGE’s Earnings Multiple Is Telling You
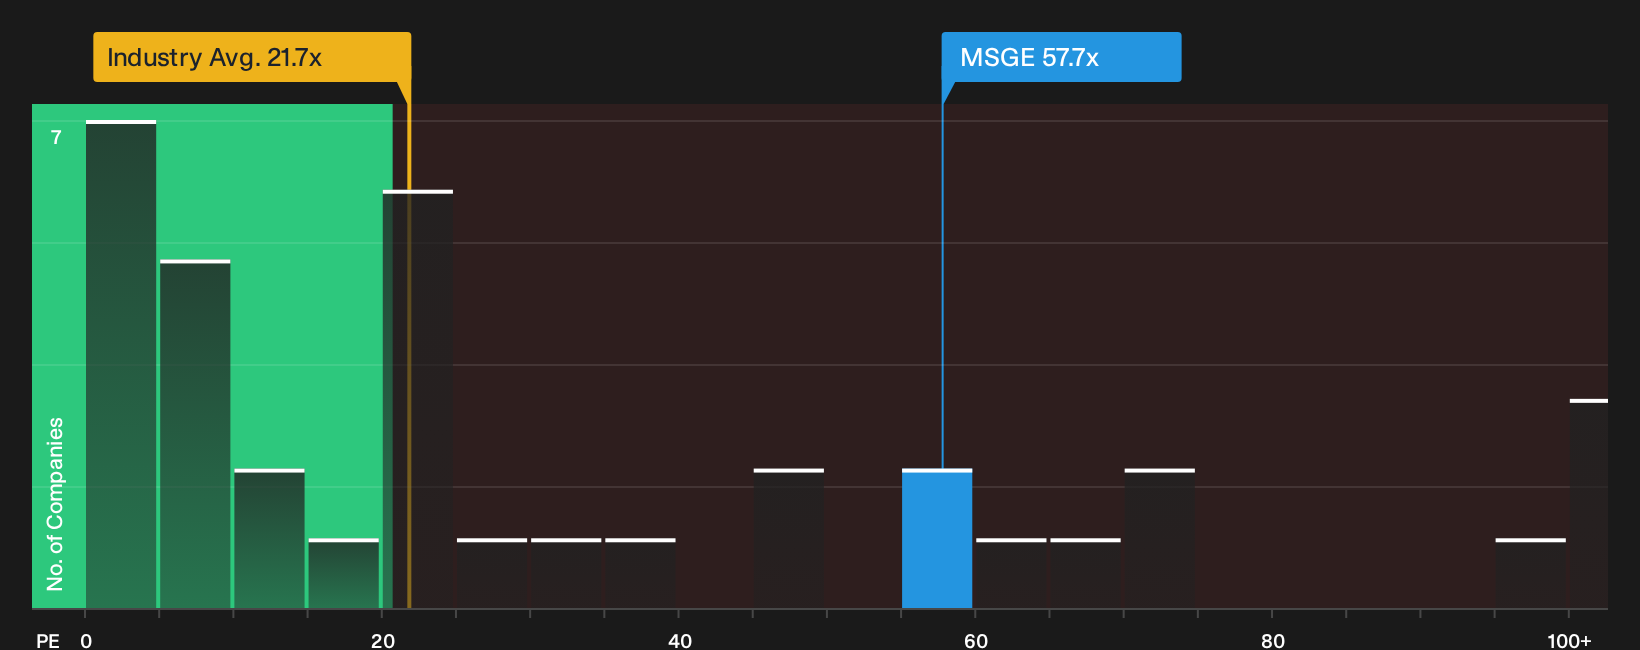
The story around Madison Square Garden Entertainment looks different once you look beyond the share price and focus on the earnings multiple. MSGE trades on a P/E of 57.7x, while the US Entertainment group sits at 21.7x and peers average 31.7x, with a fair ratio estimate of 23x.
That gap suggests investors are already paying a heavy premium for current momentum, even though the headline narrative points to an undervalued stock based on a $91.63 fair value. The question for you is simple: Are you comfortable that future execution, legal risks and debt justify such a rich P/E starting point?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Conflicted by the mix of optimism and concern around Madison Square Garden Entertainment? Use that tension as a prompt to dig into the details yourself and move before the story shifts. Start by weighing the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Madison Square Garden Entertainment?
If Madison Square Garden Entertainment has sharpened your focus, do not stop here. Use the Simply Wall Street Screener to compare other opportunities and pressure-test your thinking.
- Target companies that pair income with resilience by reviewing the 8 dividend fortresses for candidates that could complement a total-return approach.
- Zero in on financially steady businesses by scanning the list of solid balance sheet and fundamentals (25 results) so you can see which tickers back the story with robust foundations.
- Spot potential future leaders early by working through the 10 elite penny stocks with strong financials before attention and capital move there without you.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com