
ASX Penny Stocks To Watch In October 2026
Australian shares are poised to open higher, reflecting the broader strength seen on Wall Street as investors appear to shift their focus beyond large technology stocks amid ongoing volatility in the AI sector. While penny stocks might seem like a term from a bygone era, they continue to offer intriguing opportunities for investors seeking growth at lower price points. By focusing on companies with strong financials and solid fundamentals, these smaller or newer entities can present hidden gems within the market.
Here we highlight a subset of our preferred stocks from the screener.
Black Cat Syndicate (ASX:BC8)
Simply Wall St Financial Health Rating: ★★★★★★
Overview: Black Cat Syndicate Limited, along with its subsidiaries, focuses on mining and processing gold properties in Western Australia and has a market capitalization of A$517.50 million.
Operations: The company generates revenue from its Kal East Gold Operation and Paulsens Gold Operation, with figures of A$156.79 million and A$217.50 million respectively.
Market Cap: A$517.5M
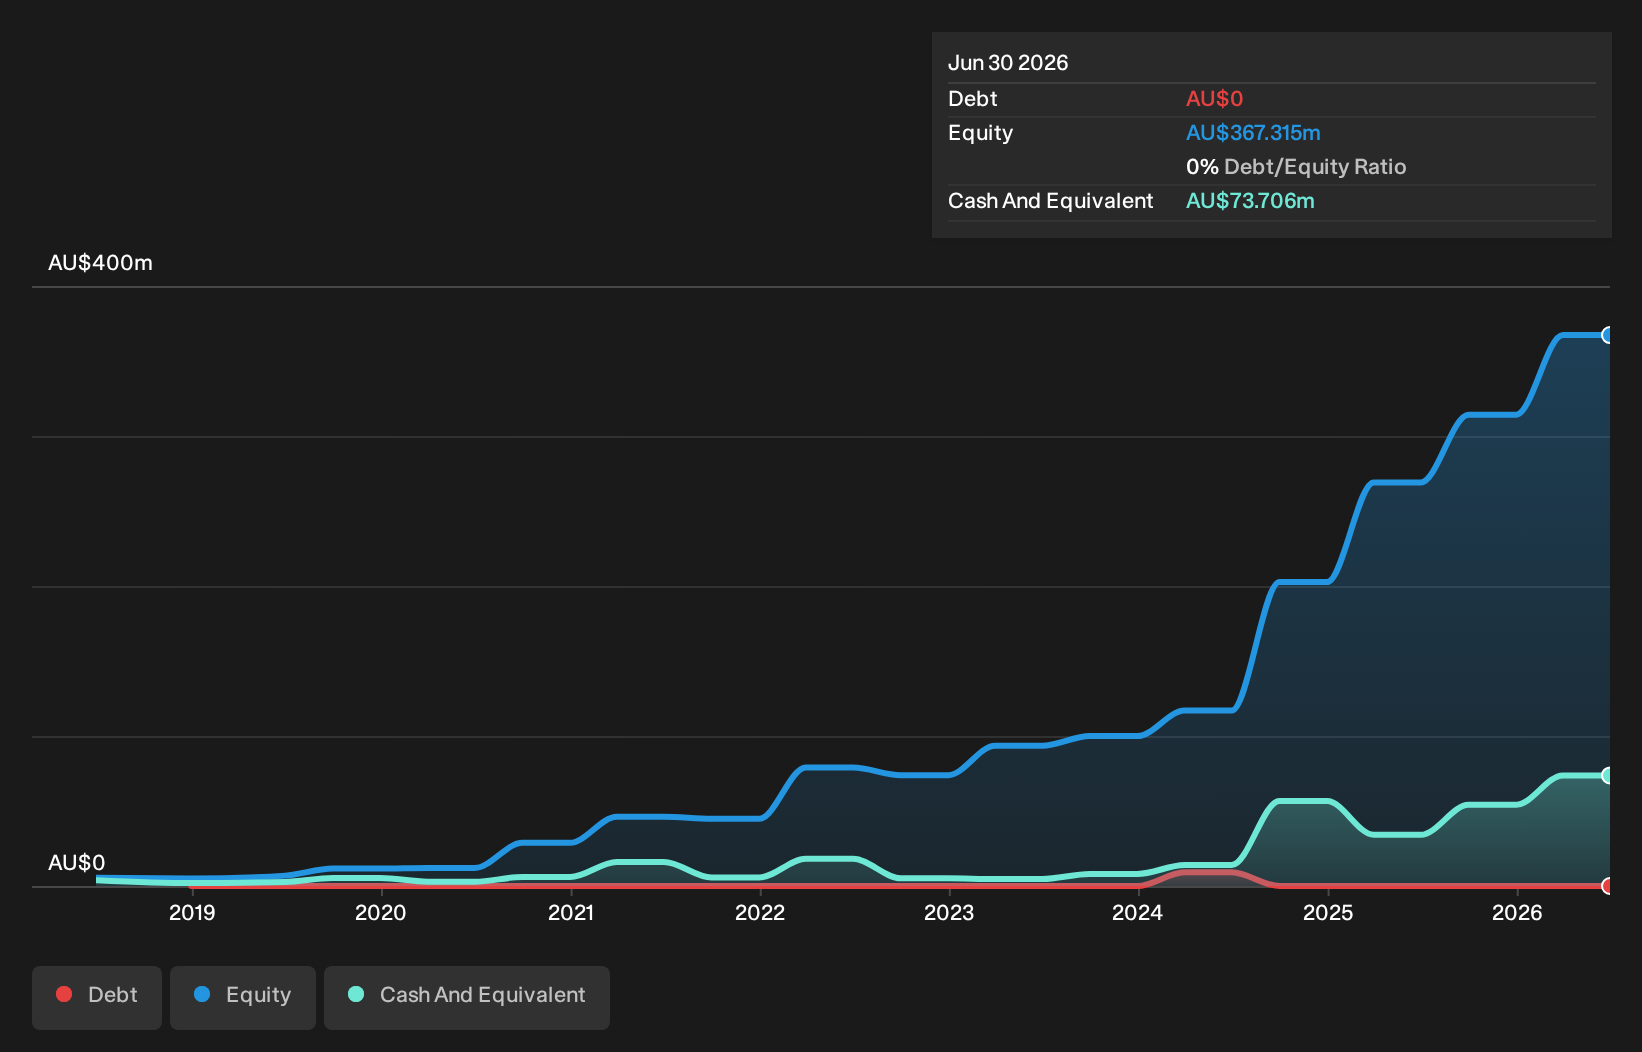
Black Cat Syndicate Limited has shown significant growth, with annual sales reaching A$374.29 million and net income of A$86.46 million, marking its transition to profitability from a previous loss. The company's gold production increased substantially to 90,833 oz in the last fiscal year. Despite having a relatively new board and management team, Black Cat is debt-free and maintains strong short-term asset coverage over liabilities. Recent guidance indicates further production growth for 2027, while the appointment of experienced director Chris Stone may bolster strategic decision-making as the company continues its upward trajectory in earnings and operations.
- Click here to discover the nuances of Black Cat Syndicate with our detailed analytical financial health report.
- Review our growth performance report to gain insights into Black Cat Syndicate's future.
Generation Development Group (ASX:GDG)
Simply Wall St Financial Health Rating: ★★★★★☆
Overview: Generation Development Group Limited operates in the diversified financial services sector in Australia, with a market capitalization of A$1.27 billion.
Operations: The company's revenue segments include Benefit Funds generating A$436.98 million, Group Services (Corporate) at A$20.54 million, Research and Ratings (Lonsec) contributing A$46.14 million, Managed Accounts Business (Evidentia) with A$63.16 million, and Benefit Funds Management & Funds Administration (Generation Life) providing A$64.41 million in revenue.
Market Cap: A$1.27B
Generation Development Group Limited, with a market cap of A$1.27 billion, operates across various financial services segments, generating significant revenues from Benefit Funds and Managed Accounts. Despite stable weekly volatility at 13%, the stock remains more volatile than most Australian stocks. The company's debt is well-covered by operating cash flow, and it maintains more cash than total debt. However, recent earnings have declined to A$31.93 million from A$35.47 million last year, with net profit margins slightly decreasing to 5.5%. The management team is relatively new with an average tenure of 1.3 years, suggesting potential strategic shifts ahead.
- Jump into the full analysis health report here for a deeper understanding of Generation Development Group.
- Evaluate Generation Development Group's prospects by accessing our earnings growth report.

Judo Capital Holdings (ASX:JDO)
Simply Wall St Financial Health Rating: ★★★★☆☆
Overview: Judo Capital Holdings Limited, with a market cap of A$1.04 billion, operates through its subsidiaries to offer a range of banking products and services tailored for small and medium businesses in Australia.
Operations: The company generates revenue primarily through its Small and Medium Enterprises (SMEs) Lending segment, which accounted for A$404.7 million.
Market Cap: A$1.04B
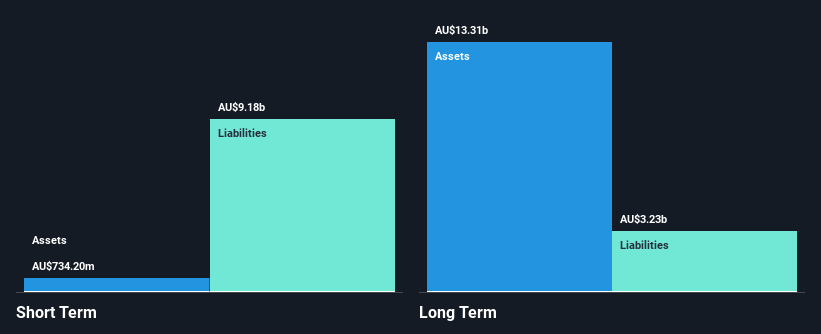
Judo Capital Holdings, with a market cap of A$1.04 billion, demonstrates strong financial health in the SME lending sector, reporting net income of A$111.1 million for FY26, up from A$86.4 million the previous year. The company maintains an appropriate Loans to Assets ratio and primarily relies on low-risk customer deposits for funding. While its Return on Equity is relatively low at 6.3%, earnings growth has been robust at 28.6% over the past year, outperforming industry averages and reflecting high-quality earnings despite a high level of bad loans at 3.3%.
- Unlock comprehensive insights into our analysis of Judo Capital Holdings stock in this financial health report.
- Gain insights into Judo Capital Holdings' outlook and expected performance with our report on the company's earnings estimates.
Seize The Opportunity
- Unlock our comprehensive list of 415 ASX Penny Stocks by clicking here.
- Ready To Venture Into Other Investment Styles? Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com