
Can Barclays (LSE:BARC) Still Justify Its Price On Earnings?
Barclays has delivered a powerful multi‑year share price run, yet the recent pullback and fresh regulatory questions now put the focus squarely on whether the current valuation is still supported by its earnings profile. With the stock moving sharply over different time frames, the key issue for you is how much of the bank's profit engine is already reflected in today's price.
- Over the past 3 years Barclays has returned 241.8%, which puts real pressure on the question of how far its earnings can underpin that kind of share price reset.
- Fresh scrutiny from the Bank of England over complex private credit derivatives may influence how much capital the bank needs to hold, which can feed directly into what portion of earnings is available for shareholders through dividends and buybacks.
- Your read on Barclays is one view; the desks covering it have another. See what analysts think Barclays's shares could be worth.
The issue now is whether Barclays' current share price is justified by the earnings power investors are paying for today.
If you want to test this same earnings question beyond Barclays, you can apply the same approach to a wider field using the 7 high quality undervalued stocks.
Is Barclays Still Cheap on Earnings?
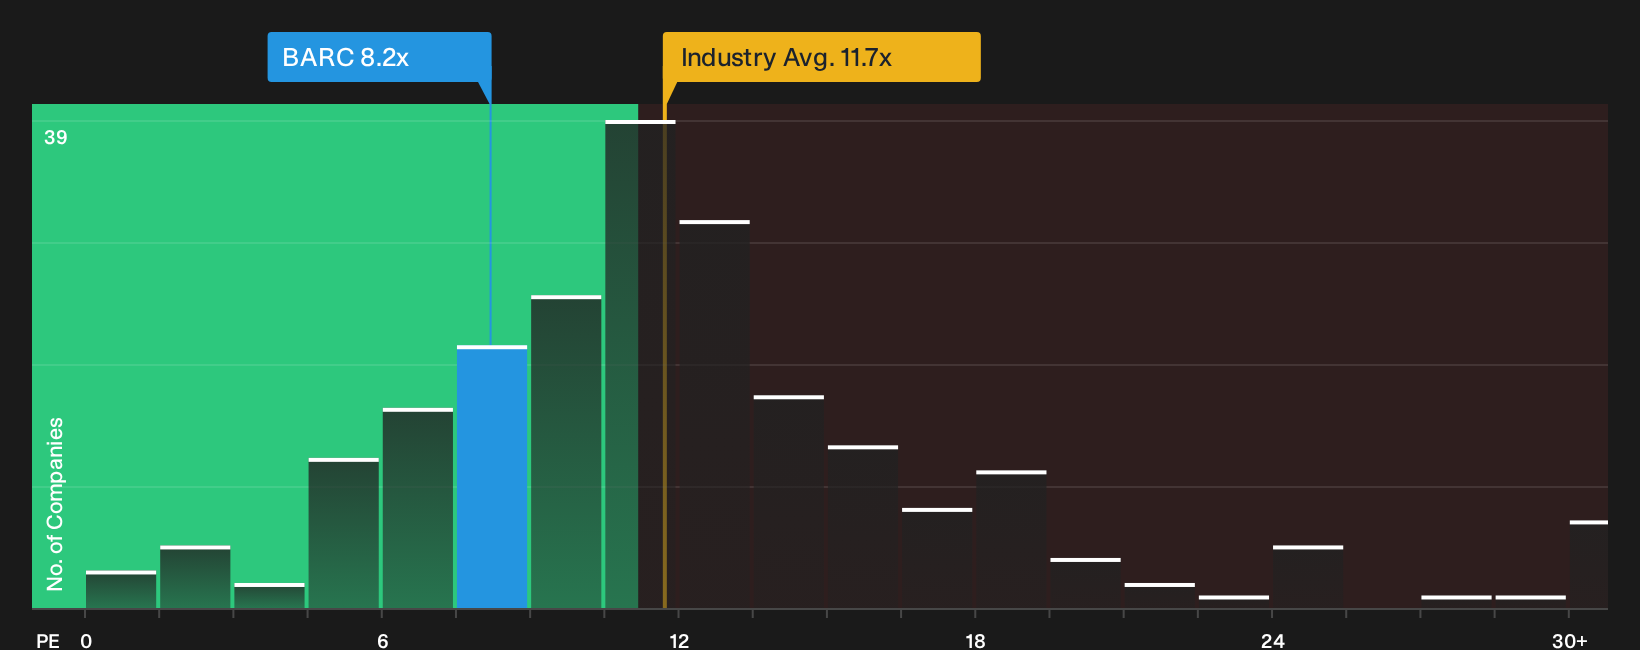
P/E fits Barclays because earnings, not asset values, tend to drive how investors judge large banks. On this yardstick, the current P/E of 8.2x compares with an industry average of 11.1x for banks and a peer group closer to 12.0x, so the shares trade on a lower earnings tag than many comparable institutions.
The Fair Ratio points to the kind of multiple that might line up with Barclays' own profitability profile and risk mix, and the stock currently changes hands below that level. Because the recent Bank of England probe has put extra focus on potential capital demands, this discount suggests the share price already bakes in a degree of caution even before any regulatory outcome is known. That gap between price and Fair Ratio is what the detailed valuation work is designed to help you quantify in more depth. Explore the numbers behind Barclays's P/E valuation.
The Barclays Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Barclays valuation puzzle leaves off by spelling out which expectations for growth, margins and earnings would need to hold for the bank to trade meaningfully above or below its current share price on any given view. Each scenario sets out the assumptions sitting behind its own sense of fair value, so you can compare those inputs with Barclays' reported numbers as they arrive over time on the Community page.
One of the top community narratives on Barclays: 26% undervalued
"Combined with a price-to-earnings ratio of around 10, the price-to-book ratio suggests a puzzling lack of confidence in Barclays' future profitability and earnings durability..."
Discover why this Narrative puts Barclays at 26% undervalued.
One more piece of the Barclays puzzle worth checking
Valuation only tells part of the story for Barclays, because the real test is who is steering the bank, how their incentives are structured and whether those rewards truly align with your interests. See who runs Barclays and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com