
What ExxonMobil Doubters Got Wrong
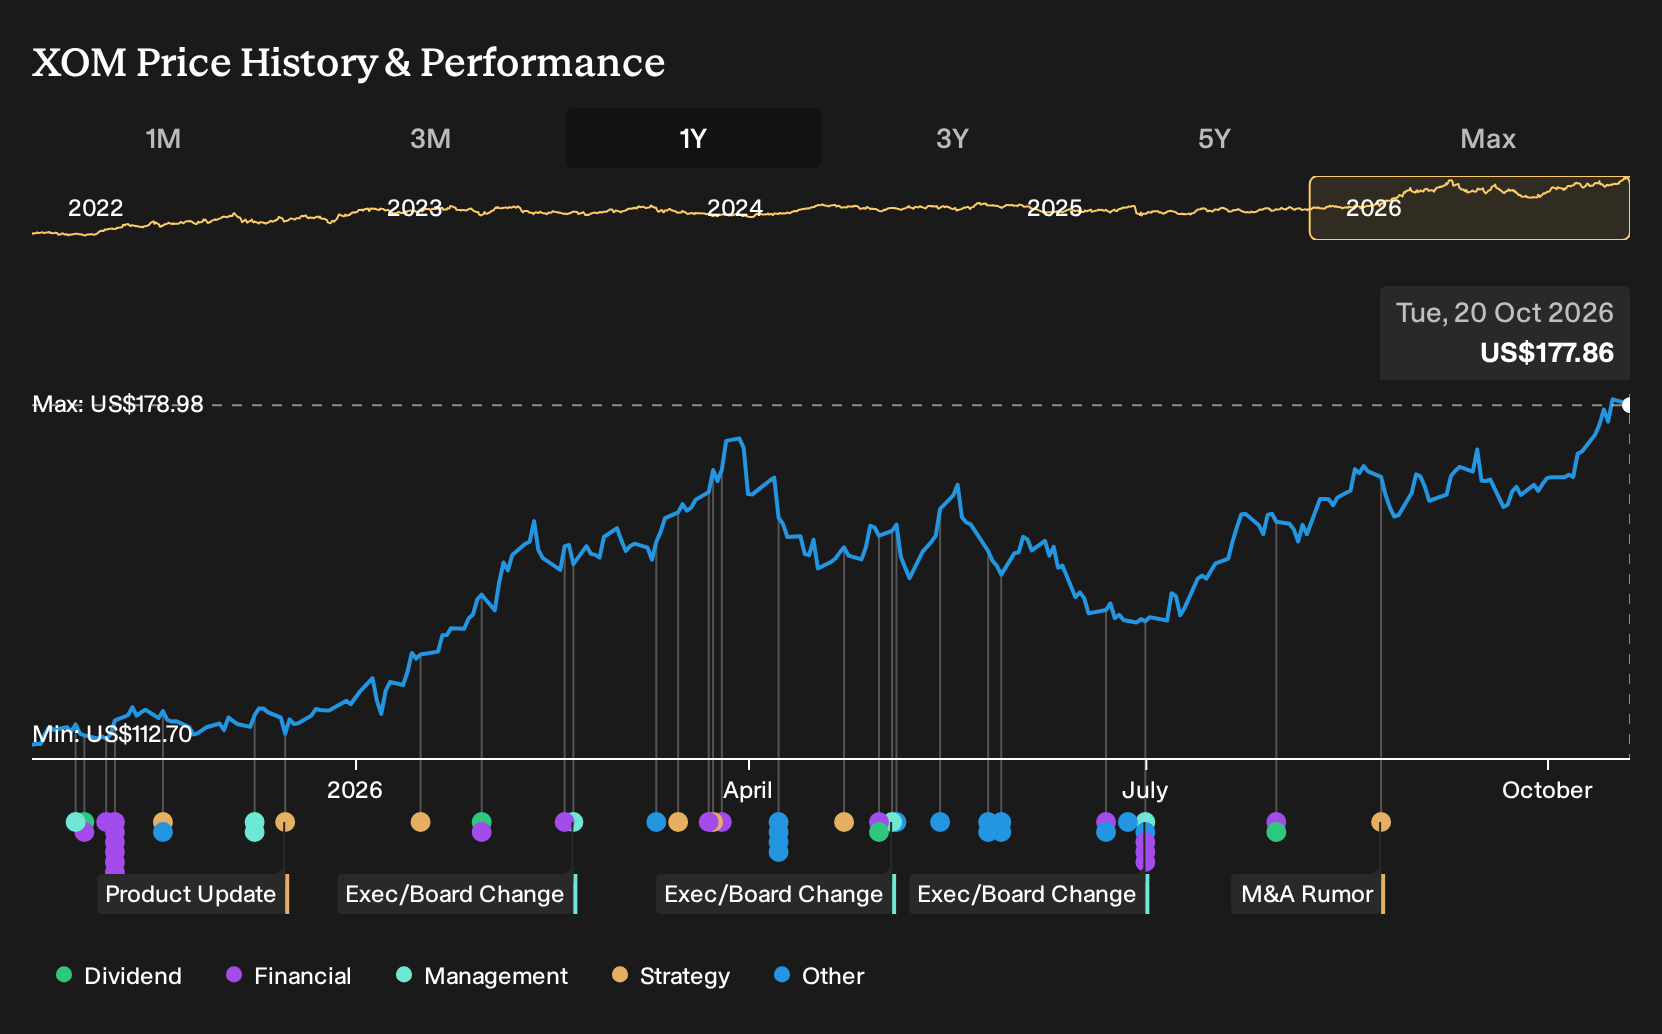
If ExxonMobil was on your watchlist rather than in your portfolio, the payoff over the last 12 months may feel like a near miss. Holding ExxonMobil over the past year would have returned 62.4%, including dividends. That result invites a sharper question. If the thesis about Guyana and Permian production growth expanding global energy solutions was already on record in October 2025, what specific confidence in those projects could have helped you treat it as more than just another bullish assumption?
If the move has made ExxonMobil harder to judge, start where the gap is still open and scan 34 high quality undervalued stocks.
The Argument You Would Have Been Weighing Up On ExxonMobil
The shares cost US$113 at the start of the period, which left you choosing between two very different stories about ExxonMobil.
On the optimistic side, the Guyana and Permian thesis implied a Fair Value near US$124, a price those production and efficiency assumptions pointed toward rather than a fixed truth. Supporters focused on higher volumes from advantaged assets and digital tools that could lower structural costs and keep net margins resilient.
The pessimistic view pinned Fair Value closer to US$78, based on expectations that revenue would fall about 1.0% a year and profit margins would sit near 7.9%. This camp stressed exposure to fossil fuel demand decline, regulatory pressure, and concerns that diversification into areas like lithium would struggle to offset shrinking hydrocarbon earnings.
What The Results Changed In The ExxonMobil Debate
The clearest new fact came from ExxonMobil’s Q2 2026 report. Revenue moved from US$79,477m to US$114,529m and net income from US$7,082m to US$14,525m, with net margin at 12.7% compared with 8.9%. That step up in profitability sat alongside record output in Guyana and the Permian, which supported the optimistic case more than the cautious one.
The lesson to recycle elsewhere is simple. When a thesis hangs on advantaged assets lifting profitability, do not just watch production headlines. Track whether net margin actually shifts in the direction that story promised.
What ExxonMobil's Price Seems To Be Saying Now
After a 62.4% gain over the past year, ExxonMobil trades at US$178. The selected Narrative places its Fair Value above that level, tying the gap to refining strength, advantaged barrels and heavy use of data and automation.
On that view, today's price still underplays how much lower cost production and digital savings could reshape ExxonMobil's earnings power across future cycles.
"Shift toward lower cost, higher return production as advantaged assets in Guyana, the Permian and LNG move toward roughly 65% of total output by 2030. This can influence revenue resilience and unit earnings across future cycles."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Which Company Could Surprise You Next?
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 22% below our estimate - embeds AI copilots and developer tools into existing enterprise cloud workflows.
- Company 2 - 33% below our estimate - converts a large gold reserve base into longer life production despite higher operating costs.
- Company 3 - 32% below our estimate - targets AI data centre hardware demand that strains current power and capacity buildouts.
Those are three of them. See all 25 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com