
Is Bank Of Montreal (TSX:BMO) Fairly Valued On Its October Bond Issuance?
Bank of Montreal (TSX:BMO) has been active in the bond market in October 2026, announcing and completing several fixed income offerings of senior unsecured notes with fixed coupons around 6%.
Against this backdrop of fresh bond issuance, Bank of Montreal’s equity story has been more mixed in the short term. The share price is at CA$235.4 after a 30 day share price return that declined 3.65% and a 90 day share price return that fell 6.68%. This comes even as the year to date share price return is 29.62% and the 1 year total shareholder return is 38.53%, extending to very large total shareholder returns over 3 and 5 years that point to strong long term compounding.
Scan beyond Bank of Montreal and compare its recent bond activity and long term compounding record with a hand picked list of solid balance sheet and fundamentals (7 results)
The recent pullback in Bank of Montreal after a strong year leaves an uncomfortable fork in the road. Is this where most of the gains are already booked, or is this the point where valuation still suggests further upside?
Most Popular Narrative: 8% Undervalued
On the most followed view, Bank of Montreal screens as modestly undervalued, with a fair value of CA$255.07 against the last close at CA$235.4. This puts the focus on how digital investment and U.S. execution could justify that gap.
Continued investment by Bank of Montreal in digital and AI powered banking tools such as SmartDecision underwriting, the Lumi chatbot and GenAI automation pilots is expected to support the targeted $1 billion PPPT benefit by 2030. This would mainly flow through improved efficiency, net margins and earnings.
Ongoing North American demographic trends that support demand for retail, commercial and wealth products, together with recent 7 to 8% growth in core operating deposits, give Bank of Montreal more room to grow fee income and spread revenue while keeping funding costs in check.
See why 96 investors see Bank of Montreal as 8% undervalued.
Result: Fair Value of CA$255.07 (UNDERVALUED)
Still, the whole narrative can wobble if Canadian credit quality weakens and investments in AI or U.S. banking push costs higher than Bank of Montreal expected.
Find out about the key risks to this Bank of Montreal narrative.
Another View: Multiples Paint A Richer Picture For Bank of Montreal
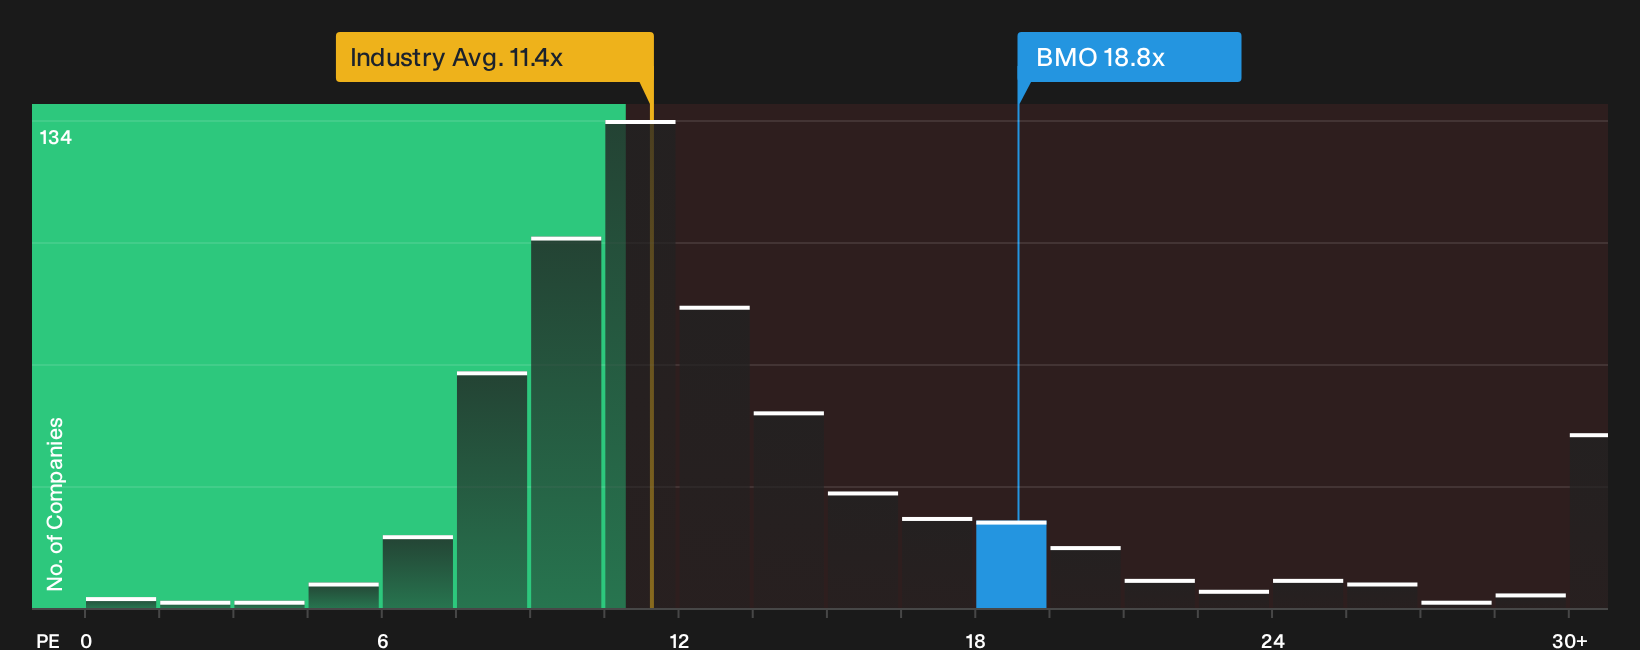
That modest 8% undervaluation story meets some resistance once you look at Bank of Montreal through simple P/E comparisons. The shares trade at 18.8x earnings, above the North American banks group on 11.4x, above peers at 16.5x, and slightly above a fair ratio of 18x. That premium hints at less room for error if growth or returns fall short of expectations.
For investors weighing whether that premium is justified by quality, execution or just optimism, the valuation breakdown based on this ratio can help separate conviction from comfort zone See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around Bank of Montreal can be hard to read. Check the full picture yourself, then weigh up the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Bank of Montreal?
If the mixed signals around Bank of Montreal have you thinking about diversification, now is the time to line up a few fresh contenders with different return profiles.
- Expand your opportunity set by reviewing 10 high quality undiscovered gems that pair quality fundamentals with less crowded investor attention.
- Strengthen portfolio resilience by scanning a 8 resilient stocks with low risk scores that focuses on companies with more measured risk scores.
- Target value focused opportunities by working through a 4 high quality undervalued stocks that filters for solid businesses trading below their assessed worth.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com