
Asian Undervalued Small Caps With Insider Activity For October 2026
In October 2026, Asian markets have been navigating a complex landscape marked by global inflationary pressures and shifts in investor sentiment away from large-cap growth stocks toward more value-oriented segments. Amid this backdrop, small-cap stocks in Asia are drawing attention for their potential resilience and growth prospects, especially those with notable insider activity that may indicate confidence in their future performance. Identifying strong candidates often involves looking at companies with solid fundamentals and the ability to adapt to changing economic conditions.
Top 10 Undervalued Small Caps With Insider Buying In Asia
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Security Bank | 4.0x | 0.8x | 21.99% | ★★★★★★ |
| Q Technology (Group) | 3.4x | 0.2x | 46.58% | ★★★★★☆ |
| Charter Hall Long WALE REIT | 8.5x | 12.0x | 40.33% | ★★★★★☆ |
| China Aircraft Leasing Group Holdings | 6.9x | 0.9x | 39.24% | ★★★★★☆ |
| Ho Bee Land | 12.3x | 2.5x | 47.01% | ★★★★★☆ |
| Centurion | 15.6x | 3.0x | 21.09% | ★★★★☆☆ |
| Australian Finance Group | 7.7x | 0.3x | 15.42% | ★★★★☆☆ |
| Aztech Global | 9.7x | 0.8x | -51.76% | ★★★★☆☆ |
| Clover | 16.7x | 1.8x | 45.67% | ★★★☆☆☆ |
| Citicore Energy REIT | 13.2x | 10.0x | 27.03% | ★★★☆☆☆ |
We'll examine a selection from our screener results.
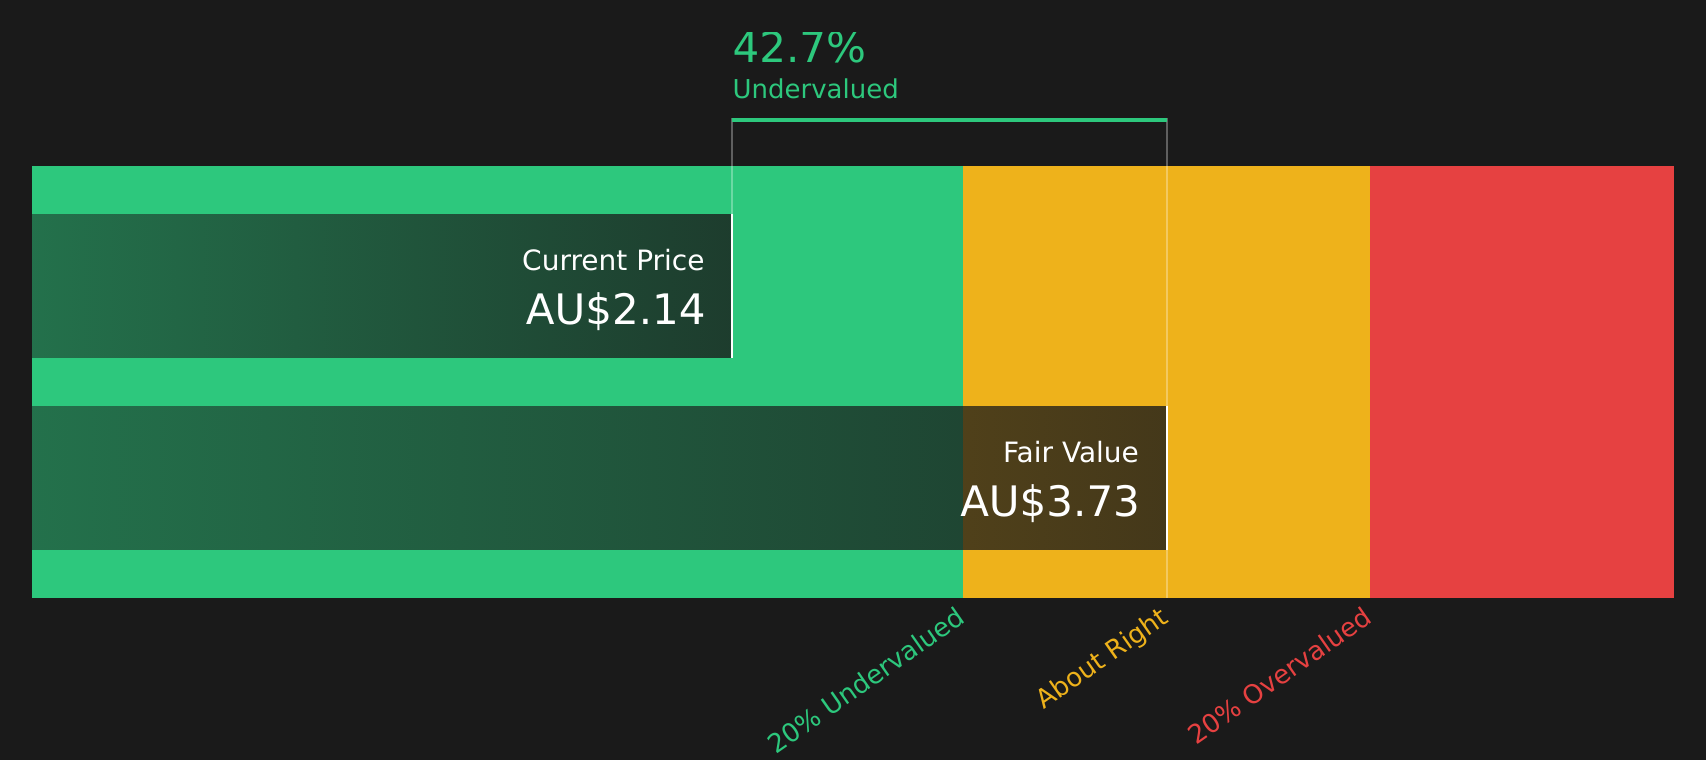
Perenti (ASX:PRN)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Perenti is a diversified global mining services group offering drilling, contract mining, and technology services with a market cap of A$1.24 billion.
Operations: Perenti generates revenue primarily from Drilling Services, Contract Mining Services, and Mining and Technology Services. The company has seen fluctuations in its net income margin over time, with a notable high of 22.90% in late 2018 before experiencing periods of negative margins in the early 2020s. As of the latest data, the net income margin is at 2.45%.
PE: 23.0x
Perenti, a player in the mining services industry, is drawing attention as an undervalued small-cap stock in Asia. Despite a dip in net income to A$18.76 million from A$120.62 million last year, insider confidence is evident with Vincent Nicoletti purchasing 125,000 shares for A$272,500. The company has initiated a share buyback program targeting up to 9% of its shares by July 2027 and forecasts significant earnings growth of 27.73% annually, suggesting potential future value enhancement.
- Dive into the specifics of Perenti here with our thorough valuation report.
Understand Perenti's track record by examining our Past report.
Qualitas (ASX:QAL)
Simply Wall St Value Rating: ★★★★★★
Overview: Qualitas is a company engaged in direct lending and funds management, with a market capitalization of A$1.15 billion.
Operations: Qualitas generates revenue primarily from its Funds Management segment, with a minor contribution from Direct Lending. Over recent periods, the company has experienced varying net income margins, reaching 31.78% by June 2026. Operating expenses are a significant component of costs, predominantly driven by general and administrative expenses.
PE: 16.0x
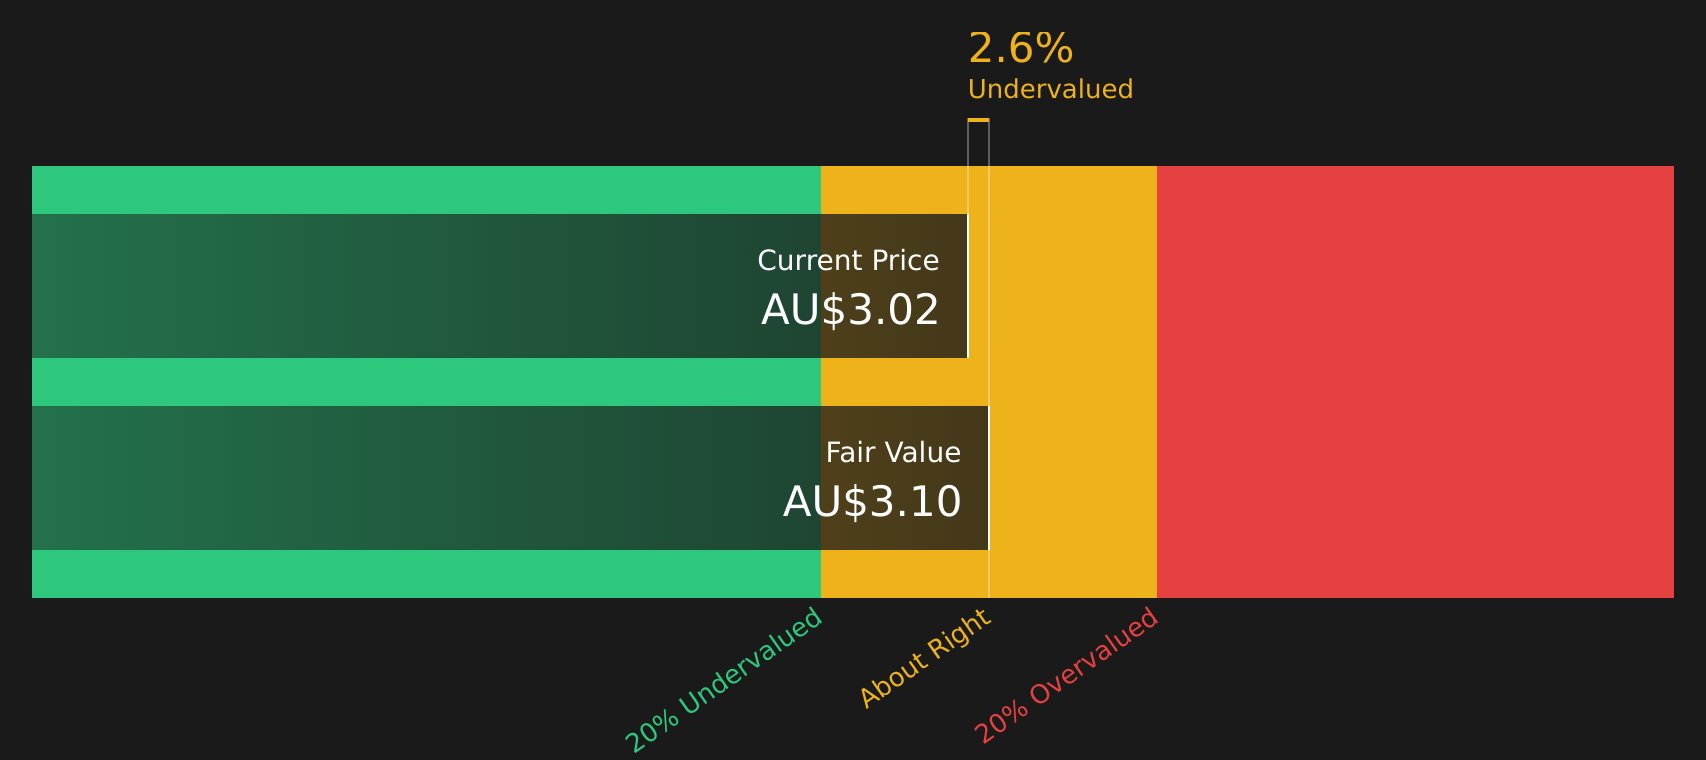
Qualitas, a small player in Asia's investment landscape, is gaining attention for its financial growth and insider confidence. In the year ending June 2026, revenue jumped to A$129.56 million from A$109.42 million previously, with net income rising to A$41.72 million from A$33.41 million. The company’s earnings per share also saw an increase, reflecting strong operational performance despite its reliance on external borrowing for funding. Future prospects look promising with earnings expected to grow annually by 17%.
- Navigate through the intricacies of Qualitas with our comprehensive valuation report here.
Review our historical performance report to gain insights into Qualitas''s past performance.
Philippine National Bank (PSE:PNB)
Simply Wall St Value Rating: ★★★★★☆
Overview: Philippine National Bank is a financial institution engaged in various operations including retail and corporate banking, treasury services, and other financial activities, with a market capitalization of ₱53.18 billion.
Operations: The bank generates revenue primarily from retail banking, corporate banking, and treasury operations. Retail banking contributes the largest share at ₱29.76 billion, followed by treasury at ₱23.64 billion, and corporate banking at ₱13.90 billion. The net income margin has shown variability over time with a notable peak of 40% in recent periods.
PE: 4.1x
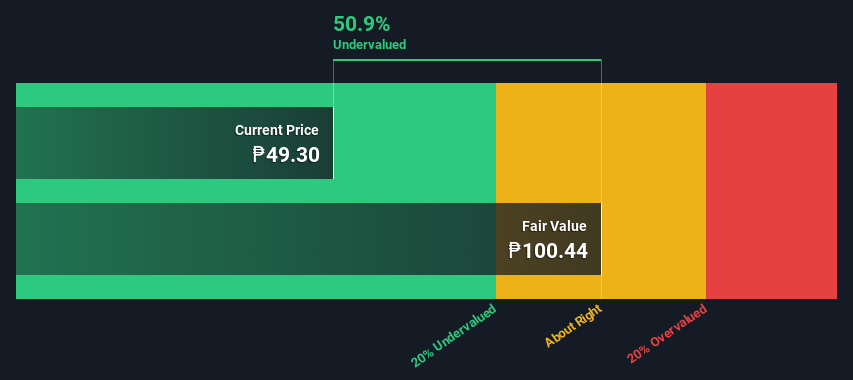
Philippine National Bank, a smaller player in the Asian financial landscape, has recently shown signs of insider confidence with Roberto Abastillas purchasing 1.16 million shares valued at PHP 68.67 million. Despite a low allowance for bad loans at 82% and a high level of non-performing loans at 5.1%, PNB's net income surged to PHP 8.21 billion in Q2 2026 from PHP 6.40 billion the previous year, reflecting strong earnings potential amidst strategic leadership changes in its IT and international banking sectors slated for late-2026.
- Click here to discover the nuances of Philippine National Bank with our detailed analytical valuation report.
Gain insights into Philippine National Bank's past trends and performance with our Past report.
Key Takeaways
- Click this link to deep-dive into the 58 companies within our Undervalued Asian Small Caps With Insider Buying screener.
- Already own these companies? Bring clarity to your investment decisions by linking up your portfolio with Simply Wall St, where you can monitor all the vital signs of your stocks effortlessly.
- Join a community of smart investors by using Simply Wall St. It's free and delivers expert-level analysis on worldwide markets.
Curious About Other Options?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com