
Is Hong Kong Zcloud Technology Construction (SEHK:9900) Worth Its Premium As P/S Questions Grow?
Debate around Hong Kong Zcloud Technology Construction (SEHK:9900) has intensified as its price to sales ratio sits well above construction peers, which is pushing investors to scrutinise project execution strength and the depth of its contract pipeline.
Recent trading has been choppy for Hong Kong Zcloud Technology Construction, with the share price rising 20.23% over 30 days but declining 5.93% year to date. At the same time, a 42.73% 1-year total shareholder return and a very large 3-year total shareholder return suggest that earlier momentum is still influencing how investors judge its premium P/S ratio.
Compare how Hong Kong Zcloud Technology Construction’s rich P/S stacks up against other contractors by scanning our hand picked list of solid balance sheet and fundamentals (202 results) for potential alternatives in the sector.
Hong Kong Zcloud Technology Construction now trades on a premium P/S after a sharp short term rebound and patchy year to date returns. Does that skew the risk reward toward fresh buyers or recent holders taking stock?
Price-to-Sales of 20.3x: Is it justified?
Valuation for Hong Kong Zcloud Technology Construction now hinges on a steep P/S tag of 20.3x, while the last close sits at HK$5.80 and peers trade on far lower sales multiples.
The P/S ratio compares the market value of the equity to its revenue base. For a contractor like Hong Kong Zcloud Technology Construction, that measure often reflects how confidently investors view the durability of the order book and the predictability of cash coming from long term works.
That confidence looks expensive. 9900 is flagged as costly relative to a peer average P/S of 12.8x, and the Hong Kong Construction industry reference point is even lower at 0.6x. The current premium suggests the market is paying up for future execution or contract wins without clear supporting earnings trends, especially with a value score of 0 and no fair P/S ratio available to indicate a level the market could reasonably move toward.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Sales of 20.3x (OVERVALUED)
Still, Hong Kong Zcloud Technology Construction carries clear risks, including reliance on a single Hong Kong revenue base and uncertainty around future contract awards or execution quality.
Find out about the key risks to this Hong Kong Zcloud Technology Construction narrative.
Another view on Hong Kong Zcloud Technology Construction’s value
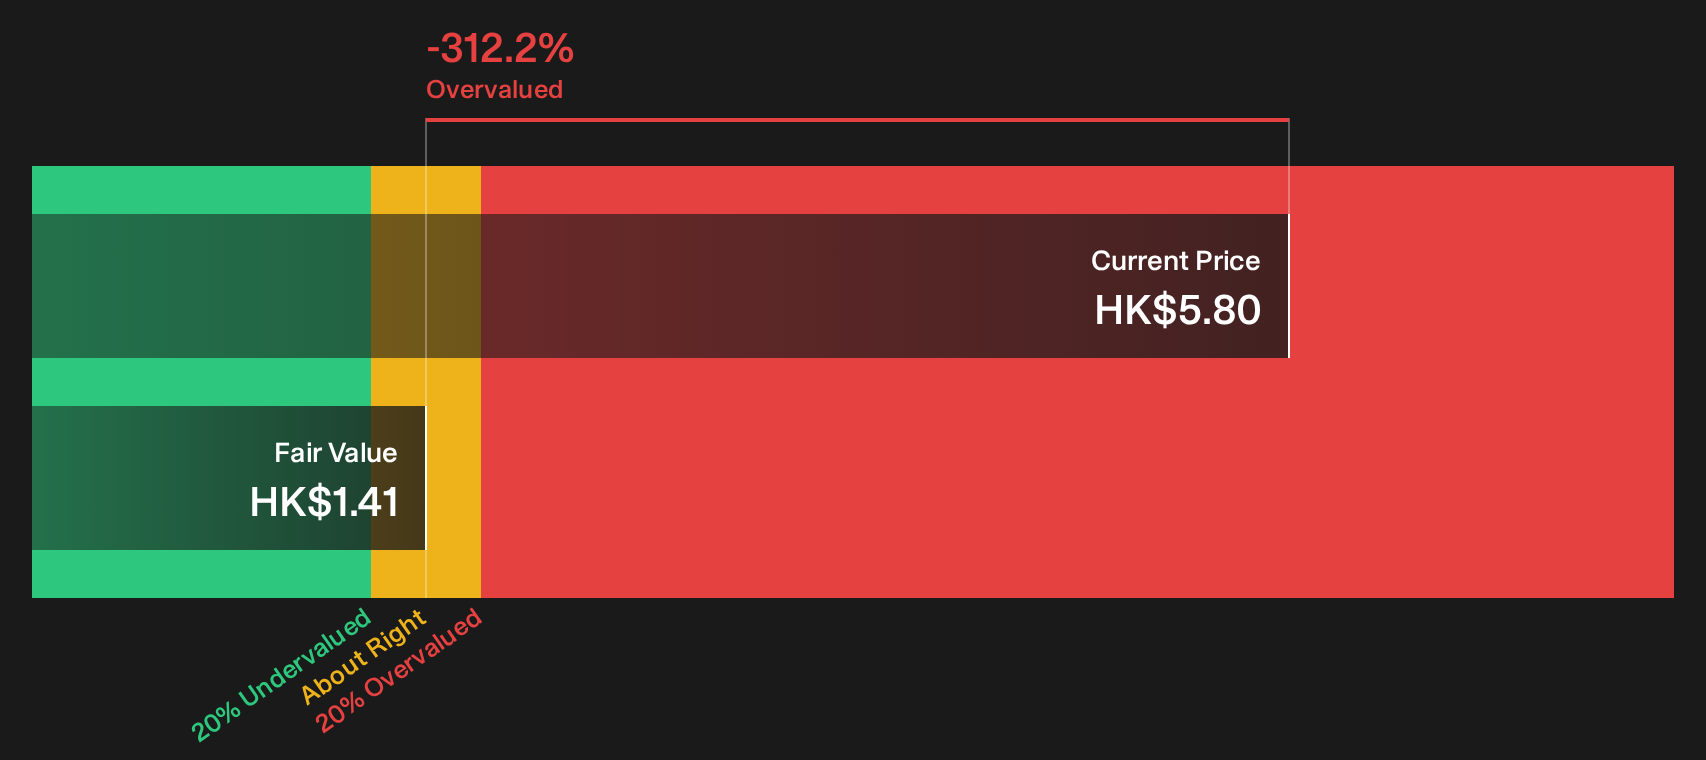
A second lens tells a similar story. Our DCF model estimates Hong Kong Zcloud Technology Construction’s future cash flow value at HK$1.41 per share, compared with the current HK$5.80 price, suggesting the stock looks expensive on cash flows as well. Is the market overconfident about what comes next?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Hong Kong Zcloud Technology Construction for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 192 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the tone here feels cautious, that is by design. It is exactly why you should review the data yourself and test your own thesis. To move from headline impressions to a firmer view on Hong Kong Zcloud Technology Construction’s downside, start by weighing the 3 important warning signs.
Looking for more investment ideas beyond Hong Kong Zcloud Technology Construction?
Do not stop your work with Hong Kong Zcloud Technology Construction alone. A broader watchlist can sharpen your judgement and reveal opportunities you would otherwise miss.
- Target companies that appear mispriced by screening for 192 high quality undervalued stocks that combine solid fundamentals with more modest expectations baked into their share prices.
- Strengthen your income focus by reviewing a curated 222 dividend fortresses that may offer higher yields with balance sheets you can scrutinise in detail.
- Tilt your watchlist toward resilience by scanning a 229 resilient stocks with low risk scores that filters for businesses with lower risk scores and more robust profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com