
Is InvenTrust Properties (IVT) Undervalued On Strong Leasing And NOI Trends?
Recent commentary around InvenTrust Properties (IVT) centers on a gap between its discounted cash flow estimate and where the shares currently trade. This is putting fresh attention on how reliable its future cash generation might be.
InvenTrust Properties has seen mixed share price momentum, with the stock up 7.53% year to date but down 17.04% over the past 90 days. A 1-year total shareholder return of 8.42% and 3-year total shareholder return of 35.57% suggest longer term holders have fared better than recent entrants at the current US$29.98 share price.
Compare InvenTrust Properties with a curated group of resilient real estate and income-focused plays by scanning the 32 resilient stocks with low risk scores that filter for balance sheet strength and lower risk profiles.
InvenTrust Properties now trades at roughly a 20% discount to both analyst targets and an intrinsic estimate, even after the recent pullback. Is that caution earned, or overdone, as the valuation work begins?
Most Popular Narrative: 18% Undervalued
The most followed narrative on InvenTrust Properties pegs fair value at $36.63 versus the recent $29.98 close. This points to a meaningful gap that depends on how well current leasing trends and recent acquisitions translate into future cash flows.
Embedded rent growth from contractual escalators and strong leasing spreads, reflected in Q2 2026 blended comparable lease spreads of 8.5% and a material contribution from rent bumps to same property NOI, provides a pipeline of internal revenue growth that can continue to support net operating income and FFO per share without relying solely on new acquisitions.
See why 0 investors see InvenTrust Properties as 18% undervalued.
Result: Fair Value of $36.63 (UNDERVALUED)
Still, the InvenTrust Properties story can break if acquisition yields fail to clear its 5.4% funding cost or if competition for Sun Belt retail assets squeezes returns.
Find out about the key risks to this InvenTrust Properties narrative.
Another View: InvenTrust Properties On Sales-Based Valuation
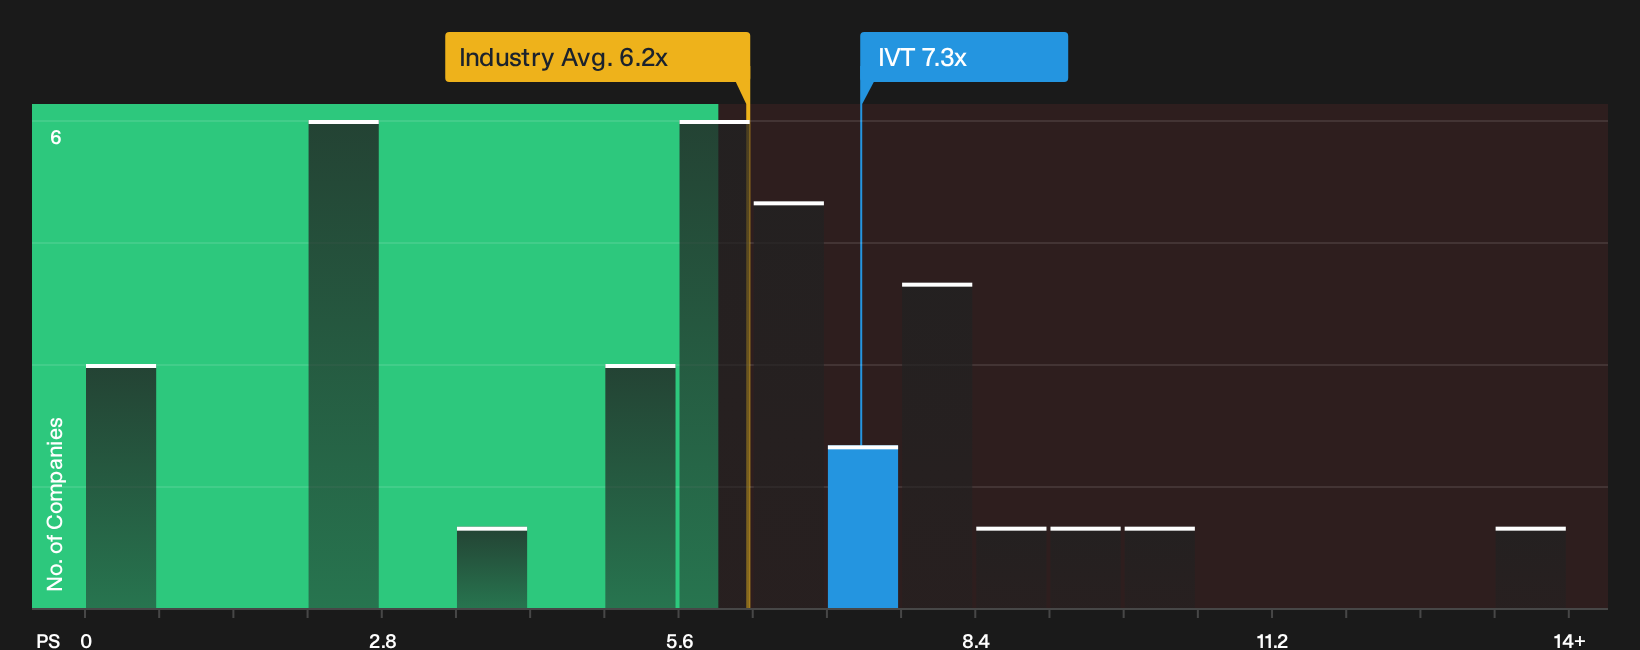
On a sales based yardstick, InvenTrust Properties looks less generous. The stock trades on a P/S ratio of 7.3x, which is richer than the US Retail REITs industry at 6.3x and well above a fair ratio of 5.1x. That gap points to valuation risk if sentiment cools before fundamentals catch up.
For a closer look at how this pricing stacks up against peers, and what the current P/S gap might signal for future returns, see what the numbers say about this price: See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around InvenTrust Properties can make the story feel unclear, so move quickly to review both sides and decide where you stand. To see the specific data behind the cautious points and the upside case, take a close look at the 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond InvenTrust Properties?
Do not stop with one opportunity. Use the Simply Wall Street Screener to uncover other stocks that better match your risk tolerance, income goals, and growth expectations.
- Spot potential bargains early by scanning 20 high quality undiscovered gems that combine solid fundamentals with under-the-radar market attention.
- Target resilience in tougher markets by reviewing the list of solid balance sheet and fundamentals (25 results) so you focus on businesses with stronger financial footing.
- Boost your income playbook by assessing the 8 dividend fortresses that filter for higher yields with an emphasis on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com